

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
CdTe Thin Film Solar Cell Market: Why 13.5% CAGR Through 2032 Changes Everything

CdTe Thin Film Solar Cell Market: Strategic Trends and Commercial Opportunities Beyond 2030
The cadmium telluride (CdTe) thin film solar market has transitioned from a niche alternative to a mainstream force in utility-scale photovoltaic deployment. Sustained revenue expansion from the early 2020s through the mid-2020s, followed by a projected double-digit compound annual growth rate through the early 2030s, underscores a structural shift in how large-scale solar assets are designed, financed, and operated. With total market valuation crossing the five-billion threshold in 2025 and continuing to scale toward the mid-teens by 2032, CdTe is no longer competing solely on cost alone. It is competing on balance-of-system efficiency, land utilization, supply chain resilience, and regulatory alignment. For executives navigating energy transition portfolios, the question has shifted from whether CdTe merits attention to how its growth trajectory intersects with corporate decarbonization timelines, grid interconnection constraints, and domestic manufacturing incentives.
Market Landscape and Defining Constraints
The CdTe thin film sector has demonstrated consistent valuation growth over the historical period, with momentum carrying forward into the forecast window. This expansion reflects not just volume scaling but a maturation of the technology stack: improved deposition uniformity, better module-level power conversion, and increasingly refined balance-of-system assumptions that favor lower weight and higher temperature tolerance. The trajectory suggests that CdTe has crossed a commercial viability threshold in regions where land availability, interconnection queues, and capital efficiency dictate project economics. Yet the growth path is not frictionless. Several structural tensions are reshaping how developers, manufacturers, and financiers evaluate CdTe deployments.
PW Consulting
Key Commercial Tributaries Shaping the Next Cycle
One persistent challenge is the tension between scaling production capacity and maintaining material availability without creating volatility in tellurium sourcing. While CdTe modules consume significantly less semiconductor material per watt than crystalline silicon alternatives, tellurium remains a byproduct of copper refining, and its supply dynamics can shift with mining output, metal price cycles, and refining capacity. This does not make the material scarce by default, but it does require strategic procurement, long-term supply agreements, and recycling pathways that reduce exposure to commodity dislocation.
A second challenge lies in navigating a policy environment that rewards domestic manufacturing and clean energy deployment but introduces compliance complexity. Incentives tied to local content, labor standards, and supply chain transparency can accelerate adoption in certain markets while raising the barrier to entry in others. Companies that treat regulatory alignment as an afterthought risk delays in permitting, reduced eligibility for support mechanisms, or higher financing costs if counterparties perceive compliance risk.
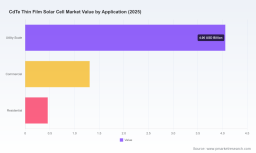
A third challenge is the growing differentiation between rigid and flexible form factors across application contexts. Rigid CdTe modules continue to anchor utility-scale economics, where scale, predictable output, and balance-of-system savings dominate decision criteria. Flexible variants open different deployment scenarios, including curved surfaces, lighter mounting structures, and non-traditional infrastructure, but they must prove consistent performance and durability under varied environmental conditions. The market is not choosing one format over the other; it is dividing by use case, and the strategic implication is that product roadmaps must be aligned to application-specific value propositions rather than generalized claims.
Core Drivers Shaping Market Direction
Multiple forces are converging to push CdTe further into the mainstream of large-scale solar planning. The most consequential are technological progress, regulatory momentum, demand-side economics, and supply chain economics. Each driver reinforces the others, but their interaction is where the commercial opportunity becomes clearer.
Technology Innovation and Efficiency Gains
CdTe has benefited from steady laboratory and production-path efficiency improvements, narrowing the performance gap with competing technologies while preserving inherent advantages in material intensity and thermal behavior. Record efficiency levels achieved in research settings have reached the low twenty-three percent range, while leading manufacturers have advanced manufacturing-line performance toward the low twenty-two percent range in recent years. These gains matter because even modest efficiency improvements translate into lower land requirements, reduced racking costs, and better energy yield per installed watt in hot climates. The commercial narrative is shifting from “CdTe is cheaper to make” to “CdTe can deliver a more favorable system-level cost profile in specific deployment conditions.” For developers and asset owners, this reframing expands the addressable opportunity beyond pure cost parity and into performance-matched site selection.
Dye Sensitized Solar Cell Market
Policy and Regulatory Alignment
Government attention to CdTe has become more explicit, with policy documents and program offices highlighting cost reduction, domestic scale-up, and utility-scale deployment as priorities. This kind of directional clarity matters to capital allocation because it reduces uncertainty around long-term demand visibility. When public agencies outline technology-specific priorities, it often signals potential support pathways, research coordination, and procurement alignment. At the same time, the regulatory landscape remains uneven across jurisdictions. Some markets are simplifying incentives for local manufacturing and clean generation, while others impose trade, content, or traceability requirements that need to be factored into multi-region strategies. The companies gaining traction are those aligning their expansion plans with policy trajectories rather than betting against them.
Demand-Side Behavior and Asset Economics
Demand for CdTe is being reinforced by how large-scale solar projects are financed and evaluated. Utility-scale buyers increasingly prioritize not just module price but total installed cost, land efficiency, degradation profiles, and operating temperature characteristics. CdTe’s lower material intensity and higher temperature tolerance can improve yield in environments where silicon modules may lose more output to heat-related efficiency losses. Meanwhile, corporate procurement and integrated energy strategies are pushing developers to reduce development risk, shorten construction timelines, and secure equipment from suppliers with visible capacity pipelines. This demand profile favors manufacturers that can offer scale, predictable delivery, and performance documentation that aligns with lender and insurer requirements.
Supply Chain Structure and Cost Resilience
Cost dynamics in CdTe are shaped by a combination of material efficiency, manufacturing footprint, and logistics. Because CdTe cells consume far less semiconductor material than crystalline silicon technologies, the input cost profile can be more resilient when semiconductor demand spikes elsewhere in the electronics or battery ecosystems. However, resilience depends on how well manufacturers manage tellurium procurement, module assembly scale, and regional production location. Recent expansion activity in domestic manufacturing reflects a broader recognition that supply chain proximity can reduce lead-time risk, improve logistics predictability, and align with incentive structures. The strategic lesson is that CdTe competitiveness is not just about cell efficiency; it is about the end-to-end architecture of production, sourcing, and delivery.
Competitive Positioning and Landscape Evolution
The competitive landscape in CdTe remains concentrated, with a small group of manufacturers commanding the majority of market share. This concentration is not accidental. CdTe commercialization requires specialized deposition know-how, scale economics, long-term supply commitments, and a track record that satisfies utility procurement standards. First Solar exemplifies this profile, with a product focus centered on commercial CdTe thin-film modules built for utility-scale deployments, supported by established manufacturing facilities and continued research toward higher efficiency. Its strategic positioning rests on integrating cell technology with system-level value: module design choices that reduce balance-of-system cost, a manufacturing footprint that supports delivery consistency, and ongoing R&D intended to improve conversion performance while maintaining commercial reliability.
Strategic Differentiation in a Concentrated Market
Leaders in this space do not win purely on module pricing. Their differentiation tends to emerge from a combination of manufacturing scale, supply chain control, deployment track record, and technology roadmaps that are credible into the next product generation. Recent operational and financial milestones have shown how execution can reinforce market confidence. Record sales and income growth in CdTe-related business during a recent first-quarter reporting period signaled that demand visibility and production execution can align in favorable cycles. At the same time, the start of construction on a new large-capacity CdTe manufacturing facility in the United States highlighted a deliberate move to expand domestic production capacity, reduce supply-chain latency, and align with regional policy incentives. Together, these moves illustrate a broader pattern: competitive advantage is being built through capacity expansion synchronized with demand growth and regulatory momentum.
Consolidation, Entry Barriers, and Emerging Competition
Market concentration is likely to persist in the near term because credible scale, performance documentation, and utility-grade reliability create high entry barriers. New entrants can disrupt specific segments, particularly in flexible or specialized applications, but displacing incumbent share in utility-scale procurement requires more than product specifications. It requires financing acceptance, bankability, warranty confidence, and integration into developer procurement pipelines. This dynamic suggests a landscape where incumbents consolidate share through scale and execution, while smaller players compete around niche formats, regional partnerships, or differentiated use cases. The more interesting strategic tension is not imminent fragmentation, but the gradual broadening of the value chain: more integrated module-plus-balance-of-system offerings, more recycling and material recovery initiatives, and more partnerships linking manufacturers with developers, financiers, and equipment providers.
Forward Outlook: Three Strategic Trends
Looking across the current trajectory and the forces shaping it, three trends are likely to define the CdTe market over the next several years. Each carries a distinct commercial implication, and each carries uncertainty that decision-makers should price into planning assumptions.
Solar Cell Metal Paste Market
Trend One: Utility-Scale Dominance with System-Level Optimization
Utility-scale applications will remain the primary growth engine, but the competitive edge will increasingly come from system-level optimization rather than module cost alone. Land constraints, interconnection delays, and balance-of-system expenses mean that developers will favor solutions that reduce structural materials, lower installation complexity, and deliver reliable yield under local climate conditions. CdTe’s material efficiency and thermal characteristics position it well for this optimization path. The commercial opportunity lies in aligning module specifications with site-specific performance models, financing criteria, and operations planning. The risk is that over-optimizing for one metric may understate total lifecycle performance, especially if degradation behavior, soiling, or temperature profiles are not fully reflected in procurement assumptions.
Trend Two: Domestic Manufacturing as a Strategic Asset
As policy frameworks continue to emphasize local production and supply chain resilience, manufacturers with visible domestic capacity pipelines will gain an advantage in markets where incentives, procurement rules, or supply risk perception favor regional production. Expansion events in the United States reflect this direction, but similar dynamics can emerge elsewhere if governments tie support to local content, jobs, or supply stability. The opportunity for companies is to use manufacturing geography as a strategic asset rather than merely a production decision. The uncertainty comes from policy continuity, permitting timelines, and the risk that demand growth may not fully absorb new capacity if project development slows or interconnection bottlenecks persist.
Trend Three: Material Strategy and Circularity as Competitive Moats
Tellurium management, recycling pathways, and end-of-life module recovery will become more central to commercial strategy. Because CdTe’s material advantage depends on efficient use of semiconductor inputs, any supply disruption or regulatory shift around material handling can influence cost and market access. Companies that invest early in closed-loop material strategies, supplier diversification, and recovery infrastructure may convert a procurement challenge into a competitive moat. This trend also intersects with increasing attention to lifecycle accountability across the solar value chain. The risk is that circular infrastructure can require capital, coordination, and time, and the commercial payoff may be uneven across regions and regulatory regimes.
Action Considerations for Decision-Makers
The CdTe market is large enough and dynamic enough that generic strategy prescriptions are unlikely to be useful. More valuable is a clearer line of sight between a company’s role in the value chain and the forces currently reshaping procurement, capacity, and policy alignment.
-
For manufacturers and technology developers: prioritize roadmap investments that improve efficiency without compromising reliability, and treat supply chain resilience as a core product attribute. Capacity expansion decisions should be tied not only to near-term order books but to anticipated regional incentives, developer procurement cycles, and interconnection timelines. Efficiency gains are necessary, but bankability, delivery consistency, and lifecycle material strategy are increasingly what determine long-term share.
-
For investors and capital allocators: evaluate CdTe exposure through system-level economics rather than module price alone. Demand visibility, capacity timing, policy alignment, and balance-of-system value all influence whether growth translates into durable returns. Watch for indicators such as domestic manufacturing progress, utility procurement patterns, and any shifts in material sourcing or recycling infrastructure that could alter cost structures. Diversification across formats and applications may reduce dependence on a single deployment cycle.
-
For procurement teams and project developers: use CdTe where its system-level characteristics match site conditions and financing requirements. Evaluate performance models against local temperature profiles, land constraints, and installation complexity, and ensure that module specifications are supported by credible warranty and degradation documentation. Where domestic production incentives or supply chain resilience criteria matter, incorporate manufacturing geography and supply continuity into sourcing decisions rather than treating them as secondary considerations.
The broader takeaway is that CdTe has moved into a phase where its commercial trajectory depends less on proving basic viability and more on executing within a complex set of market, policy, and supply chain conditions. Companies that understand the interplay between efficiency progress, regional manufacturing strategy, material sourcing, and utility-scale economics will be better positioned to capture value as the market scales. For teams that need more granular segmentation, regional deployment patterns, application-level nuance, or scenario-based assessments of capacity and policy shifts, deeper intelligence can shorten the distance between strategic intent and execution.
For detailed analysis of this topic, please visit the official page: CdTe Thin Film Solar Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com