

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
X-Ray Detectors Market: Why 6.5% CAGR Through 2032 Changes Everything

The X-Ray Detectors Market at an Inflection Point: Strategic Trends and Commercial Opportunities
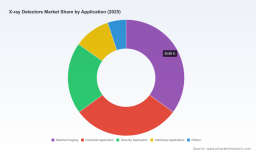
The global X-ray detectors market has matured into a multi-billion-dollar ecosystem defined by steady expansion, technological refinement, and shifting procurement dynamics. Valued at approximately 355 million USD in 2020, the market reached 487 million USD by 2025, reflecting a compound annual growth rate of 6.5 percent. Projections indicate the sector will approach 757 million USD by 2032, driven by synchronized upgrades in medical imaging infrastructure, industrial inspection requirements, and security screening demands. While the headline trajectory appears linear, the underlying mechanics are anything but static. Regional demand patterns, modality transitions, and regulatory pacing are reshaping how manufacturers position their portfolios and how end-users evaluate capital expenditure. For executives and investors tracking this space, the central question is no longer whether growth will continue, but where value will concentrate and which strategic moves will separate margin-accretive players from commoditized participants.
Understanding the current state of the X-ray detectors market requires moving beyond aggregate revenue figures and examining the structural forces that dictate pricing power, adoption curves, and competitive positioning.
-
From replacement cycles to capability upgrades. Procurement decisions are increasingly tied to performance thresholds rather than routine turnover. Higher detective quantum efficiency, improved modulation transfer function, and reduced pixel sizes are now mainstream expectations rather than premium differentiators.
-
Capital constraints meet technology ambition. Hospitals, industrial facilities, and security agencies operate under tighter operating budgets, yet the clinical and operational case for advanced detectors continues to strengthen. This tension creates a selective upgrade environment where financing models, refurbished components, and phased deployments gain strategic relevance.
-
Concentration remains moderate, but differentiation is intensifying. The market is not dominated by a handful of suppliers, leaving room for specialized entrants, regional champions, and cross-industry players to capture niches through application-specific engineering and integration expertise.
The market is expanding, but expansion alone does not guarantee profitable positioning. Several structural challenges are redefining the rules of engagement.
Transitioning Imaging Standards and Performance Expectations
Radiography workflows are no longer satisfied with basic digital capture. Diagnostic accuracy requirements, workflow integration, and throughput expectations are pushing detector specifications toward higher resolution, lower noise, and faster readout capabilities. This shift creates a performance arms race in which incremental engineering gains must be paired with system-level compatibility, software integration, and serviceability. Manufacturers that treat detectors as standalone components risk losing relevance as integrated imaging ecosystems become the default purchasing unit.
Regulatory Friction and Time-to-Market Pressure
Approval pathways for X-ray detectors continue to tighten, particularly where clinical or public safety claims intersect with evolving regulatory expectations. Substantial equivalence demonstrations, performance metric validation, and post-market conformity requirements add development overhead and extend launch timelines. This dynamic favors companies with mature quality systems, established predicate device strategies, and the ability to absorb compliance costs without losing product cadence. For newer entrants, regulatory navigation is not merely a procedural hurdle; it is a strategic barrier that shapes market access and competitive velocity.
Cost Structure Compression and Budget Sensitivity
Service and maintenance budgets in healthcare settings have experienced sustained pressure, while manufacturing scale in East Asia is compressing detector pricing. The combined effect is a market where mid-tier institutions can upgrade within existing capital envelopes, but where traditional pricing models face erosion. At the same time, demand for refurbished detector components is gaining traction as organizations balance performance aspirations against budget realism. This environment rewards manufacturers that can offer credible lifecycle economics, flexible configuration options, and durable hardware economics rather than relying on premium positioning alone.
Key Drivers Reshaping the Market
Growth in the X-ray detectors market is not being pulled by a single force. It is being shaped by converging technical, regulatory, demand-side, and supply-side dynamics that interact differently across medical, industrial, and security use cases.
Flat Panel X Ray Detectors Market
Technical Innovation and System-Level Integration
Detector technology is advancing along multiple vectors simultaneously. Flat-panel and solid-state designs continue to improve image metrics while enabling more compact form factors and broader deployment flexibility. Recent product activity illustrates how performance refinement is becoming a core competitive lever. In mid-2025, Canon Medical Systems and Konica Minolta introduced new detector lines with improved pixel size, modulation transfer function, and detective quantum efficiency for mobile X-ray units, incorporating Vieworks detectors and imaging software. Around the same period, Carestream Health expanded its DRX-Evolution Plus and DRX-Compass systems with Lux HD 35 and Lux HD 43 detectors, reinforcing the industry’s focus on clinical efficiency and mobile workflow compatibility.
These developments point to a broader pattern: detectors are increasingly optimized not only for image quality, but for portability, integration with software ecosystems, and adaptability across fixed and mobile configurations. For manufacturers, the strategic implication is clear. Superior pixel performance must be paired with usable system integration, reliable service support, and compatibility with existing clinical or industrial workflows. For buyers, the opportunity lies in technologies that improve throughput and diagnostic confidence without disrupting established operating procedures.
Policy, Reimbursement, and Regulatory Alignment
Demand for X-ray imaging is strongly influenced by reimbursement structures and approval pathways. In the United States, diagnostic X-ray tests are covered under Medicare when performed in outpatient settings or as part of initial preventive physical examinations, reinforcing the relevance of high-quality detector solutions in routine clinical environments. At the same time, FDA 510(k) clearances for X-ray detectors require demonstration of substantial equivalence to predicate devices, with performance metrics including modulation transfer function and detective quantum efficiency. Stricter regulatory approvals, including FDA 510(k) and EU MDR certifications, increase development costs and slow new technology launches, but they also create a competitive moat for organizations that can move through the process efficiently.
The regulatory environment is therefore a double-edged sword. It raises the barrier for fragmented, low-quality entrants while rewarding established players with robust compliance infrastructure and predictable product pipelines. For investors and corporate strategists, regulatory capacity is increasingly a strategic asset, not just a compliance function. Companies that can shorten time-to-clearance without sacrificing performance credibility gain advantage in both clinical and security segments where certification timing directly affects revenue realization.
Demand-Side Behavior and Operational Economics
End-user behavior is shifting from technology adoption for its own sake toward value justified by workflow efficiency, diagnostic reliability, and total cost of ownership. In healthcare, the emphasis is on reducing retakes, improving patient throughput, and integrating detectors with mobile and stationary systems in ways that minimize operational disruption. In industrial and security applications, the demand logic centers on inspection accuracy, detection sensitivity, and the ability to deploy imaging solutions in constrained environments. This demand evolution favors solutions that balance image performance with practical usability and maintenance economics.
A related shift is the growing acceptance of lifecycle-based procurement. With hospital service budgets tightened by roughly 13 percent in recent years, interest in refurbished detector components has increased. Rather than signaling a collapse in new equipment demand, this trend suggests a more segmented market in which premium new systems coexist with cost-conscious refurbishment and component-level replacement strategies. Manufacturers and channel partners that can address both new-capital and lifecycle-extension needs are better positioned to retain share across economic cycles.
Supply Chain Scale and Competitive Pricing Dynamics
Manufacturing scale in East Asia is compressing detector pricing, enabling mid-tier hospitals to upgrade within existing capital budgets. This development expands the addressable market by lowering financial barriers to adoption, but it also intensifies price competition and puts pressure on margin structures for suppliers that cannot offset pricing with differentiation. The strategic response is not simply to compete on cost, but to build value through performance credibility, integration depth, regional service coverage, and application-specific customization. In practice, the pricing environment is pushing the market toward a bifurcated structure: cost-competitive volume segments and performance-leading specialty segments.
Competitive Landscape and Leadership Strategies
The competitive field in X-ray detectors is broad, spanning established electronics and imaging conglomerates, specialized detector manufacturers, and regional players with strong local service footprints. The market remains moderately concentrated, leaving room for distinct strategic positions rather than a single dominant template. What separates leading players is not merely scale, but the ability to align detector technology with application needs, regulatory readiness, and integration economics.
Several companies illustrate how strategic positioning is evolving.
-
Varex Imaging Corporation emphasizes digital flat-panel detectors for medical imaging systems, with seamless integration between detectors, X-ray tubes, and software for high-resolution applications. This system-aligned approach supports customers seeking cohesive performance rather than isolated component upgrades.
-
Hamamatsu Photonics K.K. focuses on high-performance flat-panel and solid-state detectors used in medical radiography and industrial applications, leveraging deep expertise in photon detection technologies to address both clinical and non-medical imaging demands.
-
Canon Inc. advances flat-panel detectors integrated into digital X-ray systems with improved modulation transfer function and detective quantum efficiency for diagnostic imaging, reinforcing a strategy centered on diagnostic confidence and system-level refinement.
-
Carestream Health, Inc. highlights DRX series digital radiography detectors and mobile X-ray solutions for clinical efficiency, appealing to institutions prioritizing flexible deployment and workflow mobility.
-
Konica Minolta, Inc. pursues flat-panel and solid-state detectors for high-quality medical imaging with smaller pixel sizes and superior image metrics, aligning with the broader push toward higher-resolution diagnostic capabilities.
-
Thales Group extends solid-state and flat-panel X-ray detectors across medical and security applications, illustrating how detector technology can bridge very different end-use requirements through robust engineering and application versatility.
PW Consulting -
Teledyne Technologies Incorporated provides digital imaging solutions and detectors for X-ray systems, including Teledyne DALSA components, positioning around component-grade capabilities and specialized imaging architectures.
-
Rayence Co., Ltd. offers high-performance flat-panel detectors for medical applications, with recent regulatory milestones underscoring the importance of clearance pathways in expanding commercial availability.
-
Detection Technology Plc specializes in solid-state detectors for X-ray imaging, representing a focused strategy around detector core technology and materials expertise.
-
Vieworks Co., Ltd. delivers digital flat-panel detectors for radiology and industrial use, combining medical and cross-sector applicability to diversify demand exposure.
-
Trixell centers on flat-panel detectors for medical imaging, competing in a segment where integration compatibility and image consistency are critical purchasing criteria.
-
Agfa-Gevaert Group covers digital radiography and computed radiography detectors, balancing modern flat-panel offerings with established computed radiography capabilities that remain relevant in certain procurement environments.
-
Fujifilm Holdings Corporation supplies flat-panel detectors for digital X-ray systems, drawing on broader imaging heritage to support system integration and image processing ecosystems.
-
Analogic Corporation focuses on advanced X-ray detectors and imaging components, often serving applications where component reliability and interoperability are paramount.
-
Siemens Healthineers provides integrated detectors and solutions for X-ray imaging systems, with recent activity reflecting the value of cleared, system-ready technologies in accelerating adoption.
The competitive story is not simply a roster of names, but a pattern of differentiation. Leading players tend to cluster around several strategic postures. Some compete through system integration and software compatibility, positioning detectors as enablers of seamless workflows. Others compete through raw imaging performance and materials science, emphasizing resolution, noise characteristics, and detector efficiency. A third group competes through application breadth, spanning medical, industrial, and security markets to diversify demand and leverage shared core technologies. A fourth group competes through regional service strength and procurement flexibility, which becomes especially important where budget sensitivity and lifecycle economics shape buying decisions.
Market Structure Evolution: Consolidation, Specialization, and Entry Barriers
The market is unlikely to collapse into a single dominant architecture. Instead, it is evolving toward a layered structure. At one level, larger imaging and electronics players continue to strengthen their position by embedding detectors into broader platform ecosystems. At another level, specialized detector companies retain advantage by focusing on core sensor technology, niche applications, or regional service networks. New entry remains possible, but the combination of performance expectations, regulatory clearance requirements, and integration complexity raises the practical barriers to meaningful competition.
Strategic consolidation is likely to occur more through capability acquisition and partnership than through blunt market consolidation. Detector technology increasingly intersects with software, tube integration, mobile deployment, and workflow optimization. Companies that can combine detector performance with application-specific engineering and regulatory readiness will capture more value than those competing on detector specifications alone. Recent regulatory and product activity supports this interpretation: cleared systems and refined detector lines are being launched not as isolated components, but as parts of broader imaging solutions that promise faster deployment, better compatibility, and clearer clinical or operational value.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of market development will likely be defined by how companies navigate the intersection of performance improvement, procurement economics, and regulatory cadence. Three trends appear particularly consequential.
Performance Convergence Becomes the Baseline, Not the Differentiator
Improved pixel size, modulation transfer function, and detective quantum efficiency are rapidly moving from premium features to baseline expectations. Over the next several years, competitive advantage will shift toward how well detectors fit into real-world workflows, how reliably they operate in mobile and fixed configurations, and how effectively they support service continuity. The commercial opportunity lies in bundling detector performance with integration services, software compatibility, and deployment models that reduce total operating friction. The risk is that undifferentiated performance claims become table stakes, compressing pricing for suppliers that cannot demonstrate system-level value.
Expanded Access Through Cost Compression and Refurbishment Ecosystems
Lower detector pricing driven by manufacturing scale is broadening access for mid-tier institutions and expanding the pool of feasible upgrades. This opens new volume opportunities, but also encourages a more segmented market where refurbished components and lifecycle extensions play a larger role. Companies that build credible refurbished supply chains, component-level service offerings, and flexible financing models can capture demand that would otherwise slip to informal or lower-quality channels. The strategic risk is margin dilution if pricing pressure outpaces value differentiation, making it essential to pair cost competitiveness with clear performance and service guarantees.
Regulatory Pace as a Strategic Filter
Approval requirements will continue to shape market entry and product timing. FDA 510(k) clearances and EU MDR-related conformity expectations increase development costs and slow launches, but they also create a filtering mechanism that favors organizations with disciplined regulatory execution. Over the coming years, the ability to move cleared technologies into market-ready systems will be a meaningful competitive advantage, especially when paired with demonstrated performance equivalence and reliable imaging metrics. The uncertainty lies in how regulatory expectations evolve across regions and applications, which can shift timing advantage between competitors and alter the pace of adoption for new detector architectures.
These trends suggest that the market’s next growth phase will reward companies that treat detectors as part of a broader value proposition rather than as standalone hardware. Opportunities will emerge in mobile imaging optimization, industrial inspection specialization, security screening upgrades, and lifecycle services that extend the useful life of existing capital. Risks will concentrate in segments where pricing erosion, regulatory delay, or integration gaps weaken commercial viability.
Strategic Implications for Decision Makers
For executives, investors, and procurement leaders, the X-ray detectors market offers a structurally attractive growth path, but only when approached with clear positioning and disciplined execution.
For Manufacturers and Technology Providers
-
Align detector development with system-level integration. Image metrics matter, but compatibility with tubes, software, mobile deployment, and service networks increasingly determines commercial success.
-
Build differentiated positions through application specificity. Medical, industrial, and security segments have distinct performance and economics requirements; broadGeneric offerings risk competing in the most price-sensitive zones.
-
Strengthen regulatory and quality infrastructure as a strategic asset. Faster, more predictable clearance pathways can translate directly into competitive timing advantages and revenue realization.
For Investors and Corporate Development Teams
-
Evaluate value based on integration depth and application reach, not detector specifications alone. Companies that link detector technology to workflow efficiency and lifecycle economics are better positioned to sustain margins.
-
Watch for consolidation through capability rather than scale. Partnerships, component acquisitions, and regional service expansion may create more durable advantage than broad headcount or plant expansion.
-
Monitor pricing pressure points and refurbishment demand as indicators of market segmentation. These dynamics can reveal where premium positioning is sustainable and where volume strategies will dominate.
For Procurement Leaders and End-User Organizations
-
Evaluate total cost of ownership rather than sticker price. Detector selection should account for integration effort, service availability, downtime risk, and compatibility with existing systems.
-
Consider phased and lifecycle-aware procurement strategies. As refurbished components and cost-compressed new systems expand options, organizations can balance performance goals with capital constraints without sacrificing operational continuity.
Radiation Detector Market -
Prioritize solutions with clear performance metrics and regulatory readiness. Verified equivalence, documented image metrics, and predictable support reduce implementation risk and improve long-term value capture.
Moving From Direction to Detail
The X-ray detectors market is expanding along a clear trajectory, but the strategic value lies in understanding where growth is most defensible, where pricing and regulatory dynamics will reshape competition, and how technology refinement translates into commercial advantage. Aggregate growth tells part of the story; segment-specific demand, application economics, regulatory timing, and integration depth determine who captures the most value.
Detailed breakdowns of regional dynamics, product-type shifts, application-level demand patterns, and company-level developments can sharpen planning significantly. For teams evaluating market entry, portfolio optimization, investment allocation, or procurement strategy, a comprehensive report with segmented data and customized scenario analysis provides the granularity needed to convert high-level trends into executable decisions. The opportunity is not simply to track where the market is going, but to identify the specific moves that will create durable advantage as detector performance, cost structures, and regulatory expectations continue to evolve.
For detailed analysis of this topic, please visit the official page: X-ray Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com