

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Desiccant Dehumidifier Market 2032: Why 6.35% CAGR Signals a Structural Shift

Strategic Shifts and Commercial Opportunities in the Desiccant Dehumidifier Market
Market Landscape and Core Challenges
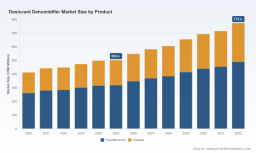
The global desiccant dehumidifier market has demonstrated consistent expansion over the past half-decade, moving from approximately 412.45 million USD in 2020 to 502.4 million USD in 2025. Forward projections indicate a steady climb toward 773.2 million USD by 2032, supported by a compound annual growth rate of 6.35 percent across the 2026 to 2032 horizon. This trajectory reflects more than incremental demand; it signals a structural shift in how critical environments manage moisture, energy, and operational reliability. While conventional condensation-based systems continue to serve standard comfort and residential applications, industries requiring precise humidity control, low dewpoints, or operation in sub-ambient conditions are increasingly turning to desiccant technologies as a non-negotiable infrastructure component.
The market structure itself reveals a moderately concentrated landscape. The three largest players command roughly 54 percent of total revenue, while the top five extend their combined share to 62 percent. Such concentration suggests that scale, established technical reputations, and long-term service networks play a significant role in winning high-stakes contracts. Yet the remaining market share is widely distributed across regional specialists, application-focused integrators, and emerging product developers. This fragmentation is not a sign of weakness; rather, it creates room for differentiated positioning, niche innovation, and targeted partnerships, especially in sectors where humidity control is tightly coupled to process yield, equipment longevity, and regulatory compliance.
Despite the favorable growth outlook, the industry is navigating several inflection points that will shape competitive outcomes over the next cycle. First, energy efficiency expectations are rising at a pace that challenges legacy system architectures. Facility operators and engineering teams are no longer evaluating dehumidifiers solely on moisture removal capacity; they are scrutinizing total energy consumption, integration with existing HVAC infrastructure, and the ability to maintain performance without inflating operating expenses. Second, regulatory and standards-driven requirements are reshaping procurement criteria. Cleanroom specifications, refrigerant phase-down pressures, and energy conservation mandates are influencing not just which technologies are permitted, but how quickly specifications must adapt to remain compliant. Third, supply chain resilience and material availability are becoming strategic concerns. The performance of desiccant media, the durability of rotating wheel assemblies, and the availability of precision control components all affect product reliability and lead times, particularly when demand spikes across multiple regions simultaneously.
These challenges do not diminish the market outlook; they redefine the basis of competition. Manufacturers and buyers alike are moving from a commodity mindset toward a performance-and-integration mindset, where the value of a dehumidification system is measured by its ability to stabilize environments, reduce lifecycle costs, and adapt to tightening operational rules.
Key Demand Drivers
Technology Innovation and Performance Breakthroughs
Technological advancement is one of the most visible forces expanding the addressable market for desiccant dehumidification. Recent product introductions highlight a clear direction: systems are becoming more scalable, more precise, and more compatible with conventional building and industrial infrastructure. Munters’ launch of the MX3 dehumidifier series in March 2026 illustrates this trend. Positioned as a scalable platform for full humidity and temperature control based on desiccant technology, the series reflects an engineering emphasis on flexibility across applications rather than a single-point solution. In parallel, Mojave Energy Systems introduced the AquaDry hydronic liquid desiccant air handling unit in May 2026, designed to deliver 25°F supply dewpoints using conventional chilled water. The significance of this development lies in its efficiency implication: by extending chiller capacity and improving efficiency by 20 percent, the product shows how desiccant systems can complement rather than compete with existing cooling infrastructure.
These innovations matter because they lower the practical barriers to adoption. When desiccant equipment can be integrated into standard chilled-water systems, when platforms can scale across different project sizes, and when dewpoint control becomes more predictable, procurement teams have stronger justification to specify desiccant solutions in new construction, retrofits, and mission-critical upgrades. The broader implication is that technology leadership is increasingly defined by integration capability, controllability, and energy optimization, not simply by moisture removal alone.
PW Consulting
Policy, Regulatory Pressure, and Standards Alignment
Regulatory and standards environments are exerting steady pressure on both equipment design and purchasing behavior. In the United States, the Department of Energy’s proposal to amend energy conservation standards for dehumidifiers, with a final rule anticipated around 2025 and 2028 referenced as a compliance benchmark, signals that efficiency requirements will continue to tighten. For manufacturers, this means product roadmaps must account for regulatory floors that may eliminate less efficient designs over time. For buyers, it means that today’s specification choices are increasingly linked to tomorrow’s compliance posture.
At the same time, international frameworks are reinforcing the case for desiccant adoption in specific settings. Strict energy efficiency and management practices associated with ISO 50001 are encouraging facilities that aim to reduce greenhouse gas emissions to consider desiccant dehumidifiers as part of broader decarbonization strategies. In parallel, EU regulations on refrigerants and energy efficiency have accelerated the transition to desiccant technology with zero ozone depletion potential, a shift reflected in a meaningful share of new commercial building projects. These regulatory dynamics are not abstract; they directly influence equipment selection in regions where compliance risk, operational reporting, and sustainability targets are closely tied to capital decisions.
Standards related to controlled environments are equally influential. ISO 14644 requirements for cleanroom operation in electronics and semiconductor manufacturing emphasize the need for precise humidity control, reinforcing desiccant dehumidifiers as a preferred option where process sensitivity is high. In such environments, humidity stability is not a comfort parameter; it is a quality and yield parameter, which makes the performance characteristics of desiccant systems especially valuable.
Demand-Side Shifts in Critical and Process-Sensitive Applications
Demand-side behavior is changing as more sectors recognize humidity control as a core operational requirement rather than a peripheral building service. Food and pharmaceutical operations continue to represent some of the most sensitive application spaces, where moisture management intersects with preservation, contamination control, and regulatory-grade environment stability. Electronics and semiconductor-related activities add another layer of demand intensity because tightly controlled cleanroom conditions are essential to manufacturing integrity. Energy and chemical applications further broaden the market base, particularly where process drying, corrosion mitigation, or moisture-sensitive storage create persistent operational needs.
Construction and adjacent sectors also contribute to demand, though often through different adoption logic. In these settings, desiccant equipment may be specified for temporary environmental control, moisture mitigation during build-out, or specialized indoor conditions where conventional systems are less effective. What unites these diverse applications is a growing expectation that humidity control should be robust, predictable, and compatible with broader facility goals. Buyers are increasingly willing to invest in systems that reduce downtime risk, protect sensitive assets, and support consistent process outcomes. This shift elevates desiccant dehumidifiers from optional equipment to strategic infrastructure in many procurement decisions.
Supply Chain and Cost Structure Considerations
Cost dynamics and material conditions are shaping how products are designed, sourced, and priced. The desiccant media landscape provides a useful example. Silica gel is positioned to lead the desiccants market with an estimated 38 percent revenue share in 2026, driven by strong adsorption capacity and established performance characteristics. For equipment manufacturers, the prevalence of such materials matters because media selection influences efficiency, regeneration requirements, service intervals, and overall system design. Any disruption in the availability or pricing of key materials can affect product economics and delivery timelines.
Beyond materials, the cost structure of desiccant dehumidifiers is influenced by precision component supply, manufacturing scale, and the cost of servicing complex installations over time. As competition intensifies and efficiency expectations rise, companies are under pressure to optimize not only initial equipment cost but also total cost of ownership. This encourages designs that reduce energy draw, extend service life, and simplify maintenance. It also encourages suppliers to strengthen inventory planning, diversify sourcing where possible, and align production with demand patterns that may vary by region and application. The practical result is that cost competitiveness in this market is becoming multidimensional, blending product engineering, operational efficiency, and supply chain discipline.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Leading Players
The competitive environment is shaped by a combination of established multinational players, application-focused specialists, and regional integrators. Munters Group, headquartered in Stockholm, continues to emphasize desiccant-based humidity and temperature control as a core offering, with recent product launches reinforcing its focus on scalable platforms and broad application coverage. Its positioning suggests an emphasis on technical breadth and repeatable engineering solutions that can be adapted across industrial, commercial, and process-sensitive environments.
Condair Group, based in Zurich, brings a comparable emphasis on controlled moisture management within broader HVAC and humidification/dehumidification contexts. Its strategy reflects the value of integrated environmental control, where desiccant dehumidification is positioned as part of a larger system logic rather than a standalone device. Bry-Air Inc., operating from Michigan, has long been associated with desiccant drying and humidity control solutions, and its market presence underscores the importance of application-specific expertise, especially where low dewpoint performance and robust drying capability are required.
Desiccant Dryer Market
Mojave Energy Systems, located in Sunnyvale, California, has carved out a distinct position through innovation that targets efficiency and integration with existing chilled-water infrastructure. Its liquid desiccant approach demonstrates how a company can differentiate by solving a practical operational problem: achieving aggressive dewpoint control while improving system efficiency. Climate by Design International, based in Minnesota, has focused on mission-critical applications where precise environmental control is essential. Its acquisition by Modine Manufacturing Company in October 2025 highlights a growing pattern in which larger industrial or HVAC-oriented firms absorb specialized capabilities to expand their desiccant dehumidification reach and strengthen their position in critical-environment segments. Trotec Laser GmbH, headquartered in Austria, represents the presence of firms whose desiccant-related offerings are tied to specific operational contexts and application expertise, reinforcing the broader theme that specialization remains a viable competitive route.
Differentiation and Competitive Advantage
Across these players, differentiation is increasingly built on several recurring advantages. One is application-specific engineering. Companies that can demonstrate proven performance in cleanrooms, drying processes, pharmaceutical environments, or mission-critical facilities gain credibility with buyers who face stringent operating requirements. Another is integration design. Products that connect cleanly with chilled-water systems, building management controls, or existing HVAC architecture reduce installation friction and improve operational continuity. A third is efficiency. As energy standards tighten and operating costs remain a central concern, the ability to deliver moisture control with lower energy penalties becomes a strong commercial argument.
Service capability and long-term support also matter. Desiccant systems often involve rotating wheels, regeneration configurations, media maintenance, and control calibration. Buyers evaluate not only initial equipment performance but also the reliability of service networks, spare part availability, and technical responsiveness. In a moderately concentrated market, these factors can be decisive, especially when projects require sustained uptime or when facilities operate under tight environmental tolerances.
Market Evolution: Consolidation, Differentiation, and New Entry
The landscape is evolving along multiple axes. Consolidation is evident where larger manufacturing or HVAC groups acquire specialized firms to expand technology coverage and market access. The Modine acquisition of Climate by Design International is a clear example of this logic, adding desiccant dehumidification technology and capacity for mission-critical applications to a broader portfolio. Such moves can accelerate product development, expand service reach, and strengthen competitive positioning in high-value segments.
At the same time, differentiation remains powerful. Exhibitions and trade presence continue to play an important role in market development. Dryer Air-Handling Equipment Co., Ltd. exhibited at AHR Expo 2026 in Las Vegas and participated at ARBS 2026 in Melbourne, displaying desiccant dehumidification solutions and reinforcing the relevance of face-to-face technical engagement in a market where performance claims, configuration options, and application fit need close examination. These events show that even as product platforms mature, customer education and technical demonstration remain essential.
New entry and expansion are also possible where innovation addresses an unresolved operational pain point. Liquid desiccant approaches, scalable platform designs, and efficiency-focused configurations all represent potential entry points for firms that can prove measurable advantages in real installations. The market is therefore unlikely to become uniformly consolidated; instead, it is more likely to sustain a layered structure in which broad-line players compete on scale and integration while specialists compete on application depth, unique technology, or service intensity.
Future Trends and Forward Outlook
Trend One: Efficiency-Led System Design Will Become the Default Expectation
Over the next three to five years, efficiency will likely move from a desirable feature to a baseline requirement. With regulatory trajectories pointing toward tighter energy standards and with facility operators under pressure to manage operating costs, desiccant systems will be judged increasingly on how well they work alongside other plant equipment. This trend favors designs that reduce regeneration energy demand, leverage waste heat or conventional chilled water intelligently, and integrate smoothly with facility controls. For commercial opportunity, this creates demand for upgraded retrofits, hybrid configurations, and engineering services that can optimize existing installations rather than simply replace equipment.
Trend Two: Critical-Environment Applications Will Drive Higher-Value Specifications
As cleanroom, pharmaceutical, food, electronics, and mission-critical applications continue to expand or modernize, specification quality will become more important. Buyers in these segments are likely to prioritize repeatability, dewpoint precision, documented compliance support, and reliability under continuous operation. This trend opens opportunities for manufacturers and integrators that can provide application-tailored solutions, validated performance data, and service models aligned with sensitive operating environments. It also raises the stakes for suppliers that cannot demonstrate credible control over the conditions their equipment is expected to maintain.
Trend Three: Regional Diversification and Localized Support Will Gain Importance
Although concentration among leading firms remains significant, regional demand patterns and local support requirements will continue to shape market dynamics. Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa each present distinct application mixes, regulatory contexts, and procurement cultures. Over time, successful players are likely to strengthen localized engineering support, regional service capacity, and market-specific product configurations. For businesses evaluating expansion or partnership, this suggests that presence and responsiveness in the target region may be as important as global brand recognition.
Risks and Uncertainties
Several uncertainties bear watching. Regulatory timelines can shift, and the pace of final rule implementation may influence product planning and procurement cycles. Energy price volatility and operational budget constraints could slow adoption in some segments if efficiency gains are not sufficiently compelling. Material supply conditions, including availability and cost of key desiccant media and precision components, could affect production stability and pricing. In addition, if conventional dehumidification technologies improve their efficiency or if alternative moisture-control methods gain traction in certain applications, competition may intensify in segments that today appear firmly aligned with desiccant solutions. These risks do not weaken the market outlook, but they reinforce the need for scenario-aware planning.
Actionable Guidance for Decision Makers
For Manufacturers and Product Strategists
Prioritize integration and efficiency in the next product cycle. Systems that can connect with conventional chilled-water infrastructure, offer scalable configurations, and deliver measurable efficiency gains are more likely to win specification attention in both new projects and retrofits. Equally important is the ability to support mission-critical and process-sensitive applications with documented performance and reliable service. Manufacturers should also review supply chain planning for desiccant media and precision components, since material conditions and lead times can shape both cost structure and customer confidence.
Household Dehumidifiers Market
For Investors and Corporate Development Teams
Focus on the segments where humidity control is tied to quality, yield, compliance, or uptime. Food and pharmaceuticals, electronics, energy, and chemical applications represent environments where desiccant dehumidification is often linked to core operational outcomes rather than peripheral comfort. Consolidation trends also suggest that specialized capabilities can become valuable acquisition targets, especially where they add technology, application depth, or mission-critical credibility to a broader portfolio. When evaluating opportunities, consider not only revenue potential but also the defensibility of application expertise, service capacity, and efficiency-oriented product design.
For Procurement and Facility Leaders
Evaluate desiccant dehumidifiers as part of a total-environment and total-cost strategy. The most relevant questions are not limited to moisture removal capacity; they extend to dewpoint performance, energy interaction with existing systems, maintenance requirements, and the supplier’s ability to support the specific operating conditions of the facility. Where regulations, cleanroom standards, or sustainability goals affect operations, ensure that equipment choices align with anticipated compliance and efficiency expectations. Specifying with a long-term view can reduce rework risk, improve operational stability, and better position the facility for evolving standards.
The desiccant dehumidifier market is advancing along a clear but multi-layered path. Growth is supported by expanding demand in critical applications, evolving efficiency expectations, and continued product innovation that makes desiccant systems more compatible with real-world infrastructure. At the same time, competitive success will depend on how well companies navigate regulatory change, material and supply chain conditions, and the increasing expectation that dehumidification equipment deliver measurable operational value over its full lifecycle. For decision makers seeking a more detailed view of segment dynamics, regional variation, application-specific demand patterns, and tailored strategic options, the broader research record offers a deeper competitive map and a more granular basis for planning.
For detailed analysis of this topic, please visit the official page: Desiccant Dehumidifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com