

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Furfural Market 2026: Beyond the 5.6% CAGR Story, What's Really Driving Growth to $844.2M

Strategic Shifts and Commercial Opportunities in the Furfural Market Through 2032
The furfural market is entering a period of structural expansion, driven by the convergence of bio-based material demand, regional feedstock advantages, and evolving downstream applications. From a base of approximately 580.0 million USD in 2025, the market is projected to reach 844.2 million USD by 2032, reflecting a compound annual growth rate of 5.6 percent. The trajectory since 2020 shows a consistent upward path, with revenue climbing from 420.5 million USD to 561.5 million USD by 2024, before settling into the current baseline. This growth is not merely cyclical; it reflects deeper shifts in how industrial resins, solvents, and chemical intermediates are sourced, formulated, and integrated into broader sustainability strategies. For executives and investors, the question is no longer whether the market is expanding, but where value will concentrate and which strategic moves will capture it.
PW Consulting
Mapping the Current Landscape
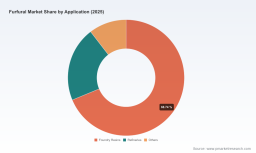
The market’s structure reveals several defining characteristics. Asia Pacific accounts for the largest revenue share, reflecting both production scale and proximity to key agricultural feedstocks. North America and Europe follow as substantial markets, each with distinct demand profiles shaped by industrial manufacturing practices and regulatory expectations. Latin America and the Middle East and Africa round out the geographic footprint, contributing smaller but strategically important volumes tied to regional biomass availability and niche applications. In terms of product types, furfuryl alcohol dominates the revenue composition, underlining its central role in foundry resins and specialty chemical pathways. Solvents and chemical intermediates represent smaller but increasingly relevant segments, particularly as downstream formulators seek bio-derived alternatives with tailored performance characteristics. By application, foundry resins remain the primary demand driver, while refineries and a broader set of industrial uses provide additional volume and diversification. The industry’s competitive structure is moderately concentrated, with the top five players capturing roughly 38 percent of total revenue and the top three holding about 32 percent. This level of concentration suggests room for differentiated positioning while also indicating that scale, feedstock access, and product specialization will continue to matter.
Critical Challenges and Inflection Points
Despite the positive growth arc, the market faces several challenges that will shape competitive outcomes over the next few years.
-
Raw material dependency and feedstock volatility remain central concerns. Corn cob currently represents the dominant feedstock, driven by its high pentosane content and comparatively efficient processing economics. Yet reliance on a single feedstock category introduces exposure to agricultural cycles, regional supply disruptions, and shifting crop economics. Suppliers that can diversify feedstock streams without compromising yield or cost structure will be better positioned to manage volatility.
-
Product differentiation and quality consistency are becoming more demanding as downstream users integrate furfural-derived materials into higher-value applications. The launch of a new high-purity furfural grade for bio-polymer synthesis and advanced resin applications, with improved color stability, signals that performance thresholds are rising. Formulators and end-users increasingly expect not only bio-based content but also predictable handling, stability, and compatibility across complex resin and solvent systems.
-
Capacity expansion and integration decisions are creating both opportunity and execution risk. Investments aimed at expanding production capacity, particularly where biomass processing is integrated into existing mills or agricultural operations, can unlock scale advantages. However, these projects require careful alignment of feedstock logistics, capital deployment, and downstream offtake. Misaligned expansion can lead to utilization gaps or margin pressure, especially in a market where regional feedstock abundance does not automatically translate into competitive cost leadership.
Key Drivers Shaping Market Direction
Technological Innovation and Process Breakthroughs
Advancements in biomass conversion and product purification are reshaping what furfural can deliver. The development of high-purity grades tailored for bio-polymer synthesis and advanced resin applications demonstrates how incremental improvements in color stability and consistency can open new use cases. At the same time, feedstocks such as sugarcane bagasse are expected to grow faster than other input categories, with a projected CAGR of 7.2 percent, supported by abundance in sugar-producing regions. This shift matters because feedstock choice influences not only cost but also the narrative around sustainability, supply security, and regional competitiveness. Producers that can convert diverse agricultural residues into reliable, high-quality output while maintaining cost discipline are likely to gain an edge in both traditional and emerging applications.
Policy and Regulatory Environment
Regulatory and policy dynamics are increasingly influential in shaping demand and investment priorities. Bio-based content expectations, industrial emissions considerations, and broader sustainability targets are nudging formulators and manufacturers toward renewable feedstock alternatives. While furfural has long been used in foundry resins and solvents, the regulatory backdrop is helping reframe it as part of a wider shift toward bio-derived chemical inputs. This does not automatically guarantee demand growth, but it does create a more favorable context for applications where bio-based positioning aligns with compliance goals, customer preferences, and corporate sustainability commitments. The practical effect is a market where regulatory signals reinforce product development priorities and encourage investment in grades that meet evolving performance and traceability expectations.
Demand-Side Shifts in Consumer and Enterprise Behavior
Downstream demand is evolving as enterprises seek materials that fit both performance and sustainability criteria. Foundry resins continue to anchor demand, but there is growing interest in solvent and intermediate applications where bio-based attributes can differentiate offerings in competitive procurement environments. In parallel, advanced resin and bio-polymer pathways are drawing attention from formulators who value color stability, purity, and consistent handling characteristics. This demand-side evolution is not a sudden replacement of conventional materials; rather, it is a gradual migration in specific applications where bio-derived inputs can deliver comparable performance while supporting broader environmental and branding objectives. Companies that understand which applications are most sensitive to these shifts can prioritize product grades and commercial messaging accordingly.
Supply Chain and Cost Structure Dynamics
Cost competitiveness in furfural production is closely tied to feedstock logistics, regional biomass availability, and integration with existing agricultural or processing operations. Feedstock advantages are often regional rather than universal, which means that producers with access to reliable, low-cost biomass streams can achieve meaningful margin resilience. At the same time, supply chain design matters increasingly for quality consistency and delivery reliability. Investments that connect feedstock sourcing, conversion capacity, and downstream distribution in a coherent way can reduce exposure to price swings and improve customer confidence. Conversely, fragmented supply chains or overreliance on a single input source can undermine cost stability and limit flexibility when market conditions change.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of integrated agricultural processors, specialty producers, and regional exporters, each with a distinct strategic posture.
-
Central Romana Corporation operates from the Dominican Republic with a focus on furfural and furfuryl alcohol production derived from sugarcane bagasse within integrated sugar operations. This model highlights the value of linking furfural production to an existing agricultural and processing ecosystem, which can improve feedstock reliability and operational efficiency.
-
Illovo Sugar Africa has built a presence in South Africa by producing furfural from sugarcane bagasse and maize residues, with capacity expansion planned at its Saiccor Mill. The company’s approach underscores how regional sugar and residue streams can support scalable production, especially where mill integration reduces feedstock handling costs.
-
Pennakem LLC operates in the United States, manufacturing furfural from agricultural residues for foundry resins, solvents, and chemical intermediates. Its positioning reflects a broad downstream orientation, which can help balance demand fluctuations across application areas.
-
Silvateam S.p.A. in Italy emphasizes bio-based furfural and furfuryl alcohol derivatives with a focus on high-quality biomass-derived products. This quality-oriented stance is well suited to customers seeking consistent performance and a clear bio-based value proposition.
-
Trans Furans Chemicals bvba, based in Belgium, specializes in furfural and derivatives, including a newer high-purity grade designed for bio-polymers. Its product development signal illustrates how specialty grades can create differentiation in applications where color stability and purity are decision factors.
-
KRBL Ltd in India produces furfural from rice husk within integrated rice milling operations. This feedstock strategy leverages an agricultural byproduct stream that can offer cost and availability advantages in regions with strong rice processing infrastructure.
-
Hongye Holding Group Corporation Ltd is a major Chinese producer and exporter with integrated biomass processing and a broad distribution network. Scale, export reach, and integrated operations can support competitive positioning in both domestic and international markets.
-
Lenzing AG, based in Austria, supplies furfural-based specialty chemicals, including inputs for dissolving pulp and bio-based materials. Its role shows how furfural can intersect with higher-value fiber and material pathways, broadening the application context beyond traditional industrial uses.
Collectively, these players illustrate a market where strategic positioning is shaped by feedstock access, product specialization, and downstream alignment. Some competitors rely on integration with sugar or rice operations to secure feedstock and reduce cost exposure. Others pursue product differentiation through higher-purity grades or specialty derivatives that meet specific application requirements. The trend appears to be moving toward a blend of consolidation among scale-advantaged producers and fragmentation among niche specialists targeting performance-sensitive applications. New entrants and expanding producers are likely to focus on either regional feedstock advantages or product grades that address emerging bio-polymer and advanced resin needs. In this environment, the most resilient strategies will combine reliable feedstock economics with clear product differentiation and strong customer-specific application support.
Future Trends and Strategic Implications
Trend Toward Feedstock Diversification and Regional Advantage
Over the next three to five years, feedstock strategy will become an increasingly visible competitive factor. While corn cob remains dominant, the faster growth projected for sugarcane bagasse indicates that regional biomass abundance will matter more as producers seek cost resilience and supply stability. This trend creates opportunities for operations located near sugar-producing or residue-rich agricultural zones, especially where integration with existing mills or processing facilities can lower handling and conversion costs. At the same time, it raises the importance of logistics, seasonality planning, and feedstock flexibility. Companies that treat feedstock strategy as a core competitive lever rather than an operational detail will be better equipped to sustain margins through agricultural and market cycles.
Expansion of High-Purity and Specialty Grade Applications
A second trend is the gradual extension of furfural into more performance-sensitive applications. The introduction of high-purity grades for bio-polymer synthesis and advanced resin applications points to a broader shift in which bio-based inputs are expected to meet tighter specifications for color stability, consistency, and compatibility. As these grades gain traction, they can open revenue streams beyond the largest traditional applications, particularly where formulators value differentiated material properties. The commercial implication is that product development and quality assurance will become more important profit drivers, not just volume plays. Suppliers that can reliably deliver specialty grades with documented performance benefits may be able to command stronger positioning in procurement discussions and expand into higher-value customer segments.
Methylal Market
Integration of Sustainability Expectations into Procurement Decisions
A third trend is the deepening integration of sustainability considerations into industrial procurement. Even where performance remains the primary decision factor, bio-based content and supply chain transparency are increasingly part of the evaluation framework. This does not replace cost or quality as decision criteria, but it adds a layer that can influence supplier selection, especially in applications where corporate sustainability goals or customer expectations are active. The opportunity lies in aligning product communication, traceability, and application support with the way buyers now evaluate materials. The uncertainty is that sustainability preferences can vary significantly by region, industry, and procurement culture, so broad claims may be less effective than application-specific value propositions backed by consistent product quality.
Decision-Maker Playbook
For manufacturers, the priority is to connect feedstock strategy, product quality, and application focus in a way that supports both cost resilience and differentiation. Diversifying feedstock exposure where feasible, investing in grades that meet higher purity or stability expectations, and aligning product portfolios with the applications most likely to adopt bio-based inputs can improve competitive positioning. Manufacturers should also assess whether integration with existing agricultural or processing operations can reduce feedstock risk and improve economics without overextending capital or operational complexity.
For investors, the opportunity is to distinguish between volume-driven growth and value-driven growth. Capacity expansion can be attractive, but returns will depend on feedstock advantage, utilization discipline, and access to applications that reward quality and specialization. Investor scrutiny should extend beyond headline capacity figures to include feedstock mix, regional supply dynamics, product grade strategy, and the strength of downstream customer relationships. Projects that combine regional biomass access with clear differentiation in higher-value applications are more likely to deliver durable competitive advantage.
For procurement and supply chain leaders, the focus should be on evaluating suppliers not only on price but also on consistency, grade suitability, and the ability to support application-specific requirements. As higher-purity and specialty grades become more relevant, procurement decisions may need to balance conventional cost optimization with performance reliability and bio-based alignment. Building supplier partnerships that provide transparency on feedstock sources, product specifications, and quality consistency can reduce procurement risk while supporting broader sustainability objectives.
5-hydroxymethylfurfural (5-HMF) (CAS 67-47-0) Market
The furfural market is moving through a phase where growth is increasingly tied to feedstock economics, product specialization, and the way sustainability expectations are embedded into industrial procurement. Companies that treat these forces as interconnected rather than separate issues will be better prepared to capture value as the market expands toward 2032. Detailed segmentation data, regional nuance, and application-level forecasts can sharpen these decisions further, and the full research report provides that level of granularity for teams seeking a more precise basis for strategy and investment planning.
For detailed analysis of this topic, please visit the official page: Furfural Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com