

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Audio Interfaces Market: 6.08% CAGR and Strategic Shifts Reshaping 2026–2032

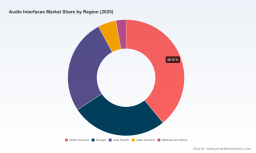
Audio Interfaces Market: Strategic Trends and Commercial Opportunities (2026–2032)
The audio interfaces market has transitioned from a peripheral accessory category to a strategic infrastructure segment within the broader professional and prosumer audio ecosystem. Over the past five years, the market has demonstrated consistent expansion, with total revenue climbing from approximately $138.0 million in 2020 to $229.95 million in 2025. The forward trajectory remains robust, with projected growth from $244.9 million in 2026 to $348.87 million by 2032, reflecting a compound annual growth rate of 6.08 percent. This expansion is not merely a function of incremental adoption; it signals a structural shift in how creators, broadcasters, educators, and enterprises capture, process, and distribute high-fidelity audio. As digital content production becomes more decentralized and quality expectations rise, audio interfaces have emerged as critical nodes in the signal chain, influencing everything from latency performance to workflow integration and downstream monetization.
Despite the favorable growth profile, the market is navigating a set of structural inflection points that demand strategic recalibration. First, the interface between hardware performance and software ecosystem compatibility has become a decisive purchasing criterion. Buyers increasingly evaluate latency consistency, driver stability, and integration with digital audio workstations, cloud collaboration platforms, and hardware DSP architectures rather than isolating analog-to-digital converter specifications in isolation. Second, pricing pressure from component inflation and logistics volatility is compressing margins for mid-tier manufacturers, forcing a sharper focus on portfolio segmentation, bundled software value, and lifecycle support models. Third, the competitive landscape is maturing into a differentiated arena where engineering pedigree, connectivity standards, and channel-count flexibility define premium positioning, while cost-efficient, feature-focused designs target the expanding home and project-studio segments. These dynamics create both friction and opportunity, rewarding companies that can balance technical credibility with ecosystem breadth and cost discipline.
Key Drivers of Market Expansion
Technological Innovation and Real-Time Processing Architecture
The market’s momentum is heavily influenced by advances in converter design, clocking precision, and low-latency connectivity pathways. Recent product iterations from leading manufacturers demonstrate a clear emphasis on high dynamic range preamplification, transparent signal paths, and integrated digital processing options that reduce reliance on external outboard gear. For example, the release of the Digiface AES 14x16 USB interface in February 2026 highlights how bus-powered designs with extensive digital I/O are becoming central to multi-channel studio configurations where rack space, power delivery, and signal routing efficiency matter as much as raw fidelity. At the same time, updates to popular USB-based studio lines now emphasize preamp clarity and enhanced dynamic range, indicating that even entry-to-mid-tier devices are being engineered to a higher performance baseline to remain competitive.
Beyond hardware improvements, the convergence of interface design with software ecosystems is reshaping value creation. Manufacturers that embed native plugin integration, console-grade routing paradigms, and high-resolution conversion architectures are extending the functional role of the interface from simple signal conversion to an integrated hub for mixing, monitoring, and processing. This trend is particularly visible in professional Thunderbolt-oriented lines that combine fast connectivity with high-resolution converters, enabling studios to maintain tighter control over signal integrity while leveraging host-based or hardware DSP workflows. The practical implication is that technological leadership is increasingly defined by integration rather than isolated specifications.
Regulatory and Geopolitical Pressures on Component Sourcing
Regulatory dynamics are exerting meaningful influence on product economics and supply continuity. Trade restrictions affecting semiconductor components, including those used in digital-to-analog and analog-to-digital conversion and digital signal processing, have introduced upward pressure on sourcing costs for key electronic parts. These constraints ripple through the value chain, affecting bill-of-materials planning and forcing manufacturers to make earlier design decisions around component substitution, alternate sourcing, and buffer inventory strategies. The impact is not uniform across the market; premium and high-throughput designs with specialized chip requirements are more exposed to supply contention than standardized connectivity-led products.
Sustainability regulation is also becoming a design constraint rather than a marketing consideration. Regulatory frameworks aligned with environmental and circular-economy objectives are pushing manufacturers toward eco-friendly design practices and recyclable material usage, particularly in chassis construction, packaging, and internal component lifecycle planning. In parallel, export controls and rare earth export restrictions have broadened the scope of supply risk by affecting materials and memory-related components that intersect with electronics production. For audio interface producers, the operational message is clear: long-term competitiveness will depend on navigating procurement diversification, compliance readiness, and product architecture choices that reduce exposure to concentrated sourcing pathways.
Demand-Side Shifts in Content Production and Professional Workflows
The demand picture is being reshaped by the expansion of professional content creation beyond traditional studio environments. Remote collaboration, location-based recording, live streaming, serialized podcast production, and hybrid event broadcasting have increased the need for interfaces that combine portability, channel density, and robust connectivity. Professional-grade applications continue to anchor a significant share of revenue, but the broader application landscape is growing as project studios, educational institutions, and enterprise media teams standardize on equipment that supports repeatable, high-quality capture workflows. This demand broadening is not simply about volume; it is about workflow flexibility, where multi-channel I/O, digital expansion options, and class-compliant operation can determine whether a device fits into a given production environment.
At the same time, end-user expectations are maturing. Buyers are less willing to accept trade-offs in preamp transparency, driver stability, or expandability when those limitations disrupt a production pipeline. This has accelerated interest in interfaces that offer console-grade input characteristics, structured insert paths, and high channel counts, especially in environments where multiple sources must be captured simultaneously without compromising signal quality. The commercial result is a market in which product credibility is increasingly tied to real-world workflow reliability rather than spec-sheet visibility alone.
Supply Chain and Cost Structure Dynamics
Component price volatility across integrated circuits, metal chassis materials, and logistics channels is reshaping cost structures for original equipment production. This pressure is especially relevant for manufacturers balancing premium feature sets with competitive pricing. In practice, companies are responding by rethinking product architecture: consolidating features into higher-value tiers, refining SKU breadth to manage inventory risk, and aligning product roadmaps with connectivity trends that reduce reliance on cost-sensitive legacy pathways. These adjustments are not purely defensive; they influence product positioning, time-to-market strategy, and the ability to sustain margin health through cycles of input-cost variation. The market is gradually moving toward designs that optimize for both performance and manufacturability, with supply chain resilience becoming a strategic differentiator rather than an operational afterthought.
Competitive Landscape and Leading Strategies
Differentiation Through Engineering Heritage and Ecosystem Alignment
The competitive field is defined by manufacturers that have anchored their positions in distinct value propositions. Focusrite has built a strong commercial presence through widely adopted USB-based studio lines, most notably the Scarlett series with fourth-generation updates that emphasize high dynamic range preamps and Clarity+ options for professional recording. This strategy blends accessibility with a recognizable performance baseline, making the portfolio a frequent reference point in education, project studios, and entry-level professional setups. Universal Audio has pursued a more DSP-centric model by pairing Thunderbolt interfaces such as the Apollo X | Gen 2 series with integrated UAD plugin workflows and high-resolution converters, effectively positioning the interface as part of a broader processing environment for professional studios.
RME has carved out a reputation for reliability and channel flexibility, with Fireface and Digiface USB lines including the AES model that supports high channel counts and class-compliant operation. This positioning appeals to facilities and advanced users who prioritize stable drivers, extensive digital expansion, and predictable performance under demanding routing conditions. Audient has focused on console-grade preamp character through its iD series, with the iD48 interface reflecting an emphasis on eight console preamps and DB25 inserts for professional recording, reinforcing a heritage-driven value proposition centered on analog quality and structured signal handling. PreSonus, through its Quantum and Studio series, has targeted multi-channel recording use cases with Thunderbolt support and high channel counts, while Solid State Logic has extended its console lineage into rackmount interfaces such as the SSL 18, which brings advanced preamp technology and eight console-grade mic/line inputs into a format designed for professional signal management.
Additional specialist players contribute to the market’s breadth. Apogee Electronics has maintained a presence in high-end FireWire and Thunderbolt interfaces, with Crystal preset technology associated with superior audio quality in demanding recording contexts. MOTU has offered flexible high input/output configurations through the 8pre and UltraLite series with Thunderbolt connectivity, while Antelope Audio’s Orion and Verge series combine ADAT and Thunderbolt pathways for professional multi-channel applications. TASCAM continues to broaden its professional audio interface footprint with models like the Model 24, which emphasize robust connectivity options and practical studio integration. Collectively, these companies illustrate a market where differentiation is achieved through a combination of connectivity architecture, preamp and converter philosophy, channel scalability, and software ecosystem alignment.
Strategic Positioning and Evolution of the Market Structure
The market concentration pattern suggests a moderately fragmented landscape, with a concentrated upper tier and a broad long tail of specialized and regional participants. A leading group of manufacturers accounts for a meaningful share of revenue, but the remaining share is distributed across brands with distinct audience segments, feature emphases, and geographic reach. This structure is evolving through two complementary forces. On one side, consolidation and partnership activity are likely to increase as larger players expand portfolios, acquire capabilities in DSP integration, or strengthen distribution and software ecosystems. On the other side, differentiation remains viable because audio interface adoption spans diverse environments, from mobile recording and broadcast to multi-room facilities and hybrid enterprise media operations.
Worldwide Sound Cards Market
New entrants and expanding incumbents are increasingly competing on workflow completeness rather than hardware alone. Interfaces that offer stable drivers, predictable latency, digital expansion compatibility, and strong integration with popular production software are gaining traction because they reduce friction across the entire recording and post-production pipeline. Meanwhile, premium manufacturers are reinforcing their advantage through converter transparency, preamp character, and high channel-count flexibility, while value-oriented players continue to address the growing home and project-studio base with streamlined feature sets and accessible pricing. The net effect is a market that is both consolidating at the top and remaining functionally segmented by use case and budget.
PW Consulting
Forward Outlook: Three Signals to Watch (2026–2032)
Connectivity and Ecosystem-Centric Interfaces Will Define Premium Demand
Over the next several years, interfaces that combine high-throughput connectivity, stable driver behavior, and meaningful software integration are likely to capture disproportionate attention in professional and advanced prosumer settings. USB and Thunderbolt pathways will continue to dominate based on current demand patterns, but the strategic battleground will be how effectively an interface fits into broader production workflows, including DSP offload, plugin ecosystems, digital expansion, and multi-location collaboration. Commercial opportunity lies in building product lines that are not only technically competent but also interoperable with the software and operational conventions that shape real-world usage. The risk is that features become decoupled from actual workflow needs, resulting in specifications that do not translate into adoption or customer retention.
Sustainability, Supply Diversification, and Component Strategy Will Become Competitive Advantages
Regulatory alignment and sourcing resilience are moving from compliance concerns to strategic assets. Manufacturers that proactively manage eco-friendly design requirements, recyclable materials, and component-diversification strategies will be better positioned to sustain product rollouts and margin stability. This is particularly important given ongoing exposure to semiconductor-related trade constraints, rare earth export controls affecting additional elements, and volatility in integrated circuits and logistics costs. The upside is that companies with disciplined sourcing and design-for-manufacturing approaches can improve predictability and reduce launch risk. The uncertainty is that regulatory and geopolitical conditions can shift quickly, making multi-region sourcing and component substitution strategies essential rather than optional.
Channel Density, Expandability, and Workflow Reliability Will Shape the Next Wave of Adoption
As professional and hybrid content production becomes more distributed, demand for interfaces that support simultaneous multi-source capture and clean signal routing will continue to rise. Products that offer scalable channel counts, digital I/O flexibility, and robust insertion and monitoring architectures are likely to see sustained interest among studios, broadcasters, and enterprise content teams. At the same time, the home studio segment will keep expanding, creating a dual-track market in which premium multi-channel solutions and accessible entry designs both have viable commercial paths. The opportunity is in clearly mapping product tiers to distinct workflow requirements so that pricing, feature sets, and support models align with user expectations. The risk is fragmentation without focus, where broad SKU lists dilute engineering attention and complicate supply management.
Actionable Guidance for Decision-Makers
For manufacturers, the strategic priority is to balance engineering credibility with ecosystem integration and supply resilience. Product roadmaps should account for connectivity pathways that reflect actual workflow demand, while also ensuring that preamp and converter quality, driver stability, and digital expansion options support long-term user retention. Equally important is designing for manufacturability and sourcing flexibility, especially where semiconductor constraints and component price volatility can affect cost structures. A disciplined approach to SKU breadth and tiered feature sets can help protect margins while preserving pathways to both premium and volume-oriented segments.
For investors, the market offers a plausible growth trajectory, but value creation will depend on company-level execution rather than category momentum alone. Assessment should focus on differentiation durability, software and DSP integration potential, distribution strength, and exposure to component and regulatory risk. Companies that can demonstrate consistent product cadence, meaningful ecosystem alignment, and proactive supply strategy are better positioned to convert market growth into sustained revenue and margin stability. Due diligence should also consider the ability to navigate regulatory shifts tied to environmental requirements and semiconductor-related trade constraints, since these factors increasingly influence production economics.
For procurement and strategic buyers, the evaluation framework should extend beyond headline specifications to include workflow compatibility, driver reliability, expandability, and long-term support. In professional environments, total cost of ownership is shaped not only by purchase price but also by integration effort, channel scalability, and the likelihood of future expansion. Given ongoing volatility in sourcing and regulatory conditions, it is advisable to verify supply continuity commitments, component strategies, and lifecycle support where possible. More detailed segmentation data, regional dynamics, and company-specific assessments can further inform purchasing and planning decisions, and may be accessed through the full PW Consulting research report for those seeking deeper granularity and tailored recommendations.
Worldwide Music Production Equipment Market
For detailed analysis of this topic, please visit the official page: Audio Interfaces Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com