

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Why 4% CAGR Matters: The Marine Trenchers Market’s 2026–2032 Shift

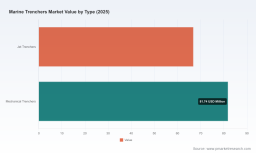
Beneath the Surface: Strategic Trends and Commercial Opportunities in the Marine Trenchers Market
The marine trenchers market has entered a phase of steady structural expansion, underpinned by growing offshore infrastructure investment and evolving technical requirements for subsea installation. Valued at approximately 120.0 million USD in 2020, the market reached an estimated 148.5 million USD by 2025, reflecting a compound annual growth rate of 4.0 percent over the 2020–2025 period. Forward projections extend through 2032, with revenue anticipated to approach 195.5 million USD by the end of the forecast horizon. While the growth trajectory appears measured in percentage terms, the underlying shift in project complexity, operational depth, and equipment specialization tells a more dynamic story. Marine trenching has moved from a supporting activity in pipeline and cable deployment to a critical capability that directly influences project economics, environmental compliance, and operational risk.
Several inflection points define the current market environment. First, the push toward deeper water projects and more complex seabed conditions is placing new demands on trenching systems, particularly around tool interchangeability, remote operation, and sediment adaptability. Second, rising project costs linked to maintenance, specialized labor, and equipment wear are forcing operators to prioritize reliability and lifecycle performance rather than upfront price comparisons. Third, the growing emphasis on offshore wind, interconnectors, and gas infrastructure is expanding the number of burial and trenching campaigns, but also compressing scheduling windows and increasing the premium on proven, repeatable execution. These dynamics are not merely operational concerns; they are reshaping procurement strategies, fleet planning, and competitive positioning across the supply chain.
Key Drivers Shaping the Market Trajectory
Technological Innovation and the Shift Toward High-Performance, Multi-Mode Systems
One of the most visible drivers in the marine trenchers market is the continued advancement of equipment capability. The industry is moving beyond single-purpose designs toward systems that can switch between mechanical cutting, jetting, and hybrid modes depending on sediment type and burial depth. This flexibility is increasingly valued because seabed conditions are rarely uniform, and project specifications often require precise depth control, minimal surface disturbance, and adaptable tool configurations. Higher horsepower platforms, improved hydraulic and electro-hydraulic architectures, and more robust cutting chains and bits are enabling operators to maintain productivity in harder sediments where wear rates and ground speed have historically limited performance.
Recent equipment milestones illustrate this direction. In October 2025, Osbit Ltd secured a contract with NKT to design and build the T3600 subsea trencher, described as one of the most powerful systems in the segment with 3,600 horsepower and dual jetting and cutting tools. The concept reflects a broader preference for machines that can handle heavier workloads while reducing the need for multiple vessel-based interventions. By February 2026, the T3600 had arrived at the Port of Blyth for final fit-out and commissioning ahead of operational use in 2027. This kind of development signals an industry leaning toward higher-capacity platforms that can address longer burial campaigns, more demanding ground conditions, and tighter project schedules.
For decision-makers, the implication is clear: equipment selection is becoming less about whether a trencher can complete a burial task and more about how effectively it can do so across variable conditions, with lower downtime and fewer operational compromises. Manufacturers that can demonstrate measurable improvements in tool life, ground speed stability, and mode switching are better positioned to capture perceived value, even when capital or rental costs are higher.
Policy, Regulation, and the Spreading Footprint of Offshore Infrastructure
Regulatory and policy environments are exerting a quiet but persistent influence on trenching demand. Environmental standards, seabed protection requirements, and cable and pipeline burial specifications are increasingly factored into project design, which in turn raises the baseline expectation for trenching quality and consistency. In many regions, burial is no longer treated as a discretionary step; it is a core requirement for protection against fishing activity, anchor damage, and environmental disturbance.
Broader energy and infrastructure trends reinforce this direction. European offshore wind capacity reached approximately 25 GW by 2020, and the continued expansion of wind farms and interconnector networks has sustained demand for cable burial equipment and related trenching standards. At the same time, Europe imported 85 billion cubic meters of LNG in 2020, helping accelerate demand for subsea pipeline burial and associated marine trenching in the region. These figures are not just energy statistics; they represent the kind of large-scale infrastructure activity that creates recurring requirements for burial, rehabilitation, and intervention services.
The policy-driven opportunity is twofold. Projects are increasingly spread across multiple geographies and seabed environments, which broadens the addressable market for trenching equipment and services. At the same time, regulatory expectations can raise the bar for execution, favoring operators with documented quality control, traceability, and compliance capabilities. Procurement teams are likely to weigh not only schedule and cost, but also the ability to meet region-specific burial standards and environmental safeguards.
Demand-Side Changes: More Burial Work, More Complexity, More Coordination
Demand for marine trenchers is being shaped by a shift in how offshore projects are planned and executed. Cable and pipeline installations are no longer isolated activities; they are integrated into wider grid, gas, and industrial networks that require coordinated scheduling across multiple contractors and vessels. As a result, trenching work is often planned around limited weather windows, restricted seabed access, and tight connection milestones. This places a premium on equipment availability, predictable performance, and rapid mobilization.
Pipeline burial remains the largest application area in terms of revenue contribution, reflecting the continued importance of protected subsea transport infrastructure. Cable burial is also significant, driven by interconnectors, wind farm export and array cables, and telecommunications links. Umbilical burial represents a smaller but technically demanding segment, often involving more delicate handling requirements and specialized burial approaches. The practical takeaway is that demand is diversified across infrastructure types, but the common thread is a need for burial solutions that can be deployed reliably across different project phases and seabed conditions.
For buyers and operators, this means that trenching capability is being evaluated within a broader project ecosystem. Equipment that can be integrated easily with different vessel configurations, ROV support, and survey and monitoring workflows is more attractive than a standalone machine optimized for a narrow set of conditions. The market is rewarding flexibility and service integration as much as raw trenching power.
Cost Structure and Operational Pressures: Wear, Labor, and Maintenance
Cost dynamics remain a significant driver of purchasing and operating behavior. Subsea trenching operations face elevated costs when sediment conditions accelerate chain and bit wear, especially in harder ground where achievable ground speeds and component life must be carefully managed. Performance monitoring against established geotechnical reference frameworks has become a practical necessity rather than an academic exercise, because underestimated wear or overly optimistic speed assumptions can materially affect project budgets and schedules.
Labor and maintenance costs add another layer of pressure. Specialized subsea trenching maintenance and operator training contribute meaningfully to overall project expenses, particularly for offshore infrastructure campaigns that require sustained operational readiness. High skill requirements, limited pools of experienced personnel, and the cost of keeping complex systems in field-ready condition all feed into total cost of ownership. This is an important shift from a purely equipment-purchase mindset to a broader operating-cost perspective.
Worldwide Underwater Dredging Robot Market
Recent project activity highlights how these cost and performance considerations play out in practice. In April 2025, Van Oord added a new Jet-It subsea trencher to its cable burial fleet following successful North Sea testing, reinforcing the value of proven shallow-water cable burial capability. In January 2025, DeepOcean completed a subsea trenching project in the US Gulf of Mexico using a 2,800hp trencher for cable and pipeline burial, demonstrating the continued relevance of powerful mechanical and jetting systems in active offshore regions. These deployments show that performance validation in real seabed conditions is a decisive factor in fleet expansion and project award decisions.
PW Consulting
Competitive Landscape and Leading Strategies
The marine trenchers market is characterized by a concentrated but diverse set of participants. Market concentration is notable, with the top three companies accounting for roughly 62.0 percent of revenue and the top five firms holding about 78.0 percent. This level of concentration suggests that scale, technological reputation, and established project relationships matter significantly, while still leaving room for specialized players and regional specialists to compete on differentiated capabilities.
Several companies illustrate the range of strategic positions in the market. Soil Machine Dynamics Ltd, based in Wallsend, Tyne & Wear, United Kingdom, manufactures subsea trenchers, burial machines, and related intervention equipment for pipeline and cable laying, including the Q-Trencher and Shallow Water Trencher models. Royal IHC, headquartered in Kinderdijk, Netherlands, designs and manufactures the Hi-Traq® multi-tool subsea trenchers, jetters, and tracked trenching vehicles for shallow water cable burial and offshore wind projects. Seatools B.V., based in the Netherlands, specializes in custom subsea trenching vehicles, mechanical and jet trenchers, cable ploughs, and upgrades for pipeline and cable installations. Osbit Ltd, also in the United Kingdom, designs, builds, and upgrades subsea trenching systems including mechanical, jetting, and cutter trenchers for cable and pipeline burial. Mastenbroek Limited, another UK-based manufacturer, provides subsea trenchers with conventional or undercut/rotary heads, available in hydrostatic or electro-hydraulic configurations for various sediment types.
The competitive field also includes operators and integrated service providers that use or deploy trenching equipment as part of broader campaign execution. Allseas Group, based in the Netherlands, operates Digging Donald, a fully remote-controlled pipeline burial trencher capable of depths up to 450 meters with interchangeable tools. DeepOcean Group, headquartered in the United Kingdom, operates a fleet and provides marine trenching equipment including mechanical trenchers, jetting ROVs, and ploughs for pipeline, cable, and umbilical burial. Van Oord, also in the Netherlands, operates and manufactures its own fleet of trenchers including Deep Dig-It, Dig-It, and Jet-It for subsea cable burial up to more than 5 meters below the seabed.
Differentiation Through Capability, Flexibility, and Execution track Record
What distinguishes the stronger positions is not simply equipment ownership, but the ability to match trenching technology to project needs and to prove performance in the field. Some manufacturers compete on power and tool versatility, emphasizing high horsepower and dual-mode systems that can adapt to harder or mixed sediments. Others compete on specialization, focusing on shallow water cable burial, tracked vehicles, or custom trenching vehicles that can be tailored to specific seabed and water-depth constraints. A third group differentiates through remote operation, depth capability, and tool interchangeability, which matters when projects require precise burial at greater depths or when surface vessel exposure must be minimized.
Recent developments show how these strategies are being reinforced. The T3600 contract award to Osbit and its subsequent arrival for fit-out point to a push toward higher-power, multi-tool systems that can serve demanding pipeline and cable projects. Van Oord's addition of a new Jet-It trencher after North Sea testing reflects a practical emphasis on validated cable burial performance in a region with active wind and interconnector work. DeepOcean's Gulf of Mexico project completion demonstrates the value of proven fleet deployment in geographically diverse markets.
Market Evolution: Consolidation, Specialization, and Selective New Entry
The market is likely to continue evolving around three themes. First, consolidation may remain attractive for firms seeking to broaden geographic reach, capture more of the project lifecycle, or combine equipment manufacturing with service delivery. Second, specialization will persist because seabed conditions, water depths, and project types are too varied for a single equipment architecture to dominate all segments. Shallow water cable burial, deep pipeline burial, umbilical handling, and mixed-sediment trenching each reward different design priorities. Third, new entry and expansion will depend on credible technical differentiation and demonstrated execution, rather than brand presence alone. In a market where top suppliers already hold a substantial share, credibility is built through project record, performance data, and the ability to integrate with operator and client workflows.
For strategic planners, the competitive takeaway is that procurement is increasingly comparative and evidence-based. Vendors that can articulate measurable differences in wear performance, operating efficiency, and deployment flexibility are better placed to defend pricing and win repeat work. For investors and industry participants, the more interesting question is not whether the market will grow, but which capabilities will be rewarded as project conditions become more varied and cost scrutiny intensifies.
Future Trends to Watch Over the Next 3 to 5 Years
Trend 1: Higher-Capacity, Multi-Mode Trenching as a Baseline Expectation
Over the next few years, the threshold for competitive trenching capability is likely to rise. Projects in harder sediments, deeper water, and more constrained schedules will push operators toward higher horsepower platforms with interchangeable tools and multiple burial modes. The recent emphasis on powerful dual-function systems is not an isolated product trend; it reflects a broader expectation that trenching equipment should reduce the need for rework, handle variable ground conditions, and keep campaigns on schedule.
The commercial opportunity here lies in equipment and service packages that lower total operating risk rather than simply increase peak power. Manufacturers and fleet providers that pair high-capacity machines with proven tool management, maintenance planning, and operational support may find stronger demand than those competing on hardware specifications alone. The risk is that power upgrades can raise capital and maintenance costs, so any advantage must be translated into measurable gains in productivity, component life, or schedule reliability.
Trend 2: Greater Integration of Remote Operation, Monitoring, and Fleet Standardization
Remote-controlled and remotely supervised trenching is likely to become more prominent as projects seek to improve precision, reduce vessel exposure, and standardize execution across multiple sites. The growth of fully remote pipeline burial systems and ROV-supported jetting and mechanical trenchers indicates a market moving toward operational models that depend less on manual intervention and more on controlled, repeatable processes. At the same time, operators managing multiple vessels and campaigns will increasingly value fleet standardization, common maintenance regimes, and shared training pathways.
Marine Deck Machinery Market
This trend creates opportunities for companies that can offer not just equipment, but consistent operating interfaces, training support, and lifecycle management. For buyers, standardized fleets and remote operation can simplify crew deployment and reduce variability between projects. The uncertainty is operational maturity: remote and semi-remote systems require dependable communications, maintenance readiness, and skilled oversight, so the benefits will depend on how well they are integrated into real-world campaign planning.
Trend 3: Regional Demand Diversification with Uneven Pace
Demand for marine trenching is expected to remain geographically diverse, supported by offshore wind, interconnectors, pipeline and cable networks, and energy infrastructure expansion in multiple regions. However, the pace of growth is unlikely to be uniform. Some markets will see sustained activity driven by large-scale wind and grid investments, while others may experience more intermittent demand tied to specific pipeline or LNG-related projects. This uneven pattern means that fleet planning and regional positioning will matter more than broad but shallow market exposure.
The associated opportunity is to align equipment portfolios and service coverage with the regions and project types most likely to generate recurring work. Companies that understand local seabed conditions, regulatory expectations, and project scheduling realities will be better positioned to capture demand without overextending into less predictable segments. The main risk is overgeneralizing from one region's pipeline or wind activity to the entire market; seabed conditions, permitting environments, and vessel logistics vary enough to make regional nuance a strategic necessity.
Strategic Recommendations for Decision-Makers
For manufacturers and equipment developers, the priority should be to translate technical differentiation into commercial clarity. Higher power, multi-mode tools, and remote operation features are attractive, but their value increases when they are linked to measurable outcomes such as reduced rework, longer component life in challenging sediments, and faster mobilization. Investment in demonstration projects, peer-reviewed performance data, and lifecycle support can be as important as the hardware itself. Companies should also consider how their offerings fit into broader project ecosystems, including compatibility with different vessel types, ROV support, and survey workflows.
For investors and strategic partners, the most defensible opportunities are likely to be found where market concentration, technical lead times, and execution track record intersect. A concentrated market can create durable positions for firms with proven capability, but it also means that competitive advantage must be continually renewed through product evolution and reliable project delivery. Capital allocation decisions should account for the reality that trenching demand is tied to large infrastructure cycles, which can be strong but unevenly timed. Preference for operators and manufacturers with diversified project exposure, disciplined cost structures, and credible maintenance and training capabilities may offer a more balanced risk profile than pure capacity expansion.
For procurement teams and project developers, equipment selection should be evaluated against total project risk rather than headline performance alone. Burial depth requirements, sediment variability, maintenance readiness, training burden, and regional support availability all influence long-term outcomes. Where possible, validation through recent deployments in comparable conditions can provide more useful guidance than specification comparisons in isolation. Buyers may also benefit from considering fleet compatibility and service integration, especially when multiple projects or regions are involved, because standardization can reduce training costs and improve scheduling predictability.
Across all perspectives, the most valuable intelligence is the kind that connects equipment capability to real operational conditions and project economics. Market size and growth rates provide context, but the decisions that matter most are usually about which trenching approach fits a given seabed profile, which fleet configuration best supports regional demand, and which performance trade-offs are acceptable when wear, labor, and maintenance costs are factored in. Detailed segmentation data, company-level positioning, and region-specific demand analysis can make those choices sharper and less reliant on assumption.
Closing Perspective
The marine trenchers market is expanding at a steady pace, but its strategic significance is growing faster than the headline numbers suggest. Burial and trenching are increasingly integral to the safe, compliant, and cost-effective deployment of offshore pipelines, cables, and umbilicals. That shift rewards systems that combine power, flexibility, remote operability, and proven field performance, while also rewarding operators and manufacturers that can manage the practical realities of wear, specialized labor, and project scheduling. The next several years will likely favor participants who treat trenching capability as part of an integrated infrastructure solution rather than as a standalone tool purchase. For executives, investors, and procurement leaders, the most useful next step is to align equipment and service choices with the specific seabed conditions, regional demand patterns, and cost structures that will shape each project's outcome.
For detailed analysis of this topic, please visit the official page: Marine Trenchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com