

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ballast Water Treatment Equipment Market: Why 8.7% CAGR Changes Everything

The Ballast Water Treatment Equipment Market: Navigating the Next Wave of Maritime Compliance and Capital Opportunities
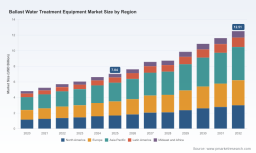
The global fleet is undergoing a quiet but profound transformation. As environmental regulations tighten and port state inspections become more rigorous, ballast water treatment has shifted from a compliance checkbox to a strategic operational priority. The market has expanded at a steady pace, with revenues crossing the seven-billion-dollar threshold in 2025 and projected to surpass ten billion before 2030, maintaining a compound annual growth rate of 8.72 percent through 2032. This trajectory reflects more than incremental fleet upgrades; it signals a structural realignment in how shipowners, regulators, and technology providers approach ballast water management as a long-term operational and sustainability imperative.
Growth is broad-based, spanning mature and emerging maritime regions, with Asia Pacific representing the largest share of activity, followed by Europe and North America. While the regional distribution reflects differing fleet compositions and regulatory timelines, the underlying momentum is universal: older vessels are being retrofitted, newbuilds are specifying treatment systems at the design stage, and operators are seeking equipment that balances performance with minimal downtime. Against this backdrop, the market is no longer defined solely by regulatory compliance deadlines. It is increasingly shaped by technology maturity, cost-of-ownership dynamics, and the growing emphasis on electronic record-keeping and verifiable treatment performance under intensifying inspection regimes.
Market Landscape and Core Challenges
The current phase of the ballast water treatment equipment market is characterized by a maturing technology base, heightened enforcement activity, and a competitive environment that favors players capable of demonstrating reliable performance across diverse water conditions and vessel types. Revenue growth has been consistent, supported by a pipeline of retrofit projects and newbuild specifications. Yet beneath the headline figures lie structural tensions that will determine which companies and investors capture durable value.
1. Treatment Performance Under Real-World Variability
Ballast water systems must handle wide fluctuations in salinity, temperature, turbidity, and biological load. This variability continues to challenge system reliability, particularly for technologies sensitive to water quality or requiring precise chemical dosing. Operators are increasingly scrutinizing performance data, service histories, and the ease of maintenance when selecting equipment. The implication is clear: systems that can demonstrate consistent efficacy with simpler maintenance profiles, and that integrate cleanly into existing vessel operations, are gaining preference over solutions that demand frequent calibration or extensive crew intervention.
2. Regulatory Tightening and Inspection Pressure
The regulatory environment is moving from baseline compliance toward verifiable, auditable performance. Recent amendments to the Ballast Water Management Convention have updated record-keeping requirements, including revised Ballast Water Record Book forms and the introduction of electronic records, reinforcing the expectation that operators maintain detailed, accessible documentation. Concurrently, port state control concentrated inspection campaigns have targeted ballast water management during specific windows, employing structured questionnaires and on-site verification to assess system compliance. These developments elevate the importance of systems that not only meet technical standards but also facilitate transparent reporting and straightforward audits.
3. Capital Allocation and Retrofit Economics
Shipowners face competing capital priorities, particularly in an environment where dry-dock schedules, compliance upgrades, and operational efficiency investments all compete for limited budgets. Retrofitting ballast water treatment equipment requires careful planning around vessel downtime, installation complexity, and integration with existing piping and control systems. For fleet operators, the decision often hinges on total cost of ownership rather than upfront price alone, including energy consumption, consumables, service availability, and the potential for future regulatory changes. This dynamic is reshaping procurement behavior toward solutions that offer predictable operating costs and adaptable configurations.
Key Drivers Redefining Market Dynamics
Several interconnected forces are accelerating growth and reshaping competitive priorities in the ballast water treatment equipment market. Understanding these drivers is essential for identifying where demand is heading and which capabilities will differentiate successful participants.
Technology Innovation and Treatment Modality Evolution
The technology landscape reflects a shift toward hybrid and multi-barrier approaches that combine filtration with disinfection methods such as ultraviolet treatment, electrolysis, and chlorine-based disinfection. Filtration-plus-UV configurations are widely recognized for their chemical-free operation and suitability across many vessel types, while electrolysis-based systems offer compact footprints and strong disinfection performance. Chlorination-focused solutions provide effective treatment in certain operating conditions but require careful handling and monitoring. The practical trend is toward systems that can adapt to varying ballast water quality, minimize consumables dependency, and integrate smoothly with vessel automation and data systems. This is not merely a technical preference; it reflects operational priorities around crew workload, maintenance intervals, and regulatory verifiability.
Policy and Regulatory Momentum
Policy remains the foundational demand driver, but its influence is deepening beyond initial compliance. The ongoing review of the ballast water management framework, informed by accumulated data and operational experience, points to potential amendments that could further refine performance requirements and measurement approaches. For manufacturers and shipowners alike, this means designing for future-proofing. Systems that are modular, upgradable, and capable of producing auditable electronic records will be better positioned as the regulatory framework evolves. The emphasis on documentation and verification also raises the strategic importance of service and support, since compliance is increasingly judged by both equipment performance and the quality of operational records.
Demand-Side Shifts in Fleet Strategy
Shipowners and operators are recalibrating fleet strategy in response to energy efficiency goals, operational resilience, and reputational considerations. Ballast water treatment is now part of a broader conversation about vessel sustainability and operational risk management. Newbuild orders increasingly include treatment specifications as standard, while retrofit activity is being prioritized for vessels with longer remaining service lives. This demand-side shift favors solutions that can be installed with minimal disruption, integrated with existing bridge and automation systems, and supported by local service networks. In addition, operators are increasingly factoring in the ease of proving compliance during inspections, which makes system transparency and documentation support a material purchasing consideration.
Supply Chain and Cost Structure Pressures
Cost structures in the equipment and services space are being re-evaluated as operators seek to manage total expenditure over the lifecycle of the vessel. While initial pricing remains relevant, buyers are paying greater attention to energy use, filter replacement cycles, chemical handling where applicable, and the availability of service and spare parts across key operating regions. This has encouraged a broader view of value, with some operators favoring solutions that reduce recurring consumable costs or that offer service agreements aligned with planned maintenance schedules. At the same time, supply chain resilience matters, particularly for components that must be available across multiple regions and vessel types. Providers that can combine reliable hardware with predictable service delivery are increasingly differentiated.
Competitive Positioning and Strategic Differentiation
The competitive landscape is moderately concentrated, with a handful of leading firms accounting for a significant share of activity. This concentration reflects the credibility requirements of the market: shipowners prefer suppliers with established certification status, proven installation experience, and the ability to support vessels across regions. At the same time, the diversity of treatment technologies and vessel requirements leaves room for specialized offerings and regional strengths.
Technology Archetypes and Differentiators
Leading participants are building distinct identities around treatment architecture, service capability, and integration depth. Alfa Laval, for example, has focused on filtration-plus-UV systems with an emphasis on compact design and compatibility with a range of vessel types, positioning its PureBallast product line around operational simplicity and performance consistency. Techcross has emphasized electrochemical approaches through direct and indirect electrolysis systems, catering to operators seeking robust disinfection performance and a footprint suited to certain vessel configurations. Hyde Marine’s Guardian series combines filtration and UV treatment with a focus on reliability and installation flexibility. Optimarin offers filtration-plus-UV systems with a strong service orientation, while De Nora Marine and Evoqua Water Technologies are associated with filtration-plus-electrolysis architectures that appeal to operators prioritizing disinfection performance and compact layouts. Wärtsilä presents both UV and electrochemical options, leveraging broad marine system integration capabilities. Norwegian Greentech, Trojan Marinex, and Ecochlor round out a field that includes filtration-plus-UV and filtration-plus-chlorine disinfection approaches, each with distinct operating trade-offs.
The strategic implication is that no single technology archetype dominates across all segments. Instead, differentiation is emerging around the fit between treatment method and vessel profile, the quality of documentation and inspection readiness, and the reliability of regional service support. Companies that can articulate clear performance cases, provide robust training and maintenance pathways, and align their offerings with electronic record-keeping expectations are likely to strengthen their position as scrutiny intensifies.
Concentration, Consolidation, and Market Evolution
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. Larger players with integrated marine system portfolios can leverage cross-selling, service networks, and engineering partnerships to deepen their footprint. At the same time, specialized manufacturers and regional service providers can compete by offering niche performance advantages, faster installation, or customized support for specific vessel types. Recent certification updates from classification bodies have reaffirmed approvals for a broad set of manufacturers, underscoring that the market remains open to multiple qualified participants. This environment favors companies that can demonstrate not only technical compliance but also the operational credibility to withstand inspection campaigns and evolving record-keeping expectations.
A further evolution likely to shape the competitive landscape is the increasing importance of digital readiness. Systems that produce clean, auditable data trails and interface with vessel reporting processes are better positioned for the inspection environment and the broader movement toward electronic records. This is not only a compliance consideration; it is becoming a differentiator in how operators assess risk, manage audits, and maintain documentation across fleets.
Strategic Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, several trends are likely to define the direction of the ballast water treatment equipment market and its commercial opportunities.
1. Compliance Becomes Continuous, Not Episodic
As inspection activity intensifies and electronic record-keeping becomes standard, the market will increasingly value systems that support ongoing verification rather than one-time certification. This trend favors solutions with clear documentation outputs, straightforward maintenance, and service models that help operators sustain compliance over time. For equipment providers, the opportunity lies in embedding compliance support into the product experience and service package, reducing the administrative burden on shipowners while strengthening reliability during audits.
Commercial implication: Providers that combine robust hardware with documentation-ready workflows, crew training, and localized service can create stickier relationships and reduce attrition in competitive retrofit and newbuild decisions.
2. Technology Convergence Around Practical Performance
While multiple treatment modalities will persist, the market is likely to see greater emphasis on practical performance across variable water conditions, ease of maintenance, and compatibility with vessel systems. Hybrid approaches that pair pre-treatment filtration with a disinfection method selected for the operating profile will remain central. Over the next few years, differentiation will increasingly hinge on real-world reliability, energy efficiency, and the ability to adapt configurations to specific vessel types and routes. This could encourage more modular designs and more flexible service agreements.
Commercial implication: Manufacturers that invest in field performance data, simplify maintenance, and align configurations to vessel operating patterns can strengthen their value proposition beyond compliance certification alone.
3. Regulatory Refinement Will Reshape Requirements and Planning Horizons
The ongoing review of the ballast water management framework, informed by operational data, suggests that requirements could evolve. Potential amendments may influence measurement approaches, reporting expectations, or performance verification methods. For shipowners and builders, this means adopting a forward-looking procurement stance, favoring systems that can be updated or reconfigured without major rework. For suppliers, it means designing products and service offerings with regulatory adaptability in mind.
Commercial implication: Early alignment with likely regulatory directions can reduce future retrofit risk and position companies to capture demand from operators seeking durable, adaptable solutions rather than short-term compliance fixes.
Worldwide Black Water Treatment System for Boats Market
Risks and Uncertainties to Monitor
No strategic outlook is complete without acknowledging uncertainty. The pace and content of future regulatory amendments remain dependent on international consensus and technical review processes. Inspection campaigns can vary in intensity and focus across regions, affecting short-term demand patterns. Economic conditions, vessel utilization, and capital availability will influence the timing of retrofit investments, particularly for older tonnage. In addition, technological trade-offs among treatment methods mean that performance claims must be carefully matched to specific operating conditions, and that supplier claims should be validated against real-world service data where possible.
PW Consulting
These uncertainties do not diminish the long-term trajectory; they reinforce the value of informed, scenario-aware decision-making. The operators and investors who succeed will be those who treat ballast water management not as a single compliance event but as a continuing operational capability.
Actionable Recommendations for Decision-Makers
For manufacturers, investors, and procurement teams, the current market environment calls for a balanced focus on compliance credibility, operational practicality, and lifecycle economics.
Water Treatment Equipment Market
For Equipment Manufacturers and Technology Providers
Position offerings around verifiable performance and inspection readiness, not certification alone. Invest in field performance documentation, crew training materials, and service models that reduce downtime and support electronic record-keeping. Consider modular architectures that allow configuration adjustments as requirements evolve. Strengthen regional service presence where retrofit and newbuild activity is concentrated, since responsiveness and parts availability increasingly influence purchasing decisions.
For Investors Evaluating Exposure
Assess exposure through the lens of total cost of ownership rather than unit pricing, with attention to service attach rates, consumable economics, and the breadth of certification and approval status across key regions. Differentiate between players with broad marine system integration capabilities and those with focused technology strengths. Monitor regulatory developments that could shift demand timing or favor particular treatment approaches, and weigh the resilience of service networks against the risk of regional inspection variability.
For Shipowners and Procurement Teams
Prioritize solutions that match the vessel’s operating profile, expected water quality variability, and inspection exposure, while keeping total cost of ownership at the center of evaluation. Favor systems that simplify maintenance, integrate with existing control and reporting workflows, and provide clear documentation support. Plan retrofit campaigns with dry-dock scheduling and service availability in mind, and seek configurations that can adapt to potential regulatory updates without major rework.
In all cases, the strategic value of detailed, up-to-date market intelligence is substantial. Segment-level demand patterns, regional inspection nuances, and technology-specific performance considerations can materially affect procurement timing and product selection. Access to granular data and tailored scenarios helps decision-makers move from broad trends to specific, defensible choices. PW Consulting’s in-depth research on the ballast water treatment equipment market provides that layer of detail, offering segmented analysis and customized viewpoints to support planning with greater precision.
For detailed analysis of this topic, please visit the official page: Ballast Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com