

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Wheel Flange Lubrication System Market: Why 4.46% CAGR Redefines Track Performance

Global Wheel Flange Lubrication System Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Steady Growth Anchored in Infrastructure Modernization
The global wheel flange lubrication system market has transitioned from a specialized niche to a critical component of railway maintenance ecosystems. Valued at USD 0.56 billion in 2020, the market has followed a consistent upward trajectory, reaching approximately USD 0.70 billion by 2025. Projections through 2032 indicate continued expansion, with the market expected to reach USD 0.95 billion by the end of the forecast period, supported by a compound annual growth rate of 4.46%. This trajectory reflects a maturing but still evolving landscape where reliability, environmental compliance, and lifecycle cost optimization drive procurement decisions across transport operators and infrastructure managers.
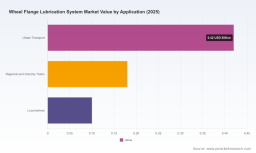
The market structure remains concentrated, with the top three and top five players collectively commanding roughly 70% of global revenue. This concentration suggests entrenched relationships with rolling stock manufacturers, railway operators, and municipal transit authorities, while simultaneously leaving meaningful room for differentiated challengers who can address specific operational pain points. Geographically, demand is distributed across multiple regions, with mature markets in North America and Europe maintaining steady procurement cycles and emerging infrastructure programs in Asia Pacific, Latin America, and the Middle East and Africa contributing incremental growth. The application mix is anchored by urban transport networks, which represent the largest share of deployments, followed by regional and intercity trains and locomotive operations. By system type, wayside configurations account for the majority of installations, while on-board solutions occupy a smaller but strategically important segment tied to fleet flexibility and space-constrained platforms.
This growth is not accidental. It reflects a broader shift in railway operations from reactive maintenance toward predictive, condition-based, and environmentally conscious asset management. The market’s trajectory through 2032 will be shaped less by raw volume expansion and more by the ability of stakeholders to align lubrication technologies with evolving compliance standards, operational reliability targets, and total cost of ownership expectations.
Critical Challenges and Industry Inflection Points
The market faces a set of intertwined challenges that are reshaping procurement behavior and technology selection. First, the operational trade-off between lubrication effectiveness and contamination risk continues to force operators to reconsider liquid versus solid delivery architectures. Recent industry publications have highlighted shunt failure issues caused by excess oil from liquid wheel flange lubrication systems in metro applications, underscoring how over-application or poorly managed dispersion can create downstream reliability problems. This has reignited operator scrutiny around dosing precision, delivery placement, and the operational footprint of lubricant residues on track infrastructure.
Second, regulatory and environmental constraints are tightening the boundaries of acceptable lubricant selection. Equipment standards such as EN 15427-1-1:2022 specify requirements for equipment used to apply lubricant to the interface between the wheel flange and the gauge face of the rail, which pushes suppliers to align hardware design, nozzle performance, and application controls with recognized engineering expectations. Beyond equipment specifications, environmental permitting and lubricant discharge limits in certain jurisdictions restrict lubricant types and affect a meaningful portion of trial sites reported by operators. These constraints are not theoretical; they influence procurement timelines, site approvals, and the willingness of operators to adopt new chemistries without localized validation.
Third, material and design choices are increasingly scrutinized through a lifecycle lens. Modern wheel flange lubrication systems are often built on a polymer matrix with dry solid lubricant integrated, a configuration that reflects the broader industry shift toward reduced residue, simplified maintenance, and lower contamination risk. However, performance consistency across varying rail profiles, weather conditions, and traffic densities remains a recurring operational challenge. Suppliers that can demonstrate repeatable friction reduction, controlled wear characteristics, and compatibility with different rail and wheel materials will have a distinct advantage in a market where operators increasingly evaluate solutions across multi-year service life rather than initial capex.
PW Consulting
These challenges do not signal stagnation. Instead, they mark an inflection point where the winning offerings will be those that balance application precision, environmental acceptability, and maintenance-friendly design rather than those that simply maximize lubricant volume or hardware complexity.
Core Drivers Shaping Market Direction
Several interconnected forces are accelerating change in wheel flange lubrication system demand and purchasing behavior.
Technological innovation is pushing the category beyond mechanical dispensing toward controlled delivery, material science advancement, and more predictable friction management. Patented application techniques and specialized material formulations are being used to improve lubrication consistency while reducing excess spread. Dry solid lubricant approaches, particularly carbon-based products designed to lower friction and wear without heavy residue, are gaining traction where operators seek to reduce cleaning cycles and minimize track contamination. At the same time, on-board and wayside architectures are being refined to address specific operating environments, from high-frequency urban tram networks to heavier regional and intercity services. The result is a more segmented technology landscape in which performance claims must be validated under real track conditions, not just in laboratory settings.
Policy and regulatory dynamics are simultaneously shaping the market by narrowing lubricant choices and increasing documentation expectations. Newer equipment requirements and evolving environmental expectations are making compliance an integral part of procurement rather than an afterthought. The growing proportion of biodegradable and low-VOC lubricant selections in new contracts signals that sustainability considerations are moving from peripheral interest to active evaluation criteria. This shift does not eliminate performance requirements, but it does raise the bar for solution providers: lubricant formulations and delivery systems must now demonstrate operational value alongside environmental acceptability.
Demand-side behavior is also changing. Urban transport authorities and regional operators are increasingly focused on service continuity, reduced wheel and rail wear, and lower maintenance burden. These priorities are especially relevant where network utilization is high and downtime carries significant operational and financial consequences. Procurement teams are therefore weighing lubrication systems not only against upfront cost, but also against expected service intervals, ease of refilling or replacement, and the ability to reduce unplanned interventions. In that context, lubrication solutions that simplify field service and deliver consistent performance can justify premium positioning even in cost-sensitive environments.
Supply chain and cost structure considerations add another layer of influence. Material availability, carbon-based feedstock characteristics, polymer matrix design, and manufacturing scalability all influence both product performance and commercial resilience. As operators become more sensitive to total cost of ownership, suppliers that can manage material sourcing, maintain formulation consistency, and support service networks with predictable lead times are better positioned to secure long-term contracts. Cost compression alone is unlikely to drive purchasing decisions in this segment; reliability, compliance, and serviceability typically carry more weight in operational evaluations.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a blend of established multinational suppliers, specialized lubrication manufacturers, and material-focused innovators. Large incumbents tend to leverage broad railway portfolios, global service reach, and longstanding relationships with rolling stock and infrastructure stakeholders. This scale advantage supports system integration, cross-platform compatibility, and the ability to offer both wayside and on-board configurations within a single supplier relationship. For operators seeking consolidation of supply and standardized maintenance practices, these players remain natural first stops in the evaluation process.
At the same time, differentiated specialists are competing through technology specificity and application expertise. Companies promoting patented delivery methods are positioning around precision, reduced waste, and performance consistency in targeted use cases. Suppliers of carbon-based dry lubricants are emphasizing friction reduction and wear mitigation with a focus on lower contamination and simplified field handling. Others are promoting solid lubricant sticks, applicators, and corrosion-resistant designs tailored for metro, tram, and industrial railway environments where residue control and durability are especially important. This specialization matters because wheel flange lubrication is inherently site-sensitive; a solution that performs well in one operating environment may require adaptation in another.
Recent developments indicate a market that is active but selective. Industry participation in technology exhibitions and targeted case study publications suggests continued emphasis on demonstration, validation, and operator education. Showcasing lubrication technologies at sector events helps suppliers reach transit authorities, maintenance teams, and engineering decision-makers who evaluate solutions based on compatibility with existing infrastructure and anticipated service impact. At the same time, published case discussions around excess oil and shunt-related issues reinforce the market’s sensitivity to over-application and contamination, pushing the conversation toward controlled delivery and cleaner interface management.
The competitive landscape is likely to evolve through a mix of consolidation and targeted entry rather than uniform convergence. Consolidation may continue where scale, service coverage, and system integration create durable advantages. Fragmentation may persist where niche performance, regional compliance needs, or specific material advantages allow focused players to win meaningful contracts. New entrants will need to demonstrate more than equipment availability; they will need to show credible validation, operator-relevant service support, and alignment with environmental and reliability expectations. For incumbents, the challenge is to avoid over-reliance on portfolio breadth alone and to maintain compelling product-level differentiation as procurement teams become more sophisticated about lifecycle performance.
Forward-Looking Trends: 2026 to 2032
Several trends are likely to define commercial direction over the next several years.
Trend 1: Controlled delivery and residue-sensitive architectures will gain preference. As operators confront the operational consequences of over-application and track contamination, demand will increasingly favor systems that emphasize dosing accuracy, targeted placement, and cleaner interface management. This trend supports both dry solid and refined liquid approaches, but only where performance can be demonstrated without creating secondary maintenance burdens. Commercial opportunity lies in solutions that reduce cleaning frequency, improve consistency across varying traffic conditions, and simplify operator procedures. The risk is that overly aggressive claims about “cleaner” systems will be challenged if field validation does not match controlled-environment expectations.
Trend 2: Environmental acceptability will become a core procurement filter, not a secondary consideration. With biodegradable and low-VOC options representing a growing share of new contract selections and environmental permitting constraints affecting a notable portion of trial activity, sustainability criteria will play a larger role in vendor shortlists. Solutions that align with local discharge expectations, demonstrate reduced environmental footprint, and maintain mechanical performance will be better positioned for broader adoption. The commercial upside is clear for suppliers that can provide compliant chemistries, application hardware, and documentation support in a single value proposition. The uncertainty lies in regulatory variation across jurisdictions, which may require region-specific validation and slow standardization of lubricant preferences.
Trend 3: Lifecycle value and service integration will increasingly outweigh initial hardware cost. Operators managing dense urban networks and publicly accountable transport systems are likely to evaluate lubrication systems through total cost of ownership, including maintenance labor, refilling logistics, wear reduction, and downtime avoidance. This creates opportunities for suppliers that bundle application reliability with field service support, predictable consumable supply, and design choices that simplify inspection and replenishment. Over the next few years, contracts may increasingly reward proven serviceability and operational consistency. The risk is that supply chain volatility, material availability, or inconsistent manufacturing quality can undermine the expected lifecycle benefits and erode buyer confidence.
Automatic Lubrication Systems Market
Strategic Implications for Decision-Makers
For manufacturers and technology suppliers, the priority is to align product development with the market’s shifting evaluation criteria. Differentiation is strongest when it directly addresses application precision, residue management, and environmental compliance without sacrificing reliable friction control. Investments in validation documentation, pilot-scale demonstrations, and region-specific lubricant compatibility can improve credibility with operators and engineering teams. Supplier strategies that depend solely on hardware presence or legacy relationships are more vulnerable to competitors offering cleaner, more controllable, and more service-friendly solutions.
For investors and strategic partners, the attractive value lies in capabilities that strengthen lifecycle value and compliance readiness rather than in volume expansion alone. Technology positions tied to controlled delivery, dry solid formulations, and durable consumable designs may offer more defensible differentiation in a market where contamination risk and environmental constraints are rising in importance. Equally important is the operational side: distribution, service readiness, and the ability to support trial-to-scale transitions can determine whether a promising product translates into durable contract wins. Due diligence should account for regional regulatory variation and the potential need for localized validation before widespread adoption.
For procurement teams and transport operators, the most effective approach is to evaluate lubrication systems through a combined lens of reliability, compliance, and maintenance burden. Specifying solutions based only on upfront price can increase exposure to repeat application issues, cleaning requirements, and downstream infrastructure concerns. Where possible, procurement should incorporate trial data, operator-relevant performance metrics, and supplier support capabilities into the decision process, especially for urban networks and high-utilization services where downtime carries significant operational cost. Balancing equipment standards alignment with lubricant selection criteria can also reduce approval friction and improve long-term contract stability.
Railway Grease Market
As the market moves toward 2032, the differentiating questions will not be limited to whether a system can apply lubricant, but whether it can do so with controlled dispersion, compliant chemistry, and maintenance-friendly execution across the intended operating environment. Organizations that secure detailed segment-level insight, region-specific regulatory context, and supplier-by-supplier positioning will be better equipped to time investments, refine specifications, and target the most commercially relevant opportunities.
For detailed analysis of this topic, please visit the official page: Wheel Flange Lubrication System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com