

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
Strategic Trends and Commercial Opportunities in the Global Casting Tip and Nozzle Market
Market Overview and Core Challenges
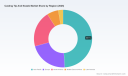
The worldwide market for casting tips and nozzles has steadily matured into a critical enabler of modern metallurgical production. Valued at approximately $336.1 million in 2025, the market has expanded from $258.4 million in 2020, reflecting a compound annual growth rate of 5.24 percent through the early stages of the current decade. Looking ahead to 2032, the trajectory points toward roughly $480.9 million, a shift that underscores sustained demand for precision flow control and thermal management components across continuous and semi-continuous casting environments. While the growth rate is moderate rather than explosive, the underlying drivers point to meaningful structural upgrades rather than cyclical expansions. Manufacturers and foundries alike are moving beyond basic replacement parts toward engineered solutions that extend campaign lengths, reduce breakout incidents, and improve strand surface integrity.
Several converging challenges are testing the industry's adaptability. First, thermal and erosion resistance remain persistent bottlenecks. Casting environments expose tips and nozzles to extreme temperature gradients, chemical interactions with molten metal, and mechanical stress during insertion and withdrawal. When components fail prematurely, campaign interruptions, metal losses, and unplanned maintenance cascade through production schedules. Second, the supply base is navigating raw material volatility and processing constraints. High-performance refractories and ceramic composites depend on tightly controlled calcination, particle sizing, and forming methods, and any disruption in precursor availability or energy costs can compress margins or delay qualification cycles. Third, end-users are demanding more predictable performance without sacrificing flexibility. Facilities running multiple alloys, varying pour rates, or transitioning between aluminum and steel lines expect components that deliver consistent flow characteristics while accommodating frequent changeovers. Overcoming these pressures requires more than incremental material upgrades; it calls for integrated design thinking that aligns nozzle geometry, thermal profiles, and installation practices with real-world operating conditions.
The broader implication is that the market is transitioning from a commodity mindset toward engineered performance. Buyers increasingly evaluate total cost over the casting cycle rather than unit price alone, and suppliers that can demonstrate reliability, repeatability, and shorter changeover times are gaining preference. Simultaneously, the competitive field remains moderately fragmented, with market concentration reflecting a mix of specialized manufacturers and broader industrial players. This structure creates both opportunities for differentiation and risks of margin pressure where products become interchangeable. Companies that can translate material science, application expertise, and field support into measurable operational gains will be best positioned to capture value as buyers prioritize consistency and uptime over lowest upfront cost.
Key Drivers Shaping the Market
Technological innovation is one of the most visible forces reshaping the casting tip and nozzle landscape. Advances in ceramic fiber and aluminum silicate composite formulations have improved high-temperature stability, non-stick behavior, and dimensional consistency, which directly benefits aluminum casting operations where adhesion and thermal shock are persistent concerns. In steel continuous casting, zirconia-based tundish metering nozzles and precision inserts are increasingly relied upon for erosion resistance and controlled discharge, helping maintain stable flow during extended campaigns. Beyond materials, design refinement is accelerating. Nozzle and tip geometries are being optimized to deliver more uniform metal distribution, reduce turbulence, and support consistent solidification behavior. For secondary cooling in continuous casting, improvements in spray pattern uniformity and droplet control are helping producers manage strand temperatures more precisely, which can reduce surface defects and support higher throughput.
Regulatory and operational standards also play a meaningful role in shaping demand. Foundries and casting facilities operate under increasingly stringent expectations for safety, environmental compliance, and process control. While the component itself may not always be the direct subject of regulation, the operational requirements that stem from quality assurance, emissions management, and process reliability indirectly drive preference for products that reduce variability. In steel casting, for example, the need to prevent surface cracks and other strand defects through controlled secondary cooling encourages adoption of nozzles that deliver repeatable spray profiles. In aluminum operations, components that minimize contact-related sticking and support cleaner breakouts can help facilities reduce downtime and rework. These conditions reward suppliers whose products contribute to process stability and help buyers document consistent performance.
Fire Nozzle Market
Demand-side dynamics are shifting as metal producers balance quality, efficiency, and flexibility. Aluminum casting continues to represent the largest application context within this market, reflecting widespread use in high-volume production where controlled flow and thermal management are central to yield and surface quality. Steel casting remains another major pillar, with needs concentrated around tundish metering, ladle-to-tundish flow control, and secondary cooling. A growing emphasis on non-ferrous alloy casting is also expanding the scope of component requirements, as producers work with materials that can impose different thermal and chemical stresses. On the behavioral side, buyers are increasingly aligning procurement with operational outcomes: reduced air and water consumption in cooling systems, longer service life between changeouts, and greater campaign predictability. These priorities favor solutions that combine material reliability with practical usability, especially when they help plants maintain quality while managing throughput.
Supply chain and cost structure dynamics further influence competitive positioning. Producers of advanced refractories and ceramic components face the dual challenge of maintaining material consistency while managing energy-intensive processing steps and input costs. Where suppliers can streamline fabrication, stabilize batch-to-batch performance, and reduce installation complexity, they create tangible value beyond the component itself. At the same time, recent product updates from leading manufacturers indicate a clear emphasis on practical performance attributes such as zero shrinkage at high temperatures, suitability for twin-roll continuous casting, and enhanced non-stick properties for aluminum processing. These developments illustrate how commercial priorities are converging around reliability, ease of integration, and readiness for varied mill configurations. As a result, competitive advantage is increasingly determined by how well a supplier can deliver not just a part, but a solution that fits the operating environment and reduces total friction across the casting cycle.
Competitive Landscape and Leading Strategies
The market features a diverse set of players spanning specialty refractory producers, precision nozzle manufacturers, and companies with deep application focus in either aluminum or steel casting. Several firms have established strong positions by aligning product design with specific process pain points. In aluminum casting, suppliers offering complete tip assemblies designed for rapid insertion and reduced assembly effort are appealing to casthouse operators seeking to minimize setup time and variability during changeovers. In aluminum sheet, foil, and strip production using twin-roll continuous casting, companies emphasizing non-stick behavior and dimensional stability at elevated temperatures are catering to the need for consistent strip quality and reduced contact-related issues. For steel continuous casting, the most differentiated players tend to focus on flow control and secondary cooling precision, where nozzle design and spray uniformity directly influence strand quality and process productivity.
Strategic positioning among leading companies often revolves around three reinforcing advantages: material performance, application engineering, and service reliability. Material performance is foundational; zirconia-based metering nozzles and high-temperature ceramic inserts are commonly associated with erosion resistance and extended campaign life in steel casting, while aluminum silicate and ceramic fiber composites are valued where non-stick behavior and high-temperature stability matter. Application engineering is equally important because casting conditions vary widely by alloy, temperature, pour rate, and equipment geometry. Suppliers that provide interchangeable configurations, predefined installation practices, and guidance on flow control can reduce trial-and-error for buyers and improve repeatability across shifts. Service reliability completes the picture: timely availability of replacement components, predictable lead times, and technical support during qualification and troubleshooting help maintain campaign continuity, which is often more important to buyers than minor price differences.
Recent market developments reinforce the shift toward performance-led differentiation. Updates in aluminum casting nozzle and tip offerings have highlighted high-temperature calcination, non-stick characteristics, and suitability for twin-roll casting environments, reflecting an emphasis on operational consistency and reduced sticking. In steel casting, continued attention to tundish metering, ladle-to-tundish flow control, and secondary cooling spray patterns signals that precision and process stability remain central concerns. These moves suggest that companies are competing less on generic part availability and more on targeted problem solving.
The competitive landscape is evolving along multiple axes. Consolidation is plausible where scale in manufacturing, distribution, or application support can lower cost and broaden portfolio breadth, particularly for suppliers able to serve both aluminum and steel environments. At the same time, fragmentation persists because specific alloy systems, nozzle geometries, and mill configurations create room for specialized players with deep process knowledge. New entrants can still find opportunities by focusing on underserved niches, such as customized metering solutions, improved cooling spray patterns, or components designed for faster changeover in multi-alloy operations. The overall direction points toward greater segmentation by application needs and material requirements, with winners likely to be those that combine material robustness with practical usability and dependable support.
Jet Engine Nozzles Market
Future Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be continued prioritization of reliability and extended campaign performance. As metal producers face pressure to maintain quality while optimizing throughput, components that resist erosion, reduce sticking, and deliver consistent flow will gain preference. This trend favors suppliers that can demonstrate measurable improvements in service life, fewer unplanned interruptions, and stable performance across varying operating conditions. Commercially, this creates opportunities for products backed by strong field data and clear application guidance, especially when buyers can tie component performance to reduced downtime or improved yield.
A second trend will be increased attention to precision in cooling and flow control. In continuous steel casting, uniform spray patterns and controlled secondary cooling are likely to remain central to surface quality and productivity goals. In aluminum operations, the focus will likely stay on reducing contact issues and supporting smooth metal delivery across twin-roll and related casting configurations. As a result, there is commercial potential in solutions that improve process repeatability while helping facilities manage water and air usage more efficiently. Suppliers that can align nozzle design with real-world cooling and discharge requirements will be well placed to capture interest from operators seeking both quality and resource efficiency.
A third trend is the gradual move toward more integrated procurement and qualification approaches. Buyers are increasingly evaluating parts in the context of broader process goals, including changeover speed, installation consistency, and support during commissioning or troubleshooting. This creates room for differentiated offerings that reduce assembly complexity, standardize fit-up, and simplify supplier coordination across multiple casting lines. However, uncertainty remains. Raw material costs, energy intensity of high-temperature processing, and the pace of equipment upgrades in end-user facilities can influence adoption timing and margin resilience. Shifts in alloy demand, changes in domestic production philosophy, or supply interruptions can also alter purchasing patterns. Companies that build flexibility into product lines and maintain reliable supply and technical support will be better equipped to navigate these variables.
Actionable Guidance for Decision Makers
For manufacturers and producers, the priority should be to evaluate casting tips and nozzles based on total process impact rather than unit price alone. That means considering service life, installation time, flow consistency, cooling performance, and support during changeovers. Where multiple alloys or casting configurations are in use, standardizing on components that balance flexibility with predictable performance can reduce variability and simplify maintenance planning. It is equally important to align procurement with operational objectives such as surface quality, campaign continuity, and resource efficiency, then validate component choices through controlled trials that reflect actual plant conditions.
For investors, the market offers exposure to steady, demand-backed growth in enabling casting components, but differentiation will matter more than broad participation. The most compelling opportunities are likely to be found in suppliers with strong material capability, clear application focus, and the ability to reduce total friction for end-users. Evaluating track records in qualification support, supply reliability, and portfolio breadth across aluminum and steel environments can help identify businesses positioned to capture value as buyers prioritize consistency and uptime. Monitoring product updates that emphasize high-temperature stability, non-stick behavior, and precision cooling can also provide early signals of where commercial emphasis is heading.
PW Consulting
For procurement and sourcing teams, the most effective strategy is to structure evaluations around performance criteria that reflect the operating environment. This includes requesting application-specific data, comparing installation and changeover requirements, and clarifying lead times and support arrangements before committing to larger volumes. Where possible, coordinate with process engineers to ensure that component selection supports downstream goals such as strand quality, cooling uniformity, and campaign predictability. For organizations seeking a fuller picture of segment dynamics, regional patterns, and supplier-specific positioning, the complete research report provides more detailed breakdowns and tailored recommendations to support procurement planning and strategic review.
For detailed analysis of this topic, please visit the official page: Worldwide Casting Tip And Nozzle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Trends and Commercial Opportunities in the Worldwide Non-invasive Ventilation Masks Market
Market Overview: Navigating a Transforming Respiratory Care Landscape
The global non-invasive ventilation (NIV) masks market is experiencing a period of sustained expansion, driven by evolving respiratory care needs and a shifting clinical paradigm toward less invasive treatment modalities. Market valuation has grown steadily from 2020 through 2025, reflecting consistent demand across healthcare settings. The trajectory from 2026 to 2032 indicates continued appreciation, supported by expanding indications, aging demographics, and technological refinement. A compound annual growth rate of 6.21 percent positions the category as a resilient segment within the broader respiratory devices ecosystem, with revenue measured in millions of U.S. dollars.
Revenue distribution reveals that North America continues to represent the largest regional share, followed by Europe and Asia Pacific. The Americas benefit from mature reimbursement frameworks, high adoption of home-based respiratory therapies, and a well-established hospital procurement infrastructure. Europe maintains a strong foothold through structured clinical guidelines and broad access to non-invasive ventilation in both acute and chronic care pathways. Asia Pacific is increasingly contributing to growth momentum as healthcare systems scale capacity, respiratory disease prevalence rises, and access to advanced ventilation technologies improves across urban and semi-urban facilities. Latin America and the Middle East and Africa, while smaller in absolute terms, are developing markets where infrastructure investments and disease burden are gradually expanding the addressable patient base.
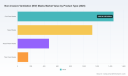
On the product side, full-face masks lead in revenue contribution, reflecting their broad application in acute and chronic non-invasive ventilation scenarios where secure sealing and high-pressure tolerance are essential. Nasal masks form a substantial second category, favored for patient comfort and suitability in longer-duration therapy. Nasal pillow masks and total face masks represent smaller but strategically important sub-segments, each addressing distinct clinical workflows and patient preferences. From an end-user perspective, hospitals and clinics remain the dominant application environment, driven by acute care demand and institutional procurement cycles. Home healthcare constitutes a significant and growing share, underscoring the shift toward decentralized respiratory management. Ambulatory care centers represent a more niche but expanding channel, particularly in settings that emphasize outpatient respiratory support and early discharge pathways.
Sleep Apnea Masks Market
Market structure is moderately concentrated, with a small group of leading manufacturers capturing a majority of revenue. This concentration reflects the technical barriers associated with mask design, sealing performance, material quality, and regulatory clearance requirements. At the same time, the presence of specialized and regional players indicates an industry in which differentiation through ergonomics, patient comfort, and clinical-specific configurations remains viable. Several key challenges are shaping the current market inflection point. First, product fit and patient adherence continue to be persistent clinical concerns; even advanced mask designs must contend with variability in facial anatomy, pressure tolerance, and prolonged wear comfort. Second, the balance between single-use clinical efficiency and cost containment is becoming more pronounced, particularly as hospitals evaluate total cost of care rather than unit price alone. Third, regulatory pathways and reimbursement frameworks are evolving in ways that influence both product development priorities and market access timing, especially in the United States where coverage criteria and device classification directly affect adoption velocity.
For executives and investors, the core implication is that the market is expanding, but growth is not uniformly distributed across products, channels, or regions. Competitive success depends on aligning design, clinical evidence, and access strategy with the environments where non-invasive ventilation is most actively deployed.
PW Consulting
Key Growth Drivers: Technology, Policy, Demand, and Supply Chain Dynamics
Several interconnected forces are accelerating the expansion of the NIV masks market. The first and most visible is technological innovation in mask design and interface engineering. Manufacturers are increasingly focusing on cushion materials, seal stability under varying pressure conditions, and headgear architectures that reduce pressure points while preserving therapeutic effectiveness. Medical-grade silicone remains a common interface material because of its flexibility, hypoallergenic profile, and ability to conform to facial contours for effective sealing. This material foundation supports ongoing refinement rather than radical substitution, enabling manufacturers to iterate on comfort and performance without compromising clinical reliability. Recent product introductions illustrate this trajectory, including mask portfolios that span nasal, full-face, and specialized configurations, with interchangeable components designed to adapt to different therapy setups. Such modularity is particularly relevant in hospital environments, where clinicians value flexibility across patient types and ventilation modes.
A second driver is the evolving policy and regulatory environment. In the United States, NIV masks are classified as Class II devices under 21 CFR 868.5895 and require 510(k) clearance for marketing as accessories for non-invasive ventilation. This regulatory structure creates a defined pathway for market entry, but it also places a premium on timely clearance, clinical differentiation, and documentation of intended use. Recent regulatory activity underscores how actively the competitive field is moving. Clearances have been obtained for hospital-focused vented and non-vented mask ranges, as well as for families of NIV masks intended for single-patient use in the hospital environment. These approvals matter because they expand the set of commercially available options and can shift procurement decisions by giving clinicians more choices in fit, circuit compatibility, and infection-control preferences. Regulatory momentum also signals to the market that non-invasive ventilation interfaces remain a priority category for device innovation and review.
The third driver lies on the demand side, where clinical practice and care-setting trends are reshaping adoption. There is a continuing shift toward earlier and broader use of non-invasive ventilation in both acute and chronic respiratory failure management, particularly when clinicians seek to avoid intubation or support patients outside the intensive care unit. At the same time, home-based respiratory care is becoming more central to long-term management strategies. CMS updated the National Coverage Determination for non-invasive positive pressure ventilation in the home for chronic respiratory failure consequent to COPD, expanding coverage for respiratory assist devices and home mechanical ventilators with revised criteria. Notably, the updated framework no longer requires overnight oximetry in certain cases and uses clinical thresholds such as PaCO2 ≥ 52 mmHg or documentation that sleep apnea is not the predominant cause. This kind of reimbursement evolution can broaden the eligible patient population and strengthen the economic case for home-based non-invasive therapy, indirectly supporting demand for appropriate masks and interfaces over time.
Non-invasive Ventilation Masks Market
A fourth driver is the changing supply chain and cost structure environment. Healthcare providers are increasingly attentive not only to device performance but also to the downstream economics of therapy, including consumables, staffing burden, and infection-control workflows. This has increased interest in products that can simplify setup, improve seal consistency, and reduce remasking or adjustment time. For manufacturers, cost pressures are encouraging disciplined material selection, manufacturing efficiency, and design choices that balance performance with scalability. The market is also seeing interest in products tailored to pediatric and infant care, where specialized sizing and comfort features can address a distinct clinical need and create opportunities for differentiation. Newer catalog additions targeting infants and children highlight how comfort-oriented engineering, swivel elbow designs, and adjustable fitting mechanisms are being used to meet the requirements of smaller patient populations.
Taken together, these drivers suggest that the NIV masks market is being shaped less by a single breakthrough and more by cumulative improvement across materials, regulatory readiness, reimbursement alignment, and clinical workflow. Companies that can integrate these elements into coherent product and access strategies are better positioned to convert clinical need into durable commercial traction.
Competitive Landscape: Positioning, Differentiation, and Evolving Market Structure
The competitive environment in the NIV masks market is defined by a combination of established multinational manufacturers and specialized players with strong clinical or regional focus. ResMed maintains a prominent position through hospital non-vented full-face NIV masks designed for single-use, with product options engineered to seal effectively under high pressures up to 40 cm H2O. This emphasis on high-pressure performance and single-use design aligns with acute-care requirements where seal reliability and infection-control considerations are paramount. Fisher & Paykel Healthcare offers a broad portfolio that includes full-face masks with vented and non-vented configurations in multiple sizes, as well as under-nose, bridge-free designs compatible with single-limb circuits. Its recent FDA 510(k) clearance for a hospital vented full-face mask range illustrates a strategy centered on expanding clinically relevant options and strengthening compatibility with common ventilation circuits. Philips Respironics contributes oro-nasal and face mask solutions with headgear and cushion designs intended for hospital-based non-invasive ventilation, reinforcing its presence in institutional care settings. Hamilton Medical has expanded its mask portfolio across nasal, full-face, and specialized configurations with interchangeable elbows and multiple sizes for adult and pediatric patients, reflecting a product architecture built around adaptability across therapy options.
Beyond these larger platforms, a second tier of competitors brings distinct value propositions. Dräger emphasizes customizable NIV masks as part of complete non-invasive ventilation solutions for acute care, with a focus on seal and fit to support gentle and cost-effective therapy. Dimar S.p.A. manufactures families of NIV masks for single-patient use in hospital environments, positioning itself as a provider of patient-interface accessories within broader ventilation workflows. GaleMed focuses on premium NIV CPAP masks designed for comfort and therapy performance, while Hans Rudolph has reimagined full-face masks with an emphasis on fit and care without sacrificing treatment effectiveness. DEAS supplies an extensive portfolio across anesthesia, ventilation, and non-invasive ventilation needs, and AirLife offers lightweight silicone full-face and nasal masks in vented and non-vented options across multiple sizes, underscoring clinician reliability and patient comfort. These companies illustrate that even within a concentrated market, there is meaningful differentiation in design philosophy, target setting, and end-user value proposition.
The strategic positioning of leading players tends to converge around a few priorities. The first is clinical fit and sealing performance, especially under high pressure or during extended use. The second is compatibility with different circuit types and hospital workflows, including vented versus non-vented configurations and single-limb circuit use. The third is patient comfort and ease of fitting, which affects adherence and reduces clinical adjustment time. A fourth priority is regulatory readiness and documentation, which has become increasingly important as procurement teams evaluate both clinical performance and compliance certainty. Companies that can combine these attributes with a clear intended-use narrative often gain an advantage in acute-care formulary decisions and, increasingly, in home-care and ambulatory channels where ease of use matters.
Market structure is evolving along several axes. Consolidation remains a possibility as larger platforms seek to strengthen respiratory portfolios and smaller players look for partnership or distribution pathways that broaden reach. At the same time, differentiation is intensifying rather than narrowing, because mask design is highly application-specific. A configuration that performs well in acute hospital ventilation may not be ideal for chronic home use, and vice versa. This creates room for specialized entrants that target particular patient populations, care settings, or clinical workflows. The presence of recent product launches and regulatory clearances across multiple companies suggests an industry in motion, with competitors actively expanding portfolios to address gaps in sizing, circuit compatibility, and comfort. Newer entries and catalog expansions in pediatric and infant segments further indicate that incumbents are not only competing on scale but also on clinical specificity.
For buyers and investors, the practical implication is that the market is not a simple hierarchy of incumbents and followers. It is a landscape in which leadership is contested through product architecture, regulatory timing, and alignment with the care settings where non-invasive ventilation is most actively adopted. Strategic advantage will likely accrue to those who can demonstrate consistent performance across the environments that matter most to their customers.
Future Outlook: Trajectories, Opportunities, and Watchpoints
Over the next three to five years, the NIV masks market is likely to be shaped by a small number of high-impact trends. The first is the continued expansion of home-based and ambulatory non-invasive ventilation, supported by evolving reimbursement frameworks and a broader shift toward managing chronic respiratory conditions outside the hospital. If coverage pathways remain favorable and clinical confidence in home NIPPV grows, demand for masks suited to long-term wear, ease of fitting, and patient convenience could increasingly influence product mix and procurement patterns. This creates an opportunity for manufacturers that can bridge acute-care performance with home-care usability, especially where patient adherence is a decisive clinical factor.
The second trend is the growth of application-specific and population-specific mask designs. The market is already seeing movement toward more modular portfolios, pediatric and infant configurations, and masks optimized for particular circuit types and therapy modes. As clinical protocols continue to differentiate between acute ventilation, chronic management, and transitional care, products that are purpose-built for these contexts may gain preference over generalized offerings. This trend favors companies that invest in fitting systems, sizing breadth, and design features that reduce mask adjustment and improve comfort across varied patient anatomies.
The third trend is the increasing importance of regulatory timing and evidence-driven differentiation. Because NIV masks are Class II devices requiring 510(k) clearance in the U.S., and because hospital procurement teams increasingly weigh compliance certainty alongside performance, the speed and clarity of regulatory approval can be a meaningful commercial factor. Companies that align product development with reimbursement and clinical evidence needs may be better positioned to capture adoption in high-value settings. At the same time, cost containment pressures will likely remain a persistent watchpoint; providers may favor solutions that reduce remasking, simplify infection-control workflows, and support predictable consumable spending.
These trends carry both opportunity and uncertainty. On the opportunity side, the combination of broader home-care use, more targeted product designs, and active regulatory activity points to a market in which well-positioned portfolios can gain share without relying solely on price competition. On the risk side, market growth may be uneven if reimbursement policies change, if clinical guidelines shift the balance between non-invasive and invasive approaches, or if supply chain and material costs alter margin expectations. Additionally, patient adherence challenges and the inherent variability of facial anatomy mean that even strong product designs must continue to earn confidence through real-world performance. The companies most likely to navigate this environment successfully will be those that treat mask design not as an isolated accessory category, but as an integral part of the broader non-invasive ventilation pathway.
Strategic Implications: What Decision-Makers Should Do Next
For manufacturers, the immediate priority is to align product roadmaps with the care settings and patient populations generating the strongest demand. This means investing in seal stability, comfort, and modular compatibility for hospital use while also ensuring that home-care and ambulatory offerings address adherence and ease of fitting. Regulatory planning should be treated as a strategic lever rather than a compliance checkbox, particularly given the active clearance environment and the commercial value of timely market access. Companies should also consider where portfolio breadth adds real clinical value versus where it simply increases complexity, because buyers are likely to reward designs that simplify selection and reduce workflow friction.
For investors, the key question is not whether the category will grow, but which segments and strategies will convert growth into durable margin and share gains. Preference may be given to players with differentiated product architecture, clear regulatory momentum, and strong alignment with reimbursement trends in home and hospital care. Particular attention should be paid to companies that can demonstrate value beyond unit price, including reductions in clinical adjustment time, improved adherence, and compatibility with evolving ventilation circuits. Portfolio exposure to pediatric, infant, and specialized acute-care configurations may offer additional optionality, especially if these segments continue to expand in clinical relevance.
For procurement and clinical decision-makers, the practical aim is to evaluate masks not only on immediate specifications but also on total therapy performance. This includes assessing seal reliability under anticipated pressure ranges, compatibility with existing circuits and workflows, sizing flexibility for diverse patient populations, and the evidence or clearance status that supports confident formulary inclusion. Given the pace of product introductions and regulatory updates, ongoing market intelligence can help procurement teams avoid delays in adoption and ensure that purchasing decisions reflect the latest clinically relevant options and access conditions.
As the market evolves, the winners will be those who connect product design, regulatory readiness, reimbursement awareness, and real-world usability into a coherent strategy. Detailed segment-level data, competitive benchmarks, and tailored scenario analysis can help organizations move from general market awareness to specific, executable decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Non-invasive Ventilation (NIV) Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Biliary Catheters Market: Why 5.48% CAGR Signals a Strategic Shift by 2032
By pmarketresearch, 2026-09-18
Globular Trends in the Worldwide Biliary Catheters Market: Strategic Opportunities for Industry Leaders
Market Overview: Scale, Trajectory, and Critical Challenges
The global biliary catheters market has entered a phase of sustained expansion, driven by an evolving interventional gastroenterology landscape and growing demand for minimally invasive biliary drainage solutions. Valued at approximately $645.5 million in the base year of 2025, the market has demonstrated consistent growth from $503.18 million in 2020. This trajectory reflects a compound annual growth rate of 5.48 percent over the forecast period extending through 2032, with projected revenues approaching $937.75 million by the end of the forecast horizon. Such figures underscore a market that is not merely expanding in absolute terms but maturing in complexity, as clinical protocols, reimbursement frameworks, and product engineering converge to shape procurement and adoption decisions.
PW Consulting
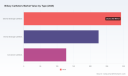
The geographic distribution of demand reveals a market where North America and Europe continue to anchor the largest revenue shares, supported by established endoscopy infrastructure, high procedural volumes, and mature reimbursement pathways. Asia Pacific represents a rapidly intensifying region, where rising healthcare expenditure, expanding specialty clinic networks, and growing adoption of percutaneous biliary interventions are accelerating volume growth. Latin America and the Middle East and Africa contribute smaller but strategically relevant portions of the market, often characterized by procurement cycles tied to public health initiatives and regional capacity-building programs. Across these regions, the product mix leans heavily toward external drainage catheters, which maintain the largest share by type, followed by internal drainage catheters and conversion catheters that serve more specialized clinical pathways. Hospitals remain the dominant end-user segment, reflecting the central role of inpatient interventional suites and radiology departments in biliary drainage procedures, while specialty clinics and ambulatory surgical centers represent growing channels for routine and follow-up interventions.
Despite the favorable growth trajectory, the market faces a set of structural challenges that will define competitive dynamics over the coming years. First, the regulatory classification of biliary catheters and accessories under Class II special controls introduces a persistent compliance burden. Manufacturers must navigate clearance pathways that demand rigorous demonstration of safety, performance, and intended use, particularly when introducing design modifications or new material formulations. Second, reimbursement architecture exerts significant influence on adoption patterns. Procedural coding for catheter placement, exchange, and imaging guidance creates a billing environment where clinical utility must be paired with clear documentation and coding accuracy. Any shifts in coverage policy, coding interpretation, or hospital cost pressure can rapidly alter procurement behavior. Third, the market exhibits meaningful concentration, with the top three competitors accounting for over forty percent of revenue and the top five exceeding fifty-eight percent. This concentration signals both the presence of established incumbents with strong distribution relationships and the potential for consolidation, as smaller manufacturers seek scale or partnerships to compete effectively. Together, these factors create a market where growth is available, but capturing it requires disciplined execution across regulatory, clinical, and commercial dimensions.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
The expansion of the biliary catheters market is propelled by a convergence of clinical, technical, and systemic forces. At the forefront is technological innovation in catheter design and delivery systems. Manufacturers are increasingly differentiating products through features such as locking loop mechanisms, radiopaque markers, hydrophilic coatings, and enlarged drainage apertures. These enhancements address practical clinical needs: improved positional stability during prolonged drainage, clearer fluoroscopic visibility during placement, reduced friction during insertion, and higher drainage efficiency for complex strictures or obstructed ducts. The availability of multiple configurations, including large-hole drainage catheters and hydrophilic-coated variants, reflects an industry response to the diversity of biliary anatomy and procedural contexts. In parallel, the use of nitinol reinforcement in select drainage catheters illustrates a focus on kink resistance and structural durability, attributes that reduce complications and improve reliability in long-term or tortuous drainage pathways.
Worldwide Pancreatic and Biliary Stent Market
Regulatory and reimbursement dynamics form a second critical driver. Biliary catheters and accessories are classified as Class II devices under special controls, a framework that balances access with oversight by requiring submission of performance data and adherence to recognized standards. Recent regulatory clearances illustrate how incremental innovation can still unlock market entry. For example, a wireguided balloon dilation catheter for biliary applications recently received FDA 510(k) clearance under a classification covering stents, drains, and dilators for biliary ducts, signaling continued openness to devices that bridge dilation and drainage workflows. Similarly, a biodegradable pancreatic stent gained clearance under the biliary catheter and accessories regulation, highlighting how adjacent product categories can leverage existing regulatory pathways to introduce materials and designs that may influence future biliary drainage strategies. On the reimbursement side, procedural codes governing percutaneous biliary drainage, exchange, and imaging guidance create a structured but scrutinized economic environment. Hospitals and clinics evaluate catheter choices not only on clinical performance but also on coding efficiency, documentation burden, and total cost of care, making reimbursement alignment a decisive factor in purchasing decisions.
Demand-side changes represent a third driver. The procedural volume for biliary drainage is expanding as interventional endoscopy and interventional radiology continue to gain traction for managing obstructions, strictures, leaks, and post-surgical complications. Clinicians increasingly favor percutaneous and endoscopic approaches that minimize invasiveness, reduce recovery time, and support outpatient or short-stay pathways where feasible. This shift is amplified by staffing and capacity constraints in many healthcare systems, which incentivize solutions that streamline procedures, reduce complication rates, and support repeat interventions without compromising outcomes. The growth of specialty clinics and ambulatory surgical centers as procurement channels reflects this trend, as these settings seek durable, user-friendly devices that fit high-throughput workflows and support standardized protocols.
Supply chain and cost structure considerations round out the driver set. The market includes a mix of large multinational manufacturers and specialized regional producers, creating a competitive ecosystem where scale, sourcing reliability, and manufacturing precision all matter. Material selection, coating consistency, and dimensional tolerances influence both performance and cost, while regional manufacturing footprints can affect lead times, logistics resilience, and pricing flexibility. In an environment where hospitals are sensitive to total cost and supply continuity, suppliers capable of delivering dependable quality, clear technical support, and responsive service gain a measurable advantage. The presence of regional manufacturers in markets such as India and Taiwan also indicates an ongoing diversification of supply sources, which can introduce cost-competitive alternatives and expand availability in emerging procurement contexts.
Competitive Landscape: Strategic Positioning and Market Evolution
The competitive field in biliary catheters is shaped by a combination of established device manufacturers and focused specialists, each pursuing distinct strategic advantages. Leading participants emphasize product portfolios that span multiple catheter types, procedural techniques, and delivery approaches. Some suppliers have built reputations around locking loop options and radiopaque markers designed for percutaneous biliary drainage, aiming to reduce migration risk and improve procedural visibility. Others differentiate through multipurpose styles compatible with direct stick or Seldinger techniques, providing clinicians with flexibility across varied access scenarios. A further set of players highlights large drainage apertures and hydrophilic coatings, positioning their devices around drainage efficiency and ease of insertion. This diversity of design philosophy indicates a market where clinical differentiation remains viable, but only when paired with robust evidence, reliable supply, and strong service support.
Strategic positioning among incumbents often revolves around three pillars: portfolio breadth, procedural alignment, and integration with procedural kits. Portfolios that cover external, internal, and conversion catheters allow suppliers to address a wider range of clinical indications and maintain relationships across multiple procedure types. Procedural alignment appears in designs that accommodate common access techniques and in the availability of kits that bundle catheters with necessary accessories, simplifying procurement and standardizing setup. Integration with broader interventional portfolios is also notable, as some manufacturers embed biliary catheters within larger drainage and interventional product lines, leveraging cross-selling and clinical familiarity to reinforce market presence. These approaches help incumbents defend share in a concentrated market while creating barriers for new entrants that lack equivalent clinical relationships or procedural coverage.
The market is evolving along several trajectories. Consolidation pressure persists given the revenue concentration among leading firms, which may encourage acquisitions, partnerships, or licensing arrangements as smaller manufacturers seek scale and broader distribution. At the same time, differentiation is increasing in the opposite direction, as specialized designs and material innovations create niches for focused players who can deliver distinct clinical value. New entrants and regional manufacturers add further complexity by introducing cost-competitive options and expanding supply diversity, particularly in growth regions where local support and affordability influence purchasing. Regulatory developments will continue to shape this evolution: clearances that validate new designs or materials can open doors for innovators, while the Class II special controls framework ensures that all participants maintain a baseline of demonstrated safety and performance. Meanwhile, reimbursement dynamics will act as a constant filter, rewarding devices that support efficient coding, clear documentation, and predictable procedural workflows. The net effect is a landscape where scale and relationships matter, but precise clinical utility and adaptable commercial models increasingly determine who gains share.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Looking ahead, the biliary catheters market is likely to be shaped by three interrelated trends. The first is continued product refinement oriented toward procedural efficiency and complication reduction. Expect broader adoption of catheters with enhanced drainage area, improved visibility features, and coatings or reinforcements that reduce friction and kinking. As clinicians accumulate experience with these design improvements, procurement patterns may favor devices that demonstrably support faster setup, more reliable positioning, and fewer exchanges, especially in high-volume settings where time and outcomes directly affect throughput and cost.
The second trend is the growing importance of procedural ecosystem alignment. Devices will increasingly be evaluated not in isolation but as part of integrated workflows that include access technique, imaging guidance, coding efficiency, and post-procedure management. Suppliers that provide clear guidance on coding relevance, procedural setup, and exchange protocols may gain an edge, particularly as hospitals seek to reduce administrative friction and standardize care pathways. This trend creates opportunities for manufacturers that invest in clinician education, procedural support materials, and documentation-friendly product information.
Medical Catheters Market
The third trend is regional expansion coupled with supply chain diversification. Growth in Asia Pacific and other emerging procurement regions will likely accelerate as infrastructure improves and procedural volumes rise. At the same time, the presence of regional manufacturers and varied sourcing options may increase price competition and broaden availability. This dynamic presents both opportunity and risk: it can expand addressable volume and create partnerships for global suppliers, but it can also pressure margins and require careful quality assurance and service planning. Uncertainty remains around the pace of reimbursement evolution, the stringency of regulatory review for design changes, and potential shifts in procurement budgets as healthcare systems balance cost control with procedural demand. Companies that monitor these signals closely and align product strategy with local clinical and economic realities will be better positioned to convert growth into sustainable share.
Strategic Actions for Decision Makers
For manufacturers, the priority is to sharpen clinical differentiation while reinforcing commercial reliability. Invest in design features that address measurable procedural needs, and support those features with clear documentation, compatible procedural kits, and responsive technical service. Ensure that regulatory and reimbursement considerations are embedded in product planning from the outset, so that new designs are not only technically sound but also aligned with coding and procurement realities. Building relationships with high-volume centers and specialty clinics can help validate performance in real workflows and strengthen adoption over time.
For investors, the market rewards disciplined capital allocation toward companies with defensible clinical positioning, stable supply operations, and scalable commercial infrastructure. Evaluate not only product portfolios but also the strength of procedural support, the consistency of regulatory execution, and the ability to navigate reimbursement frameworks. Opportunities may arise through targeted partnerships, acquisitions of niche technologies, or investments in regional manufacturing capability that improves supply resilience and market access. Attention to concentration dynamics is important, as consolidation could reshape competitive positions and create both risks and openings.
For procurement leaders and clinical decision makers, the focus should be on total value rather than unit price alone. Assess catheters based on drainage performance, insertion reliability, compatibility with existing access techniques, and support for efficient documentation and coding. Standardizing where appropriate can reduce variation and simplify training, while selective use of specialized designs can address complex cases more effectively. Engaging suppliers that provide clear procedural guidance and dependable service can help maintain throughput and reduce avoidable complications. As the market continues to evolve, access to detailed segment-level intelligence and tailored commercial insights can support more precise planning and risk management. Readers seeking deeper segmentation data, competitive benchmarking, and customized strategic guidance may consider reviewing PW Consulting’s comprehensive research report on this market.
For detailed analysis of this topic, please visit the official page: Worldwide Biliary Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Probe Cards Market: Why 7.45% CAGR and Asia Pacific Dominance Redefine Growth
By pmarketresearch, 2026-09-18
Navigating the Worldwide Probe Cards Market: Strategic Trends and Commercial Opportunities (2025–2032)
The global market for probe cards entered a phase of structural expansion in 2025, with total revenue reaching approximately USD 2.94 billion. Over the historical window from 2020 through 2025, the segment demonstrated volatile but ultimately upward momentum, reflecting both cyclical semiconductor demand and the accelerating need for wafer-level test infrastructure. Looking ahead to 2032, revenue is projected to surpass USD 4.8 billion, driven by a consistent compound annual growth rate of 7.45 percent. This trajectory signals more than steady demand; it indicates a market undergoing technological maturation, geographic rebalancing, and increasing specialization tied to advanced packaging and high-performance computing workloads.
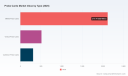
It is important to recognize the limited window between headline growth and operational reality. The market remains highly concentrated, with three firms capturing more than half of total revenue and five firms accounting for nearly three-quarters. This concentration creates both stability and fragility. Incumbent suppliers benefit from entrenched qualification cycles, long-term design-in relationships, and deep process knowledge, yet it also means that late entrants and regional players must find sharp differentiation to escape the margins of the middle market. At the same time, the customer base is fragmenting by design complexity. Foundries and logic manufacturers, memory device producers, and analog/Radio Frequency fabricated ecosystems each place different demands on probe card performance, lifespan, and interface architecture, making one-size-fits-all solutions increasingly untenable.
Within that backdrop, the industry faces several defining challenges. The first is technological transition at advanced nodes. As wafer geometries shrink and multi-die architectures become standard, probe cards must sustain finer pitch, higher pin counts, and more stable contact reliability across thousands of test cycles. The second challenge is timing, particularly the alignment between probe card availability and fab ramp schedules. Longer lead times can create bottlenecks at the most critical moment in product launches, especially when test capacity becomes a gating factor for yield maturation. The third challenge is cost pressure combined with scope expansion. Customers increasingly expect suppliers to support not only traditional wafer acceptance test but also more complex validation for 3D and 2.5D integration, high-bandwidth memory, and advanced logic stacks. Meeting these expectations requires more than incremental refinements; it demands new materials strategies, precision manufacturing, and closer co-development with device makers.
For business leaders, the immediate implication is straightforward: probe cards are no longer a commoditized consumable. They are a strategic interface between process technology and test yield, and their performance increasingly determines how quickly new nodes and new packaging formats can reach volume production. Companies that understand where the market is intensifying—and where it is splintering—will be better positioned to plan product roadmaps, secure qualified supply, and make informed capital decisions.
Key Drivers Reshaping the Probe Cards Market
Several forces are converging to shape demand, supply, and competitive positioning over the next several years. The most consequential is the pace of device architecture change. Advanced nodes, high-bandwidth memory stacks, and heterogeneous integration are pushing test interfaces to their practical limits. As design rules tighten, probe cards must deliver higher contact density, improved signal integrity, and more consistent mechanical behavior across large wafer areas. That requirement alone is accelerating adoption of micro-electro-mechanical systems-based probe cards, which can support finer pitch and higher pin counts more effectively than many legacy approaches. Vertical probe card designs are also gaining relevance because they can provide improved reliability and easier integration in certain advanced test configurations. The result is a market in which product architecture choices are being driven by test requirements that are themselves dictated by device complexity, not by probe card conventions.
Policy and regional industrial strategy form the second major driver. Semiconductor sovereignty efforts have encouraged governments to support domestic fabrication capacity, packaging ecosystems, and qualifying local suppliers. This is visible in new facility investments and regional expansion strategies that align probe card production more closely with where advanced fabs are being built. A notable example is the opening of an approximately EUR 80 million facility in Dresden aimed at supporting European semiconductor fabs, a move that reflects a broader shift toward localized supply and regional resilience. In parallel, tighter export controls and trade barriers are beginning to reshape cross-border equipment and component flows. These dynamics do not simply alter logistics; they influence which companies can serve which markets, how long qualification cycles take, and whether global suppliers must assemble regional production footprints to remain competitive.
The third driver is demand-side behavior across end-use markets. Memory remains a central application for probe cards, but the composition of memory demand is changing as high-bandwidth memory becomes tightly coupled with accelerator and AI workloads. Foundries and logic manufacturers continue to dominate revenue share, but the test requirements within that segment are diversifying rapidly. New architectures require probe card solutions that can handle more complex test patterns, higher bandwidth needs, and more demanding mechanical tolerance. At the same time, advanced packaging trends such as chiplets are changing the test conversation from single-die validation to multi-component interface validation. This broadens the scope of probe card design and encourages closer partnership between test suppliers and packaging or assembly houses.
Supply chain and cost dynamics complete the picture. Raw material constraints and geopolitical tensions have introduced meaningful variability into production planning. In recent years, lead times for probe card production have experienced delays of up to 20 percent in some cases, illustrating how fragile schedules can become when materials such as tungsten and copper are disrupted or when regional trade conditions shift. Ceramic substrates for probe cards, particularly 300mm formats, also represent a concentrated materials dependency, with a dominant share of the relevant materials market tied to those components. In response, manufacturers are increasing localized production and diversifying supply chains, reducing exposure to single-source bottlenecks. This shift has strategic implications: suppliers that can guarantee stable lead times, consistent quality, and resilient sourcing are increasingly differentiating themselves on reliability as much as on performance.
The overarching insight is that probe card demand is being shaped at the intersection of design complexity, regional policy, and supply resilience. Each of these drivers pushes the market toward higher specialization and tighter co-development, which in turn raises the value of suppliers that can move quickly, qualify early, and sustain production predictability.
Competitive Landscape and Leading Strategies
The probe cards market continues to be defined by a relatively small group of dominant suppliers supported by a broader field of specialized players. At the top tier, leading global providers of advanced wafer probe cards have built strong positions across logic, foundry, DRAM, and high-bandwidth memory applications. These companies compete not just on probe card hardware, but on the ability to sustain technology roadmaps, secure qualification with major manufacturers, and support complex test environments at scale. Their strength comes from a combination of process expertise, broad application coverage, and long-established relationships with high-volume device makers.
A second tier of major suppliers has expanded its relevance through advanced micro-electro-mechanical systems and vertical probe technologies, often targeting high-performance wafer testing for global foundries and integrated device manufacturers. Another cluster of well-established Japanese manufacturers focuses on precision probe cards for fine-pitch and advanced node testing, leveraging strong engineering heritage and close ties to Asian semiconductor ecosystems. Taiwan-based suppliers have strengthened their presence by emphasizing innovative solutions, with some expanding capacity to address AI and high-performance computing-related demand. South Korean suppliers remain important participants, especially where memory and logic testing intersect with domestic fabrication priorities. European and UK-based firms contribute specialized capabilities, including high-quality contact solutions, blade and cantilever designs, and vertical probe cards with high voltage or current capabilities. Together, these players create a market in which geography, technology focus, and application specialization all matter.
Recent developments show how companies are competing for positional advantage. One major supplier strengthened its micro-electro-mechanical systems position by acquiring a California-based firm, adding patents tied to vertical spring optimization for probe cards. That kind of move illustrates a broader pattern: incumbents are trying to lock in capability advantages that directly affect contact reliability and design flexibility. On the qualification side, one Japanese manufacturer secured recognition as a primary supplier for 2 nm probe card solutions after co-development work with TSMC, a milestone that underscores how advanced node access can be earned through sustained collaboration rather than product announcements alone. Another Asian supplier partnered with a major assembly and test player to co-develop chiplet-ready probe cards, signaling that test strategy is increasingly extending beyond the wafer into package-level validation. On the product side, a new series of 3D/2.5D micro-electro-mechanical systems probe cards for wafer acceptance test applications has entered the market with fine-pitch and high-pin-count support, reflecting the growing need for specialized tools in advanced packaging test flows. Meanwhile, regional expansion continues, with new facility investments in Taiwan designed to address demand from AI chip testing, and other firms pursuing localized production and supply chain diversification to reduce exposure to material disruptions.
The competitive landscape is evolving along several axes at once. Integration is increasing where large suppliers absorb niche technology or complementary intellectual property to broaden their portfolios. Differentiation is sharpening around advanced node qualification, high-bandwidth memory, chiplet-related test support, and materials or design innovations that improve contact performance. New entry is difficult at the top of the market because of qualification barriers and entrenched design-ins, but opportunities remain for specialists that can serve specific applications, support regional fabs, or provide tailored solutions where standard offerings fall short. The most resilient companies are likely to be those that combine technical precision with customer co-development, regional supply visibility, and the ability to move from prototype to volume with predictable timing.
PW Consulting
Forward Outlook: Three Trends Defining the Next Three to Five Years
The first trend to watch is the deepening alignment between probe card architecture and advanced packaging roadmaps. As 3D, 2.5D, and chiplet-based designs become more common in high-value product categories, probe card solutions will need to support more intricate test interfaces and more demanding mechanical requirements. Companies that invest early in designs suited to fine-pitch, high-pin-count, and high-density test conditions will be better positioned to participate in next-generation validation cycles. The commercial opportunity here is not simply selling more cards; it is becoming embedded in test plans before production ramps begin.
The second trend is the continued rebalancing of manufacturing geography. Regional fab expansion, policy support, and supply chain risk mitigation are encouraging localized production and material diversification. Suppliers with flexible production footprints and resilient sourcing strategies will have an advantage in meeting lead-time expectations and maintaining continuity during disruption. For customers, this trend creates both optionality and complexity: multiple regional sources can reduce dependency, but they also increase the need for qualification discipline and supplier management.
The third trend is the growing premium on reliability and predictability in test supply. As probe cards become more technically specialized and more tightly coupled to advanced node and memory roadmaps, the cost of late delivery or unstable performance rises. Buyers will increasingly reward suppliers that can demonstrate consistent lead times, stable materials availability, and strong co-development processes. At the same time, trade policy and export restrictions will remain a source of uncertainty, particularly for companies operating across multiple regions. These dynamics suggest that long-term competitiveness will depend as much on operational resilience as on product performance.
Probe Card Market
Actionable Guidance for Decision Makers
For probe card manufacturers, the priority is to align technology roadmaps with where device complexity is heading, not where it has already been. That means investing in architectures and process improvements suited to advanced logic, high-bandwidth memory, and heterogeneous packaging, while also building regional production options and diversified sourcing to protect lead times. Co-development relationships with key customers should be treated as strategic assets, because qualification timing and design-in access often matter more than incremental feature lists.
For investors, the market rewards players that combine credible advanced-node capability with operational resilience. Attention should be directed toward suppliers with strong qualification momentum, clear application focus, and evidence of capacity or technology moves that anticipate AI, memory, and advanced packaging demand. Concentration in the market is high, so differentiation, proprietary technology, and regional supply strategy are important indicators of durability.
For procurement and operations leaders, the commercial task is to reduce single-point dependency without sacrificing qualification rigor. Diversifying sources can improve resilience, but it must be paired with disciplined qualification, clear lead-time expectations, and close coordination with internal test roadmaps. As advanced package and high-bandwidth memory programs become more central, early engagement with test suppliers will help reduce schedule risk and avoid last-minute constraints.
Vertical Probe Cards Market
For decision makers seeking deeper segmentation, regional breakdowns, competitive tracking, and scenario-based insight, the full PW Consulting study on the worldwide probe cards market provides expanded detail and supporting analysis to inform planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Probe Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Polylaurolactam Market 2026–2032: Beyond the 5.6% CAGR Growth Trajectory
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Polylaurolactam Market
Market Overview and Core Challenges
Sizing the Opportunity
The global polylaurolactam market has demonstrated steady expansion over the past five years, with revenue scaling from approximately $1.12 billion in 2020 to $1.49 billion in 2025. Moving forward, the trajectory points toward a continuation of this upward trend, with projected revenues reaching $2.18 billion by 2032 at a compound annual growth rate of 5.6%. This growth is not merely a function of industrial expansion but reflects a structural shift in material preferences across several high-value sectors. The market's resilience stems from polylaurolactam's unique combination of chemical resistance, flexibility, and lightweighting capabilities, which make it indispensable in applications where traditional materials fall short. The consistent upward trajectory suggests that demand drivers are deeply embedded in end-user industries rather than being purely cyclical.
Three Critical Challenges Shaping the Landscape
Despite the positive growth outlook, the industry faces several structural headwinds that will define competitive positioning over the next five years. The first challenge lies in raw material volatility. Laurolactam, the primary monomer for polylaurolactam, depends on petrochemical feedstocks such as cyclododecane derived from butadiene. Fluctuations in butadiene pricing directly cascade into laurolactam and subsequent PA12 costs, creating margin pressure and pricing uncertainty. Recent data from late 2025 indicated weak to slightly declining price trends in both Asia and Europe, reflecting broader soft chemical market conditions and subdued feedstock demand. However, this softness does not eliminate structural volatility; rather, it underscores the market's sensitivity to upstream petrochemical cycles.
PW Consulting
The second challenge involves the growing emphasis on sustainability and bio-based alternatives. Automotive OEMs have set explicit targets for 20–30% sustainable polymer content by 2030, pressuring manufacturers to transition away from fully fossil-based PA12 grades. While bio-based variants exist, scaling production while maintaining cost parity remains a significant hurdle. The regulatory and commercial push toward greener materials is not a passing trend; it is becoming a prerequisite for supply chain access in certain regions and industries. Companies that fail to adapt their product portfolios to include certified sustainable grades risk marginalization as downstream customers tighten procurement criteria.
Polycaprolactone Market
The third challenge centers on geographic capacity expansion and its impact on pricing dynamics. China has been actively expanding laurolactam and Nylon 12 production capacity, which continues to influence regional pricing and competitive intensity in Asia. This capacity build-out introduces both opportunities for localized supply chain resilience and risks of oversupply in certain market segments. The interplay between new capacity coming online and the pace of demand absorption will determine whether the market experiences healthy growth or margin compression in the near term. Companies must navigate this balance carefully, as overcapacity in one region can quickly spill over into global pricing expectations.
Key Drivers Analysis
Technological Innovation and Performance Breakthroughs
Innovation in polymer compounding and processing continues to unlock new applications for polylaurolactam, extending its relevance beyond traditional segments. Advances in extrusion and injection molding grades have improved processability and reduced cycle times, making the material more attractive to manufacturers seeking efficiency gains. In additive manufacturing, the development of optimized powder grades has enabled finer resolution and improved mechanical properties in 3D-printed components. These technological refinements are not incremental; they are expanding the addressable market by lowering adoption barriers and enabling performance outcomes that were previously difficult to achieve. Manufacturers investing in tailored grade development are finding that performance differentiation translates directly into premium pricing opportunities and longer-term customer relationships.
Regulatory and Policy Pressures
Policy frameworks are increasingly shaping procurement decisions, particularly in the automotive and industrial sectors. The push for sustainable polymer content is not limited to voluntary commitments; it is being codified into supplier qualification requirements and internal procurement standards. Regulatory attention to carbon footprint disclosure and circular economy principles is also raising the compliance bar for polymer suppliers. Companies that proactively develop bio-based grades and establish transparent lifecycle assessments are positioning themselves advantageously. The regulatory environment creates a dual dynamic: it raises the cost of compliance for laggards while offering first-mover advantages to those who can meet sustainability targets without sacrificing performance or cost competitiveness. The timing of policy implementation matters, as early alignment with emerging standards reduces the risk of sudden supply chain disruptions.
Demand-Side Shifts in End-Use Industries
End-user industries are recalibrating their material choices based on performance, cost, and sustainability considerations. Automotive and transportation applications remain the largest demand driver, supported by lightweighting initiatives and the need for durable fuel lines, tubing, and under-the-hood components. Oil and gas applications continue to rely on PA12's chemical resistance for downhole and pipeline systems, though capital expenditure cycles in this sector introduce variability. Meanwhile, electronics and electrical applications are growing as miniaturization and thermal management requirements favor high-performance polymers. A particularly notable shift is the uptake of 3D printing and additive manufacturing, where polylaurolactam powders are gaining traction for prototyping and low-volume production runs. Medical and consumer goods applications, though smaller in absolute terms, benefit from PA12's biocompatibility and flexibility in specific formulations. The demand picture is becoming more diversified, reducing reliance on any single sector and creating multiple growth vectors.
Worldwide Lauryl Acrylate Market
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by feedstock dynamics, capacity geography, and production scale. The dependence on butadiene-derived cyclododecane means that laurolactam economics are tightly coupled to broader petrochemical markets. When butadiene prices are volatile, PA12 producers face difficult decisions around pricing, inventory management, and margin protection. At the same time, capacity expansions in Asia are altering the regional cost landscape, offering lower production costs in some areas but also intensifying competition. Integrated producers that control upstream feedstocks or operate at significant scale benefit from cost advantages and greater pricing flexibility. Conversely, smaller or more fragmented players may struggle to absorb volatility without eroding margins. The supply chain is also seeing increased attention to logistics and regional supply security, as customers seek to reduce exposure to long-distance dependencies and geopolitical disruptions.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market is highly concentrated, with a small group of global players commanding the majority of revenue. This concentration reflects the capital intensity of production, the technical expertise required for grade development, and the long-term supply relationships typical of high-performance polymer procurement. Leading producers have built their positions on a combination of scale, product breadth, and application-specific expertise. Evonik Industries AG anchors its strategy around large-scale PA12 production at its Marl Chemical Park, positioning itself as a reliable supplier for automotive, industrial, and 3D printing applications. Its sustainability-focused initiatives highlight efforts to align high-performance polymer production with evolving environmental expectations, reinforcing its appeal to customers prioritizing responsible sourcing. Arkema SA differentiates through its Rilsan PA12 portfolio, with particular emphasis on bio-based variants and specialty grades for tubing, fuel lines, and high-performance applications. This focus on sustainability-linked differentiation aligns directly with automotive OEM targets and positions Arkema as a strategic partner for customers navigating material transitions.
EMS-Chemie Holding AG has established a strong footprint through its Grilamid PA12 resins and compounds, targeting engineering applications across automotive, electronics, and industrial components. Its strategy emphasizes formulation flexibility and application support, enabling customers to optimize material performance for specific use cases. UBE Corporation supplies UBE Nylon 12 grades with a focus on precision molding and industrial uses, leveraging its Asia-Pacific production capabilities to serve regional demand efficiently. Its geographic positioning supports customers who prioritize responsive local supply and technical service. Wanhua Chemical operates as an integrated producer offering a full range of PA12 products for domestic and export markets. Its recent price increases of 5%–10% across its product range reflect a willingness to adjust pricing in response to market conditions and cost dynamics, signaling a more assertive commercial posture.
Market Structure Evolution
The competitive landscape is likely to evolve along multiple dimensions. Consolidation remains a plausible path as scale advantages become more pronounced and investment requirements for capacity and innovation grow. At the same time, differentiation is intensifying across product grades, sustainability credentials, and application support. New entrants face high barriers, but regional capacity additions, particularly in Asia, are altering the competitive balance by increasing supply options and pressuring pricing in certain segments. The market is not simply tightening around incumbents; it is becoming more stratified, with premium segments rewarding performance and sustainability innovation while commodity-adjacent segments face margin pressure. Companies that can navigate both dimensions—maintaining cost discipline while advancing differentiated offerings—are best positioned to capture value as the market matures. Strategic partnerships and vertical integration are also emerging as levers to secure feedstock access, improve cost predictability, and accelerate the development of sustainable grades.
Future Trends and Commercial Opportunities
Trend 1: Sustainability-Linked Product Segmentation
The market is moving toward clearer segmentation between conventional and sustainable PA12 grades. As automotive and industrial buyers embed sustainability targets into procurement, demand for bio-based and lower-carbon variants will grow even if these grades carry a premium. This creates an opportunity for producers to develop certified product lines, establish transparent lifecycle data, and secure long-term supply agreements with sustainability-conscious customers. The risk lies in the pace of cost reduction for bio-based production; if premiums remain high without clear value recognition from buyers, adoption may slow.
Trend 2: Additive Manufacturing as a Growth Accelerator
3D printing and additive manufacturing are expanding the use profile of polylaurolactam beyond traditional molding and extrusion. Powder-grade optimization, combined with growing adoption in prototyping, tooling, and low-volume production, offers a new demand channel that can be more responsive to innovation cycles than large-scale industrial procurement. Companies that invest in powder-grade development and application support for additive workflows can capture higher-margin segments and build relationships with users who may later scale into broader production applications. The uncertainty here relates to the pace of industrial adoption versus prototyping use; if additive applications remain primarily niche, the growth upside may be more limited than current enthusiasm suggests.
Trend 3: Regional Capacity Rebalancing and Pricing Dynamics
Asia's continued expansion in laurolactam and PA12 capacity will reshape regional supply and pricing dynamics. This can benefit customers seeking cost-effective supply and reduce dependency on distant sources, but it also introduces the possibility of localized oversupply and intensified competition. Producers outside Asia may need to emphasize service, technical support, and differentiated grades to maintain share, while Asian producers will need to balance capacity utilization with pricing discipline. For commercial players, this trend creates opportunities in regional supply chain optimization, import/export positioning, and strategic sourcing that accounts for shifting cost bases.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
- Accelerate the development and commercialization of bio-based and lower-carbon PA12 grades to align with automotive and industrial sustainability targets before regulatory and procurement pressures become more binding.
- Invest in grade-level differentiation for additive manufacturing and high-performance applications to capture premium segments and reduce exposure to commodity-like pricing pressure.
- Evaluate supply chain and feedstock strategies to improve cost predictability, including long-term supplier agreements, vertical integration where feasible, and regional production positioning that matches demand geography.
For Investors
- Prioritize companies with clear sustainability roadmaps and application-specific differentiation, as these traits are likely to command valuation support and customer loyalty in a market increasingly shaped by procurement criteria beyond price alone.
- Monitor capacity additions in Asia and their impact on regional pricing, as oversupply risk could compress margins for undifferentiated products while creating acquisition or partnership opportunities for well-positioned players.
- Assess exposure to additive manufacturing and high-growth application segments as potential upside drivers, but calibrate expectations against the pace of industrial adoption.
For Procurement and Supply Chain Leaders
- Diversify supplier bases to hedge against regional capacity shifts and feedstock volatility, while ensuring that alternative sources can meet performance and sustainability specifications.
- Engage suppliers early on bio-based and sustainable grade availability, securing visibility on timelines, certifications, and cost implications to avoid last-minute constraints as internal targets tighten.
- Build technical collaboration into procurement relationships, using application support and grade optimization to improve total cost of ownership rather than focusing solely on unit price.
Looking Ahead
The polylaurolactam market is at an inflection point where steady growth intersects with structural changes in sustainability expectations, application expansion, and regional capacity dynamics. For decision-makers, the imperative is to look beyond headline demand figures and understand how grade differentiation, feedstock volatility, and sustainability mandates will reshape competitive advantage. Detailed segmentation data, regional pricing analysis, and company-level benchmarking provide the granularity needed to translate these trends into actionable strategy. Readers interested in a comprehensive breakdown of market size by segment, competitive positioning, and customized scenario analysis can explore the full research report for deeper insights and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Polylaurolactam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Elastomeric Polyurethane Roof Coating: How 6.8% CAGR and Asia Pacific Growth Redefine Markets
By pmarketresearch, 2026-09-18
Worldwide Elastomeric Polyurethane Roof Coating Market: Strategic Trends and Commercial Opportunities
Market Overview & Core Challenges
The global elastomeric polyurethane roof coating market has solidified its position as a critical segment within the broader construction chemicals and waterproofing industry. Valued at approximately 1,025.4 million USD in 2025, the market reflects a compound annual growth rate of 6.8 percent across the forecast horizon extending to 2032. This trajectory underscores a steady, resilient expansion pattern, driven by the inherent performance advantages of elastomeric polyurethane systems, including exceptional flexibility, UV resistance, crack-bridging capabilities, and seamless application profiles. The historical growth from 745.2 million USD in 2020 to the current baseline demonstrates consistent demand absorption across developed and emerging construction ecosystems, while the projected climb toward 1,625.15 million USD by 2032 signals a maturing but still highly dynamic commercial landscape.
Despite the favorable macroeconomic tailwinds, the industry currently navigates several structural inflection points that demand strategic recalibration. First, raw material price volatility remains a persistent operational headwind. The polyurethane value chain relies heavily on methyldiphenyl diisocyanate (MDI) and polyol feedstocks, both of which are subject to periodic supply-demand imbalances, energy cost fluctuations, and geopolitical trade realignments. Recent pricing data indicates that MDI prices in the United States fell to 1,890 USD per metric ton in August 2025, marking a 13 percent month-over-month decline and a 19 percent year-over-year drop. While such declines temporarily ease input cost pressures, they often coincide with broader market uncertainty and can compress margins for formulators who have already locked in higher procurement costs. Conversely, early 2026 announcements from major chemical producers signaling price increases for MDI and polyols highlight how quickly cost structures can shift, leaving manufacturers and distributors vulnerable without robust hedging strategies or flexible formulation architectures.
Second, the regulatory environment around fluorinated compounds and volatile organic compounds (VOCs) continues to tighten, particularly in North America and Europe. The U.S. Environmental Protection Agency (EPA) has advanced its hydrofluorocarbon (HFC) phasedown agenda, implementing import prohibitions on certain products containing HFCs effective January 2025 under the AIM Act Technology Transitions Program. While HFC restrictions primarily target refrigerant-based applications, the broader regulatory momentum influences polyurethane formulation philosophies, pushing formulators toward low-VOC, solvent-free, and bio-based alternatives. Compliance with evolving VOC limits, particularly in states with stringent air quality mandates, requires sustained R&D investment and can temporarily disrupt traditional product roadmaps. Third, the market exhibits moderate concentration dynamics, with the top three players capturing roughly 38.45 percent of total revenue and the top five accounting for approximately 52.1 percent. This concentration reflects the technical barriers to entry, established specification networks, and long-standing contractor relationships that incumbents have cultivated. However, it also creates space for specialized challengers and regional specialists who can differentiate through niche performance claims, localized service models, or faster customization cycles.
These challenges are not insurmountable, but they do reframe the competitive calculus. Companies that treat raw material volatility as a purely reactive cost issue rather than a strategic sourcing and formulation opportunity risk lagging behind peers who build flexibility into their supply chains and portfolio architectures. Similarly, regulatory tightening is best viewed not as a compliance burden but as a catalyst for product modernization and market differentiation. The market's expansion to 1,625.15 million USD by 2032 will not be evenly distributed; it will accrue to organizations that can align product innovation, regulatory readiness, and supply chain resilience with the evolving requirements of specifiers, contractors, and building owners.
Key Growth Drivers
Technological Innovation and Formulation Advancements
The core performance proposition of elastomeric polyurethane roof coatings continues to be reinforced by targeted technological advances. Formulators are increasingly differentiating through aliphatic versus aromatic system architectures, moisture-cure versus two-component curing mechanisms, and the integration of UV-stable top coats that extend service life on exposed substrates. The shift toward low-odor, low-VOC, and solvent-free formulations addresses both regulatory pressure and on-site application preferences, particularly in urban retrofits where ventilation constraints and occupant sensitivity limit the use of high-solvent products. Product line expansions that pair aromatic base coats with aliphatic top coats exemplify a practical engineering approach: the base coat delivers adhesion, crack-bridging, and moisture tolerance, while the top coat provides long-term UV stability and color retention. Recent specification updates from industry participants illustrate how these technical nuances translate into commercial value. In mid-2025, a major coating manufacturer released updated restoration specification guidance for elastomeric polyurethane systems applied over ethylene propylene diene monomer (EPDM) membranes, reinforcing the role of compatible, high-performance top coats in extending the service life of existing roof assemblies. Shortly thereafter, the same company updated availability and specification details for its aromatic base coat and aliphatic top coat systems in standard pack sizes, signaling a focus on specification clarity and contractor accessibility. Such moves highlight how formulation precision, specification support, and packaging flexibility collectively strengthen market positioning.
Policy, Regulation, and Building Performance Mandates
Regulatory and policy environments are reshaping demand patterns by elevating the importance of durability, sustainability, and indoor air quality in roof restoration decisions. Building code updates, energy efficiency targets, and local air quality regulations are pushing specifiers toward coatings that minimize VOC emissions while maintaining elongation, tensile strength, and reflectivity over extended service intervals. The ongoing HFC phasedown and related technology transition initiatives may not directly govern elastomeric polyurethane coatings in all cases, but the regulatory trajectory reinforces a broader market expectation: building materials must demonstrate environmental responsibility without compromising performance. This expectation advantages formulators that can document low VOC content, reduced odor profiles, and compatibility with green roof assemblies or cool roof reflectance goals. Additionally, public infrastructure spending and municipal retrofit programs increasingly favor liquid-applied, seamless waterproofing systems that reduce leak pathways and minimize disruption during application. The alignment between regulatory direction and product capability creates a durable demand pull, particularly in regions where aging roof stock and stringent performance standards coincide.
Demand-Side Shifts in Commercial and Industrial Sectors
End-user behavior is evolving along two principal axes: lifecycle cost consciousness and maintenance minimization. Commercial building owners and facility managers are increasingly treating roof coatings as a capital-efficient alternative to full membrane replacement, especially where structural deck conditions remain sound and the primary failure modes involve surface degradation, seam fatigue, or minor cracking. Elastomeric polyurethane systems appeal in this context because they conform to substrate movement, bridge hairline cracks, and reduce the likelihood of water intrusion without the demolition and disposal costs associated with tear-off projects. In industrial facilities, heavy mechanical traffic, chemical exposure, and thermal cycling demand coatings that combine flexibility with abrasion resistance and chemical tolerance. The market's application mix reflects this reality, with commercial buildings representing the largest demand pool, followed by residential construction and industrial facilities. Residential demand is gaining traction as homeowners and multifamily property managers seek cost-effective weatherproofing solutions that extend roof service life and improve energy performance. Across these segments, the specification decision is increasingly influenced by total installed cost, downtime reduction, and long-term maintenance predictability rather than initial material price alone.
Supply Chain Dynamics and Cost Structure Evolution
The polyurethane feedstock landscape is undergoing a period of recalibration that will influence competitive positioning through the forecast period. Global MDI and TDI prices remained broadly stable through 2025, with a cautious outlook for stabilization in 2026 driven by supply-side adjustments. This stability provides a window for formulators to optimize formulation economics, lock in supplier agreements, and invest in alternative feedstock strategies without the urgency of acute price spikes. However, trade policy introduces a significant variable. The United States has imposed escalating tariffs on Chinese-origin MDI, starting at 30 percent and reaching 145 percent, with potential further antidumping duties under review through March 2026. These measures affect polyurethane feedstock costs and may restructure sourcing patterns, encouraging regional supply diversification, inventory buffering, and closer integration with non-affected feedstock sources. The interplay between feedstock price stabilization and tariff-driven cost pressure creates a bifurcated operating environment: companies with diversified supplier bases, transparent cost pass-through mechanisms, and agile formulation portfolios are better positioned to maintain margin integrity, while those reliant on single-source or tariff-exposed supply chains face greater exposure to cost shocks. This dynamic also elevates the strategic importance of bio-based polyols and alternative isocyanate pathways as medium-term levers for supply resilience and sustainability storytelling.
Competitive Landscape & Leading Strategies
The competitive architecture of the elastomeric polyurethane roof coating market is defined by a blend of multinational specialty chemical groups, focused regional manufacturers, and application-oriented solution providers. This mix produces a landscape where technical credibility, specification relationships, and service reliability often outweigh pure price competition. Several incumbent profiles illustrate the strategic diversity shaping the market.
Sika Corporation maintains a broad, globally integrated platform spanning liquid-applied roofing and waterproofing systems. Its product architecture includes single-component low-odor polyurethane roof coatings and two-component, fast-curing, solvent-free base coats designed for crack-bridging and elastomeric performance. Sika's strategic positioning rests on scale, specification depth, and the ability to offer compatible resin systems across multiple waterproofing platforms. This breadth supports large-scale commercial and infrastructure programs where consistent performance documentation, technical service, and supply reliability are critical differentiators. Polycoat Products has carved a focused position around polyurethane coatings and elastomer solutions for waterproofing, emphasizing UV resistance, durability, and waterproofing performance for roof and deck applications. Its strategy highlights specialization: by concentrating on elastomeric polyurethane membranes and coatings for demanding substrates, Polycoat builds reputation equity among contractors and specifiers who prioritize application-specific performance over broad portfolio breadth.
Inland Coatings, Inc. exemplifies a specification-driven, product-clarity approach. Its AldoThane series pairs aromatic base coats with aliphatic UV-stable top coats to deliver seamless, flexible waterproof membranes across diverse roof substrates. Recent activity underscores the importance of specification support and product availability: updated specifications for restoration over EPDM membranes and refreshed availability details for core product sizes demonstrate how incumbents reinforce market presence by reducing specification friction and ensuring reliable access to proven systems. Tremco Commercial Sealants & Waterproofing brings a complementary angle through one-part moisture-triggered polyurethane roof coatings and exploration of bio-based polyurethane options for reinforced liquid-applied roofing systems. This trajectory signals a dual emphasis on application convenience and sustainability-aligned innovation, appealing to project teams that value simplified application logistics alongside evolving environmental expectations.
Other participants deepen the market's regional and application-specific texture. Urethane Polymers International, Inc. focuses on elastomeric single-component systems engineered for low-slope roofing under heavy mechanical and pedestrian traffic, an area where abrasion resistance and recoatability are decisive. Karnak Corporation and Stockmeier Urethanes USA supply elastomeric polyurethane coatings that serve as practical, specification-friendly options for restoration and maintenance programs. American WeatherStar emphasizes high-solids, moisture-cure formulations primarily for sprayed polyurethane foam roofing protection and related commercial substrates, aligning product design with the specific thermal and protective needs of foam-based assemblies. In parallel, manufacturers such as Hebei Ruide Building Waterproof Material Co., Ltd. reflect the broader internationalization of supply capability, producing polyurethane roof coatings with an emphasis on durability and performance in elastomeric applications, which contributes to cost-competitive pressure and expanding option sets for price-sensitive markets.
The market's evolution is trending toward both consolidation of technical authority and fragmentation of niche advantage. On one hand, larger players with integrated R&D, global supply networks, and extensive specification libraries are well positioned to capture share in complex commercial and infrastructure programs. On the other hand, specialized manufacturers that deliver clear performance claims, rapid customization, and strong regional service can defend and expand their positions by reducing specification risk for contractors and building owners. New entrants and smaller formulators are most likely to succeed when they target underserved substrate types, specific climate durability requirements, or application formats that larger portfolios treat as secondary. The recent product and specification activity across several incumbents also suggests a market where clarity of use cases, compatibility documentation, and availability matter as much as raw performance metrics. Companies that streamline the path from specification to procurement to application will capture disproportionate value in a market where installation quality and long-term service life are central to customer satisfaction.
Future Outlook & Strategic Implications
Over the next three to five years, the elastomeric polyurethane roof coating market is likely to trend along three reinforcing directions. First, low-VOC, solvent-free, and bio-based formulation pathways will move from differentiating features to baseline expectations in many specification contexts. As regulatory momentum continues and contractor/occupant sensitivity to odor and emissions grows, formulators that can deliver strong elongation, adhesion, and UV stability within constrained VOC profiles will secure preferential positioning in commercial and institutional bids. This trend creates commercial opportunity for companies that invest early in formulation validation, performance documentation, and specifier education, particularly where green building programs and local air quality rules intersect.
PW Consulting
Second, supply chain reconfiguration will become a more explicit competitive lever. Tariff dynamics on certain MDI sources, combined with periodic feedstock price volatility, will encourage regional sourcing diversification, strategic inventory positioning, and closer collaboration with suppliers on forecasting and allocation. Organizations that build transparent cost-pass-through frameworks and maintain formulation flexibility will be better equipped to manage margin pressure without sacrificing specification credibility. This environment also elevates the value of alternative feedstock strategies, including bio-based polyols and regionally balanced supply mixes, both as cost-risk mitigation tools and as sustainability narrative enhancers.
Third, the restoration and maintenance segment will expand as a share of total demand, driven by aging roof stock, capital constraints, and the attractiveness of liquid-applied systems that avoid tear-off disruption. Elastomeric polyurethane coatings are well aligned with this shift because they accommodate substrate movement, bridge cracks, and extend service life with comparatively low installation intrusion. Commercial buildings will remain the dominant application pool, but industrial facilities and residential multifamily projects offer meaningful upside where durability, traffic resistance, and weatherproofing performance are prioritized. The opportunity lies in pairing product performance with specification support, compatibility guidance, and field service that reduces installation risk and protects long-term outcomes.
Potential risks and uncertainties deserve attention. Feedstock cost volatility can reemerge quickly, especially if energy markets shift or trade measures intensify, compressing margins for companies without flexible procurement or pricing strategies. Regulatory trajectories may accelerate in certain jurisdictions, creating uneven compliance burdens and requiring formulation agility across regions. Competitive intensity could increase if new entrants or imported supply press price points in price-sensitive segments, potentially eroding differentiation if incumbents rely too heavily on historical specification relationships. Finally, macroeconomic fluctuations in construction activity can affect the timing and scale of retrofit programs, making demand forecasting more variable. These uncertainties do not diminish the market's growth potential, but they reinforce the importance of scenario planning, supply resilience, and product-portfolio flexibility.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align formulation roadmaps with emerging specification expectations while building supply chain options that reduce exposure to feedstock and tariff shocks. Invest in low-VOC, solvent-free, and compatible base/top-coat system architectures, and pair product launches with clear compatibility documentation and specification support that reduces risk for contractors and specifiers. Diversify feedstock sourcing, evaluate alternative polyol and isocyanate pathways where feasible, and develop pricing mechanisms that preserve margin integrity during cost swings without undermining bid competitiveness.
Polyurea Coatings Market
For investors, focus on companies that demonstrate technical differentiation, specification momentum, and supply resilience rather than those competing primarily on price. Look for portfolios that combine proven elastomeric performance with clear regulatory readiness and application flexibility, and assess whether target companies have strong regional service capabilities and repeatable specification wins in commercial restoration and industrial maintenance. In a market projected to expand steadily through 2032, sustainable advantage will accrue to firms that can convert product performance into specification trust and installation reliability.
For procurement and asset owners, prioritize total lifecycle value over initial material cost. Evaluate coatings based on compatibility with existing substrates, UV stability, elongation and crack-bridging performance, VOC profile, and the quality of specification and field support available from the manufacturer. Where possible, consolidate product relationships with suppliers that can provide consistent performance documentation, clear application guidance, and reliable availability, reducing project risk and protecting long-term roof performance.
As the market evolves, detailed segmentation data, regional demand nuances, and customized strategic guidance become increasingly valuable for precise decision-making. PW Consulting's full research report provides deeper breakdowns and tailored recommendations for manufacturers, investors, and procurement teams seeking to navigate this dynamic landscape with confidence.
Roof Coating Market
For detailed analysis of this topic, please visit the official page: Worldwide Elastomeric Polyurethane Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Drivetrain Components Market: Why 20.48% CAGR Redefines the 2032 Outlook
By pmarketresearch, 2026-09-18
Worldwide Automotive Electric Drivetrain Components Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global market for automotive electric drivetrain components has entered a phase of aggressive expansion, driven by the electrification of passenger and commercial vehicle fleets. From 2020 to 2025, the sector compounded at a rapid pace, with revenue climbing from approximately $41.25 billion to $153.16 billion. The momentum does not show signs of abating; projections through 2032 indicate the market will surpass $564 billion, maintaining a compound annual growth rate of 20.48%. This trajectory suggests that electrification is no longer a niche segment but a dominant force reshaping the powertrain landscape. The scale of this growth implies a fundamental restructuring of supply chains, manufacturing capabilities, and product architecture across the automotive value chain.
Despite the robust headline numbers, the industry stands at a critical juncture defined by three key challenges. First, the supply chain for critical raw materials remains a vulnerability. The concentration of processing capacity for rare earth elements, such as neodymium required for permanent magnets in traction motors, poses significant geopolitical and operational risks. With China controlling a vast majority of global processing capacity as of 2025, manufacturers are exposed to potential export restrictions and price volatility. This dependency forces component suppliers to reconsider motor designs, exploring magnet-free alternatives or securing diversified sourcing agreements to mitigate disruption.
Second, the regulatory environment is evolving from simple electrification mandates to complex performance standards. Recent updates, such as the EU's Automotive Package revised in December 2025, introduce flexibility mechanisms for emissions averaging between 2025 and 2027 but maintain a strict 90% tailpipe emissions reduction target from 2035. Furthermore, Euro 7 regulations now introduce brake and tyre particulate emission limits alongside battery durability requirements. These rules directly impact electric drivetrain design, necessitating components that not only deliver power efficiently but also manage particulate matter and endure longer lifecycles. Compliance is no longer just about selling an electric vehicle; it is about engineering every component to meet rigorous environmental and durability standards.
Third, cost structures are under pressure due to material price volatility and technology investment requirements. While lithium prices have corrected significantly from 2023 peaks, other materials like cobalt and nickel remain volatile, and copper demand is rising with electrification but faces supply constraints. Simultaneously, the adoption of silicon carbide (SiC) semiconductors in inverters improves efficiency but comes with high production costs and supply vulnerabilities. Balancing the need for high-performance, efficient components with the imperative to reduce bill-of-materials costs is a central tension for original equipment manufacturers and tier-one suppliers alike.
Key Drivers of Market Dynamics
Several interconnected factors are propelling the electric drivetrain components market forward, transforming it from a regulatory compliance exercise into a core competitive battleground.
Technological Innovation and Efficiency Gains
Innovation is the primary engine of growth, specifically in power electronics and motor integration. The shift toward silicon carbide (SiC) semiconductors in inverters represents a significant technological leap. SiC devices offer higher efficiency and thermal performance compared to traditional silicon-based components, allowing for smaller, lighter inverters that extend vehicle range. However, the high cost and supply constraints of SiC mean that adoption is currently focused on premium and high-volume models where range anxiety is a critical purchase barrier. Manufacturers who can secure stable SiC supply or develop cost-effective alternatives gain a distinct advantage in the high-efficiency segment.
Motor technology is also seeing diversification. While permanent magnet motors dominate due to their power density, the supply risks associated with rare earth elements are driving interest in magnet-free solutions. Companies are developing high-performance electric motors that do not rely on neodymium or dysprosium, reducing exposure to raw material bottlenecks. Additionally, integration trends are accelerating. The move toward e-axle systems and 7-in-1 integrated drive units consolidates multiple components into a single compact package. This integration simplifies assembly, reduces weight, and lowers costs, making it particularly attractive for mass-market electrification.
Policy and Regulatory Environment
Government policies continue to be a powerful catalyst. Beyond the EU's tightened CO2 standards and Euro 7 requirements, regions worldwide are implementing incentives and mandates that accelerate EV adoption. The EU's flexibility for 2025-2027 averaging provides manufacturers a temporary buffer, but the long-term trajectory remains strict. This regulatory certainty encourages investment in dedicated electric drivetrain production lines. Furthermore, regulations regarding battery durability and recyclability are pushing component suppliers to design for longevity and serviceability. The focus is shifting from just initial performance to the entire lifecycle of the drivetrain, influencing how inverters, motors, and thermal management systems are engineered and validated.
Demand-Side Shifts and Vehicle Segmentation
Consumer and corporate behavior is reshaping demand patterns. Battery Electric Vehicles (BEVs) continue to capture the largest share of the electrification market, driven by expanding model availability and improving charging infrastructure. However, Plug-in Hybrid Electric Vehicles (PHEVs) remain relevant, particularly in segments where charging access is limited or for commercial fleets requiring flexible range. This dual demand means component suppliers must cater to both pure electric and hybrid architectures. The rise of premium EVs also demands higher performance specifications, such as 800V architectures, which require robust high-voltage components like advanced onboard chargers and DC-DC converters. Manufacturers like InfiMotion are targeting these premium segments with specialized 800V drivetrains, demonstrating that high-performance electrification is a viable growth niche alongside mass-market solutions.
Supply Chain and Cost Structure Evolution
The supply chain is undergoing a structural transformation. The volatility in lithium, cobalt, and nickel prices highlights the need for strategic procurement and hedging strategies. As copper demand rises with electrification, supply constraints could become a bottleneck, prompting investment in recycling and alternative materials. Additionally, the geographic concentration of processing for critical minerals is pushing manufacturers to localize supply chains or form strategic partnerships to secure access. Cost efficiency is no longer just about labor arbitrage; it is about securing raw materials, optimizing component design for manufacturability, and leveraging scale. Companies that can navigate these supply chain complexities while maintaining quality and cost competitiveness will define the market leadership of the next decade.
Competitive Landscape and Leadership Strategies
The competitive arena for electric drivetrain components is characterized by a mix of established automotive suppliers and specialized technology firms. The market shows notable concentration, with the top three players holding a significant share, while the top five extend their reach further. This concentration suggests that scale, technological capability, and long-term customer relationships are critical barriers to entry. Major players are leveraging their existing manufacturing bases and engineering expertise to capture value across the electrification transition.
Leading companies are pursuing distinct strategic positions. German automotive supply giants such as Robert Bosch, ZF, and Continental are focusing on integrated solutions. ZF, for instance, is advancing its SELECT modular electric drive platform and AxTrax 2 electric portal axle, complemented by TherMaS thermal management systems that enhance EV range. Recent showcase activities highlight ZF's push into modular electric drive systems for city and intercity buses, utilizing SiC inverters and three-speed transmissions. This modular approach allows flexibility across vehicle types, from passenger cars to commercial transport. Bosch continues to supply comprehensive electric drivetrain transmissions, silicon carbide power electronics, and inverters, leveraging its broad portfolio to serve both passenger and commercial vehicles. Continental delivers electric powertrain components including motors and inverters as part of a broader electrification portfolio, emphasizing integration and system-level optimization.
Automotive Parts and Components Market
American and Canadian players are also making significant moves. Magna International provides EtelligentDrive BEV powertrain systems and eDrive units across various power levels, catering to AWD EVs and hybrids. Their 2025 annual report highlights continued supply of primary and secondary electric drive systems, underscoring their role as a key tier-one partner. BorgWarner is supplying high-voltage electric motors and 800V onboard chargers/DC-DC converters with SiC semiconductors, positioning itself in the high-voltage architecture segment. Dana Incorporated focuses on e-axles and electrified drivetrain solutions for commercial and passenger vehicles, leveraging its driveline heritage.
Worldwide Rail Components Market
Japanese and Korean manufacturers are strong contenders, particularly in motors and e-axles. Nidec is pushing the boundaries with 3rd and 4th-generation E-Axle systems, including 7-in-1 integrated units and magnet-free high-performance E-Axles. Exhibitions of these technologies demonstrate Nidec's commitment to innovation and mass production readiness. Denso and Aisin offer electrification systems including motors, inverters, and e-axles optimized for EVs and hybrids. Hitachi Astemo supplies electric motors, inverters, and complete powertrain systems, while Hyundai Mobis manufactures integrated electric drive systems and e-axles for 400V/800V platforms, backing the growing Korean EV ecosystem.
European specialists like Valeo and Schaeffler are carving niches based on specific technologies. Valeo develops compact e-drive systems and magnet-free electric motors in partnership with MAHLE, alongside regenerative braking technologies. This focus on magnet-free solutions and braking integration addresses both material supply concerns and regulatory requirements for particulate emissions. Schaeffler provides e-motors, power electronics, and integrated e-axles through its E-Mobility division, complementing traditional bearing and transmission expertise with electrification capabilities.
New entrants and specialized firms are also disrupting the landscape. InfiMotion Technology, with operations in China and Sweden, develops 800V L700 PMSM electric drivetrains and gearboxes for premium EVs. Partnerships with global premium manufacturers to deliver high-horsepower drivetrains for new models illustrate how specialized suppliers can capture high-value segments. GKN Automotive provides e-axles and torque vectoring systems, adding performance differentiation to electrified drivelines.
The market is evolving through both consolidation and differentiation. Integrated platforms are becoming the norm, as suppliers seek to offer complete drive units rather than individual components. This trend favors players with broad portfolios and the ability to co-engineer with OEMs. At the same time, differentiation is emerging in areas like SiC adoption, magnet-free motors, thermal management, and high-voltage architectures. Companies that can balance scale with technological specialization will be best positioned to navigate the shifting competitive dynamics.
Future Trends and Outlook
Looking ahead to the next three to five years, several trends are poised to shape the electric drivetrain components market.
First, the adoption of integrated and modular architectures will accelerate. As OEMs seek to simplify vehicle assembly and reduce costs, demand for e-axles and multi-component integrated drive units will grow. Suppliers that can offer scalable modular platforms, adaptable to different vehicle sizes and performance requirements, will capture significant market share. The trend toward modularity is evident in recent product showcases featuring systems for both city buses and passenger vehicles, highlighting the versatility required in modern drivetrain solutions.
Second, material innovation and supply chain resilience will become strategic imperatives. The push for magnet-free motors and the challenges associated with SiC supply will drive investment in alternative materials and manufacturing processes. Companies that develop robust strategies for rare earth independence or secure long-term SiC supply agreements will mitigate risk and potentially gain cost advantages. Recycling and circular economy initiatives may also gain traction as regulations tighten around battery durability and material traceability.
Third, the regulatory focus on holistic vehicle performance will influence component design. Euro 7 and similar regulations worldwide will require drivetrain components to contribute to lower particulate emissions and longer durability. This may lead to innovations in regenerative braking, thermal management, and motor control algorithms that optimize efficiency and wear. Suppliers that anticipate these requirements and design components accordingly will offer added value to OEMs navigating compliance.
Commercial opportunities lie in serving the expanding BEV market, the persistent demand for PHEV components, and the high-performance premium segment. However, risks remain. Raw material price volatility, geopolitical tensions affecting supply chains, and the pace of regulatory changes could impact margins and demand forecasts. Additionally, the competitive intensity may lead to price pressure, especially in commoditizing segments. Success will depend on agility, technological leadership, and the ability to forge strategic partnerships across the value chain.
Strategic Recommendations for Decision Makers
For manufacturers and suppliers, prioritizing technological differentiation is essential. Investing in SiC capabilities, magnet-free motor designs, or advanced thermal management systems can create competitive moats. Simultaneously, securing supply chain resilience through diversified sourcing, long-term contracts, or vertical integration in critical materials should be a strategic priority. Modular platform development can also provide flexibility to serve multiple vehicle segments efficiently.
Investors should focus on companies with strong IP portfolios, scalable manufacturing capabilities, and exposure to high-growth segments such as 800V architectures and commercial EV drivetrains. Monitoring regulatory developments and raw material trends is crucial for assessing risk and opportunity. Companies that demonstrate progress in cost reduction while maintaining performance standards are likely to deliver sustainable value.
Procurement and OEM strategists should engage early with suppliers to co-develop solutions that meet upcoming regulatory requirements, such as Euro 7 particulate limits and battery durability standards. Diversifying the supplier base for critical components like inverters and motors can mitigate supply risks. Evaluating suppliers based on their ability to provide integrated solutions and support lifecycle requirements will help optimize total cost of ownership.
Detailed segmentation data, regional breakdowns, and customized scenario analysis are available in comprehensive research reports that provide deeper granularity on market dynamics, competitive positioning, and forward-looking indicators. Access to such detailed intelligence enables stakeholders to refine strategies, identify niche opportunities, and navigate the complexities of the electric drivetrain components market with confidence.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Electric Drivetrain Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Chip Probing Market: Why Automation Tools Are Reshaping Growth
By pmarketresearch, 2026-09-18
Navigating the Next Wave: Strategic Insights into the Worldwide Chip Probing Market
The worldwide chip probing market has entered a decisive phase of expansion, defined by surging test complexity and a structural shift toward higher parallelism. Valued at approximately $4.65 billion in 2025, the market has grown from $2.84 billion in 2020, reflecting a compound annual growth rate of 9.21 percent through 2032, when it is projected to approach $8.6 billion. This trajectory is not merely a function of volume; it signals a fundamental recalibration of how semiconductors are validated at the wafer level. As device architectures fracture into heterogeneous integration, chiplets, and advanced memory stacks, probing has moved from a supporting test step to a critical yield-enabling bottleneck. The base-year momentum underscores that capital is flowing into test infrastructure at a pace that outstrips historical norms, yet the expansion is unevenly distributed across technology nodes and application segments.
Beneath the headline growth, the industry confronts three interlocking challenges that will shape competitive outcomes over the next three years. First, sub-5 nanometer design complexity has slowed the introduction of new probe card architectures, with roughly one in four new designs encountering development delays as pin counts, signal integrity requirements, and thermal constraints intensify. Second, geopolitical export controls have introduced new friction into equipment flows. Refinements to the U.S. Foreign-Produced Direct Product Rule now capture certain wafer probing equipment with positioning accuracy finer than 3.5 micrometers for advanced computing applications, forcing suppliers and buyers to reconfigure supply chains and qualification pathways. Third, the economics of high-precision probing remain punishing. Fine-pitch probe cards can exceed $80,000 per unit in materials and precision assembly costs, while nearly two in five wafer test probe cards in recent years have incorporated advanced tungsten and nickel alloys to sustain durability under repeated contact cycles. These cost and complexity pressures are compressing margins for incumbents and raising the barrier for new entrants, even as demand accelerates.
The result is a market that rewards technological agility, vertical integration, and early alignment with advanced packaging and high-bandwidth memory roadmaps. Growth is no longer driven by uniform volume increases; it is being pulled by a subset of high-value applications that demand higher parallelism, lower contact resistance, and specialized RF or photonic test capabilities. Companies that can reconcile cost discipline with rapid design iteration will capture disproportionate share as the market scales toward the end of the decade.
Key Drivers Reshaping the Market
Technological Innovation and the Parallelism Imperative
The most consequential driver is the technical escalation of wafer-level testing requirements. Modern logic and system-on-chip devices, alongside high-bandwidth memory stacks, are pushing probe cards toward higher contact densities, finer pitches, and multi-site test configurations that maximize throughput. MEMS-based probe architectures and vertical probe designs have emerged as enabling technologies for these workloads, offering improved mechanical stability and better alignment with advanced node geometries. At the same time, test content is expanding beyond traditional DC and analog verification to include RF, mmWave, cryogenic, and silicon photonics characterization. This broadening test envelope is reshaping product roadmaps, as suppliers invest in specialized probe heads and integrated test systems that can address co-packaged optics and heterogeneous die-to-die interfaces. The practical effect is a market where performance differentiation increasingly hinges on the ability to deliver high-parallelism solutions without sacrificing yield or signal integrity.
Policy, Export Controls, and Infrastructure Acceleration
Policy dynamics are reshaping both the pace and geography of deployment. On one side, export control refinements have added complexity to equipment sourcing for advanced computing workloads, particularly where positioning accuracy and application context intersect with controlled thresholds. These rules do not halt demand, but they compel manufacturers to diversify supply, accelerate Qualification timelines, and in some cases re-architect test cells to remain compliant while preserving performance. On the other side, domestic semiconductor incentives are compressing time-to-production for new fab lines. Grant programs associated with national chip initiatives have helped accelerate probe card qualification for new facilities, shortening the window between process bring-up and volume test readiness. This dual force—more restrictive cross-border equipment flows paired with faster domestic fab ramp schedules—creates a distinct operating environment in which suppliers with localized manufacturing, flexible qualification processes, and broad technology portfolios gain strategic leverage.
Demand-Side Shifts: AI, HBM, and High-Performance Computing
Demand is being reconfigured by the rapid scaling of artificial intelligence accelerators, high-bandwidth memory, and high-performance computing platforms. These applications impose unusually stringent test requirements, including high contact density for multi-die validation, high-frequency signal fidelity for RF paths, and specialized handling for advanced packaging configurations. Lead-time signals already reflect this pressure: major probe card suppliers have reported extended delivery timelines, with some probe card lead times stretching to roughly six months as AI-related demand absorbs available capacity. Record financial results at several leading suppliers underscore the breadth of this demand surge, while also highlighting capacity as a binding constraint. The strategic implication is that demand is being shaped not just by unit volume but by test intensity—each advanced device now requires more probing content per wafer, amplifying the value of high-throughput, high-reliability probe solutions.
Supply Chain and Cost Structure Realities
Cost structure and material availability form the fourth pillar of change. Fine-pitch probe card production demands precision assembly and specialized alloys, pushing per-unit costs into a range that rewards scale and process maturity. The widespread use of advanced tungsten and nickel alloys in recent years reflects an industry-wide push to improve contact durability and reduce downstream yield loss, but it also ties supplier economics to material sourcing and manufacturing precision. Meanwhile, strategic partnerships and selective investments are beginning to reshape the supply base. Collaborations between test equipment producers and probe card specialists have deepened, combining complementary strengths in instrumentation, printed circuit board design, and probe technology. These alliances are accelerating development cycles and distributing risk in a market where design complexity and capacity constraints can otherwise slow responsiveness. The net effect is a supply environment in which cost discipline, material reliability, and partnership ecosystems are becoming as important as raw engineering talent.
Competitive Landscape and Leading Strategies
The competitive structure of the chip probing market is concentrated and capability-driven. The top three suppliers command a combined share in the high-sixy percent range, and the top five approach the low-eighties, reflecting the advantages of scale, established foundry and OSAT relationships, and deep application-specific engineering. Yet concentration has not translated into uniformity. Leaders are differentiating along technology axes—MEMS and vertical probe architectures, RF and photonics test readiness, cryogenic capability, and advanced packaging support—while also expanding through targeted acquisitions, capacity investments, and long-term supply agreements. The field is broad enough to accommodate specialized players in memory, logic, RF, and photonics, but the center of gravity is shifting toward suppliers that can address multiple high-growth segments without diluting technical focus.
PW Consulting
FormFactor exemplifies the integrated, high-parallelism strategy. Headquartered in Livermore, California, the company has built a portfolio around advanced wafer probe cards, including MEMS-based solutions for high-parallelism SoC, HBM, DRAM, and logic testing, alongside systems for RF, cryogenic, and silicon photonics probing. Its recent activity shows a deliberate push into capacity, partnerships, and adjacent technology domains. A new manufacturing facility in Farmers Branch, Texas, was acquired to support increased probe card demand driven by advanced packaging and HBM. In parallel, the company expanded its MeasureOne Partner Program with Rohde & Schwarz to advance on-wafer RF component characterization, and it was recognized with a 2026 Intel EPIC Supplier Award. On the inorganic side, the acquisition of Keystone Photonics extended silicon photonics and co-packaged optics wafer test capabilities. A strategic partnership with Advantest, involving minority investment and technology and PCB collaboration, further signals a preference for ecosystem alignment in probe card development. Taken together, these moves reflect a strategy that blends scale, specialized test content, and partnership-driven innovation.
Technoprobe, based in Cernusco Lombardone, Italy, competes through precision probe card design and a strong emphasis on vertical and MEMS technologies for high-volume wafer-level testing across logic, memory, and advanced packaging. Its recent supply agreement— a five-year commitment with WinWay Technology and MS SUN for MEMS probe cards based on Technoprobe’s proprietary TPEG technology—illustrates a strategy of locking in demand while extending technology reach through partners. This long-term contracting approach helps stabilize utilization and funds continued investment in high-parallelism and advanced node test solutions. MPI Corporation, headquartered in Hsinchu, Taiwan, has positioned itself around advanced probe card technologies and one-stop wafer sort test solutions, including TITAN RF probes spanning DC to 250 GHz and high-performance cards for RF, mmWave, photonics, and AI/HPC semiconductor testing. Its demand signal is notable: probe card lead times have stretched to six months amid strong AI chip demand, even as the company reported record 2025 revenue and profit alongside capacity expansion plans. MPI’s profile highlights how RF and mmWave competencies are becoming a differentiator as test content diversifies.
The regional dimension of competition is equally important. Micronics Japan and Japan Electronic Materials bring high-precision probe card expertise and close foundry collaborations, with strengths in advanced node testing, DRAM, Flash, and logic applications, as well as high-frequency materials and precision engineering. European participation remains meaningful through Feinmetall’s focus on contact probes and fine-pitch, high-reliability probe cards. In Asia, a dense cohort of suppliers—including SV Probe in Singapore, TSE and Korea Instrument in South Korea, and a cluster of Taiwanese and Korean specialists such as CHPT, WinWay Technology, Nidec SV TCL, Microfriend, STAr Technologies, and Wentworth Laboratories in the United States—demonstrates how regional manufacturing footprints and foundry relationships continue to shape access and responsiveness. This multifaceted landscape suggests two concurrent trends: consolidation among the most capable, multi-segment players, and sustained differentiation among specialists who can meet the exacting requirements of memory, RF, photonics, or advanced packaging niches. New entrants face a high bar, not only because of cost and precision demands, but because qualification cycles and customer integration depth favor incumbents with proven track records.
Probe Card Market
Future Trends and Commercial Opportunities
Looking toward 2030 and beyond, three trends are likely to define the market’s evolution. The first is the normalization of high-parallelism probing as a baseline requirement rather than a premium option. As chiplet-based designs, advanced packaging, and high-bandwidth memory become more pervasive, test cells will increasingly rely on multi-site configurations and vertical probe architectures that can address dense interface arrays with consistent contact performance. Suppliers that standardize high-parallelism platforms while retaining flexibility for application-specific variants will be best positioned to capture recurring demand and shorten qualification cycles for new device families.
Worldwide Probe Cards Market
The second trend is the convergence of probe cards with broader test ecosystems. RF, mmWave, cryogenic, and photonics test capabilities are moving from specialty add-ons to core considerations for a growing set of applications. This convergence opens commercial opportunities for integrated solutions that combine probe hardware, instrumentation alignment, and software-driven calibration, reducing the integration burden on device makers and test houses. It also favors suppliers that can orchestrate partnerships across the test chain, ensuring that wafer-level characterization keeps pace with device complexity without fragmenting accountability across too many vendors.
The third trend is geopolitical and operational decentralization. Export rule refinements and regional incentive programs are encouraging more localized qualification, manufacturing, and supply redundancy. For commercial players, this creates opportunities to build or strengthen regional capacity, align with domestic fab and packaging roadmaps, and offer predictable lead times in environments where supply assurance is becoming a competitive differentiator. The associated risk is that regulatory scope may continue to evolve, particularly around controlled accuracy thresholds and advanced computing end uses, requiring agile compliance strategies and flexible product configurations. Design complexity for leading-edge nodes will remain a persistent source of delay risk, and material cost volatility can pressure margins if not offset by scale or value-based pricing. Companies that treat these uncertainties as design inputs—by diversifying supply, modularizing probe architectures, and investing in early co-development with customers—will convert risk into durable advantage.
Strategic Actions for Decision-Makers
For probe card manufacturers and test equipment suppliers, the priority is to align capacity expansion with the highest-value demand nodes while preserving technology breadth. Investing in high-parallelism platforms, RF and photonics readiness, and advanced packaging test content should be paired with long-term supply agreements and selective partnerships that stabilize utilization and shorten development cycles. Localized manufacturing and qualification agility will increasingly matter as customers seek predictable lead times and regulatory resilience. Differentiation will come less from generic scale than from the ability to deliver repeatable performance across demanding applications while controlling per-unit cost through process maturity and material strategy.
For investors, the market’s growth is real, but share gains will be uneven. The most compelling opportunities lie with suppliers that demonstrate multi-segment capability, especially where MEMS, vertical probe, RF, and photonics competencies intersect with AI/HPC and HBM roadmaps. Monitoring lead-time signals, capacity announcements, and partnership or acquisition activity provides early indication of which players are converting demand into durable positioning. Valuation should account for the capital intensity of precision assembly, the importance of alkalinity in materials sourcing, and the potential for consolidation among mid-tier specialists who lack the breadth to compete across logic, memory, and advanced packaging.
For procurement and test strategy leaders, the practical imperative is to reduce integration risk while preserving optionality. Prioritize suppliers with proven qualification depth and the ability to support multiple test modalities, and structure agreements to balance volume commitments with flexibility for evolving device architectures. Engaging earlier in the design cycle—aligning probe card selection with packaging, interface, and test content decisions—can compress qualification timelines and mitigate the delays associated with leading-edge node complexity. Building redundancy into the supplier base, where feasible, helps manage exposure to export control shifts and capacity constraints without sacrificing performance.
The chip probing market is being reshaped by the simultaneous pull of advanced device complexity, policy-driven supply reconfiguration, and demand intensity from AI and high-performance computing. Navigating this environment requires more than broad market data; it demands segment-level visibility into technology roadmaps, supplier capabilities, and the contractual and regulatory dynamics that determine who captures value as the market scales. For decision-makers seeking granular segmentation, regional demand patterns, and tailored strategic recommendations, the full PW Consulting study provides the detailed evidence base and scenario analysis needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Worldwide Chip Probing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Insulated Cup Sleeves Market: Why the 5.76% CAGR Tells a Deeper Resilience Story
By pmarketresearch, 2026-09-18
The Worldwide Insulated Cup Sleeves Market: Strategic Trends and Commercial Opportunities Through 2032
The global insulated cup sleeves market has evolved from a peripheral accessory into a strategically significant segment within the broader foodservice packaging ecosystem. Valued at USD 1,458.6 million in 2025 and projected to expand at a compound annual growth rate of 5.76 percent through 2032, the market reflects a structural shift in how hot and cold beverages are packaged, delivered, and perceived by end users. Historical revenue progression from 2020 through 2025 demonstrates consistent upward momentum, with the segment crossing the 1,400 million threshold in 2024 before accelerating into the mid-1,500 million range in 2026. The trajectory continues upward through the forecast horizon, surpassing 2,150 million by 2032, signaling sustained commercial relevance beyond short-term consumer fads.
This growth is not merely a function of volume expansion. It represents a convergence of regulatory pressure, sustainability mandates, material innovation, and shifting handling expectations across both commercial and residential channels. Insulated cup sleeves now serve dual purposes: thermal protection and brand communication, while increasingly operating as a compliance touchpoint in jurisdictions tightening rules around single-use packaging. For executives and investors, the market offers a window into how disposable food accessories are being redesigned to align with circular economy principles without sacrificing cost efficiency or user experience.
Despite the favorable trajectory, the industry faces several structural challenges that will define competitive outcomes over the next cycle. First, the transition toward higher recycled content and alternative fiber sources introduces variability in supply consistency, pricing, and performance characteristics. Manufacturers must balance sustainability targets with the physical requirements of thermal insulation, print fidelity, and stackability. Second, regulatory frameworks across Europe, North America, and parts of Asia are increasingly tying compliance costs to recyclability metrics and post-consumer content thresholds, reshaping procurement economics and pushing smaller producers into difficult positioning decisions. Third, the market remains moderately fragmented, with concentration levels indicating room for consolidation but also leaving space for niche players who can differentiate through material science, custom engineering, or regional service models. Navigating these dynamics requires more than volume scaling; it demands strategic clarity around material selection, compliance readiness, and end-user value propositions.
Key Drivers Reshaping the Insulated Cup Sleeves Market
Material Innovation and Thermal Performance Engineering
Material selection has moved from a cost-centric decision to a performance and compliance-driven strategic lever. Kraft paper and corrugated paperboard, whether sourced from virgin or post-consumer recycled fiber, continue to anchor the segment due to their balance of cost efficiency, printability, and consumer familiarity. However, manufacturers are increasingly deploying embossed architectures, textured surfaces, and engineered air-trapping geometries to enhance insulation without simply adding material weight. Embossed fiber formats, for instance, allow producers to reduce basis weight while maintaining thermal resistance, creating a direct link between design innovation and margin preservation. Water-based and polylactic acid coatings are also gaining traction as alternatives to conventional barriers, particularly where compostability or recyclability claims must be substantiated. These developments are not incremental; they are redefining the cost-performance envelope and enabling sleeve solutions that align with both handling expectations and end-of-life requirements.
Regulatory Pressure and Extended Producer Responsibility
Policy momentum is reshaping procurement behavior across multiple regions. The EU Single-Use Plastics Directive and associated Extended Producer Responsibility schemes now encompass single-use packaging items, including paper-based beverage accessories, requiring producers to finance collection and recycling infrastructure. In the United Kingdom, the expanding EPR framework for packaging introduces fees structured around recyclability and recycled content, directly influencing the economics of disposable sleeves. Similar dynamics are emerging in California through SB 54, which establishes extended producer responsibility for packaging and is steering foodservice procurement toward recyclable fiber-based formats. These regimes do not merely impose compliance costs; they alter the relative attractiveness of material choices, reward higher recycled fractions, and penalize designs that complicate recovery streams. Companies that anticipate these requirements in product architecture and sourcing strategies can convert regulatory pressure into a procurement advantage rather than a reactive expense.
Demand-Side Shifts Among Consumers and Commercial Buyers
End-user expectations are increasingly shaping sleeve design and specification. Coffee shops and cafes remain the dominant commercial channel, where sleeves function as both thermal protection and a canvas for branding, making printability, consistency, and fit critical. Household consumers represent a growing segment, driven by at-home beverage preparation, reusable cup ecosystems that still require disposable protection in certain contexts, and heightened sensitivity to tactile comfort and environmental claims. Corporate and institutional buyers add another layer of complexity, as procurement teams evaluate total cost of ownership, compliance alignment, and visibility into material provenance. Across these channels, the common thread is a demand for sleeves that perform reliably, communicate sustainability credibly, and integrate smoothly into existing cup formats without introducing friction in high-volume environments.
Supply Chain Reconfiguration and Cost Structure Dynamics
The cost structure of insulated cup sleeves is being recalibrated by fiber availability, recycled content sourcing, energy inputs, and regional manufacturing footprints. As producers increase reliance on post-consumer recycled fiber, they must manage variability in pulp quality, contamination risk, and processing requirements. At the same time, the push toward fossil-free production and lower carbon intensity is influencing facility investments and logistics decisions. Some manufacturers are positioning around localized production to reduce transport emissions and respond faster to regional compliance mandates, while others are scaling centralized capacity to optimize material purchasing and technical development. These contrasting models reflect a broader divergence in how companies are managing the trade-off between agility and scale, with implications for pricing stability and service levels across customer segments.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established packaging groups, specialized fiber innovators, and regionally focused producers. Leadership is increasingly defined not by volume alone but by the ability to align material science, sustainability credentials, and application-specific engineering. Several companies have built differentiation around distinct value propositions that illustrate where the market is heading.
One major player has expanded its portfolio around hot cup sleeves designed as accessories for single-wall paper cups, while also advancing insulated cup formats that incorporate a built-in thermal effect, reducing the need for separate sleeves in certain applications. Its emphasis on post-consumer recycled fiber and recognized forestry standards positions it at the intersection of performance and responsible sourcing. Another leading supplier has focused on deeply embossed fiber formats engineered for superior thermal insulation with reduced material consumption, emphasizing printability and a high degree of fossil-free production. This approach illustrates how design-led material use can simultaneously address cost, performance, and environmental targets. A China-based manufacturer has concentrated on custom recyclable paper sleeves compatible across common cup sizes, offering corrugated or textured designs that protect against heat or cold transfer while supporting custom printing and recycled fiber options. This model highlights the importance of application flexibility and regional customization in capturing demand across diverse foodservice configurations.
Worldwide Paper Cup Sleeve Market
Several companies have carved out strong positions in compostable and recycled-content sleeves, targeting operators and institutional buyers seeking credible end-of-life claims. One U.S.-based producer offers sleeves made from recycled paper content that are fully compostable and designed for comfortable handling across a range of cup sizes. Another focuses on sleeves made entirely from post-consumer recycled paper, aligned with sustainable foodservice applications. A Finnish manufacturer adds a premium kraft sleeve offering and insulated paper cup designs that integrate insulation into the cup itself, reducing dependence on separate sleeves in premium segments. Meanwhile, a global packaging group has advanced recyclable sleeve solutions with high post-consumer recycled content, reinforcing a circular packaging narrative across beverage applications. These varied strategies show that differentiation is increasingly multidimensional, spanning material composition, end-of-life pathway, thermal engineering, and brand trust.
Recent recognitions underscore how sustainability and performance are converging in corporate positioning. One global supplier received an industry award for a stretch sleeve solution containing up to 75 percent post-consumer recycled material and associated with significantly lower CO₂ emissions, supporting circular packaging in beverage sectors. The same company was later named Packaging Company of the Year at a major UK awards program, reflecting leadership in sustainability, innovation, and performance, including sleeve solutions. These milestones matter because they signal to procurement teams and investors that recyclable, high-recycled-content designs are moving from pilot concepts to commercially validated offerings with external validation.
Market structure is likely to continue evolving along two tracks. On one hand, consolidation and partnership will remain attractive for players seeking broader geographic coverage, integrated material sourcing, and scaled compliance capabilities. On the other hand, differentiation will protect specialized producers who can offer superior insulation per gram, credible compostability or recyclability claims, or rapid custom response for regional foodservice channels. New entrants will find opportunity not in commodity overlap but in targeted engineering, compliance-forward material choices, and service models that reduce friction for high-volume buyers. The result is a landscape where scale and specialization can coexist, but only if each player clearly owns a defensible value proposition.
Forward Outlook: Trends Shaping the Next 3–5 Years
Several interrelated trends are likely to define the insulated cup sleeves market through the early 2030s. First, design-led efficiency will become a central competitive battleground. As material costs and compliance costs rise, producers that can deliver equivalent or better thermal protection with less fiber, more precise embossing, and smarter cup-sleeve integration will capture margin and procurement preference. This trend favors companies that invest in prototyping, application testing, and close collaboration with cup manufacturers, because the most efficient solutions often emerge at the interface between cup and sleeve rather than within either component alone.
Second, compliance-aligned material procurement will shift from a defensive requirement to a sourcing advantage. Extended producer responsibility frameworks and recycled content expectations are expanding the premium on traceable fiber, lower fossil intensity, and designs that fit existing recovery streams. Buyers will increasingly treat recyclability, compostability, and recycled fraction not as marketing attributes but as procurement prerequisites. This creates opportunities for suppliers that can document content composition, provide consistent lot-to-lot quality, and align sleeve architecture with regional end-of-life infrastructure. It also raises the stakes for companies that rely on ambiguous claims or inconsistent material streams, since procurement scrutiny is likely to intensify.
Third, application segmentation will deepen as channel needs diverge. Coffee shops and cafes will continue to prioritize fit, print quality, and throughput reliability. Household consumption will reward comfort, reusability compatibility, and clarity around environmental attributes. Corporate and institutional procurement will weigh compliance documentation, total cost, and supply continuity more heavily. The practical implication is that one-size positioning will lose ground to channel-tuned offerings, with modular design platforms and configurable material options becoming more valuable than rigid standardized SKUs. The opportunity lies in building flexible production and specification systems that can serve multiple channels without sacrificing cost discipline.
These trends carry risk. If recycled fiber availability tightens or quality variability increases, cost structures could become less predictable, particularly for smaller producers. If regulatory definitions around compostability, recyclability, or recycled content diverge across regions, compliance complexity could erode the benefits of otherwise strong product designs. If cup manufacturers accelerate integrated insulation features, separate sleeve demand could shift in certain premium formats, redistributing volume rather than eliminating it. Companies that monitor these forces closely and maintain agile sourcing, design, and compliance capabilities will be better positioned to convert uncertainty into commercial advantage.
Worldwide Ice Silk Sleeves Market
Actionable Guidance for Decision Makers
For manufacturers and material suppliers, the priority is to invest in insulation efficiency and compliance-ready material streams in tandem. Reducing basis weight through embossing and structural design, expanding verified recycled content, and aligning sleeve architecture with regional recovery expectations can protect margins while strengthening procurement appeal. Equally important is building close feedback loops with cup producers and high-volume foodservice buyers, because the most valuable innovations often emerge from integrated fit, handling, and printing requirements rather than from material substitution alone.
For investors, the signal is to distinguish between commoditized scale plays and differentiated capability plays. Volume growth is real, but sustained outperformance is likely to concentrate among companies that can demonstrate credible sustainability performance, consistent quality at higher recycled fractions, and application-specific engineering that reduces total handling cost for end users. Due diligence should evaluate not only capacity and footprint but also traceability systems, regulatory readiness, and the strength of customer relationships in channels where sleeve specifications are becoming more rigorous.
For procurement teams and brand operators, the focus should shift from price-per-unit comparisons to total value across handling, compliance, and supply reliability. Sleeves that fit consistently, protect comfortably, and align with local recycling or composting infrastructure can reduce operational friction and reputational risk. Evaluating suppliers on documented material composition, print performance, and continuity of supply will become more important as specifications tighten and channel expectations diverge. Where possible, coordinating sleeve selection with cup format decisions can unlock efficiency gains that are not visible when the two are procured in isolation.
The market trajectory through 2032 suggests that insulated cup sleeves will remain a meaningful and evolving segment within foodservice packaging, shaped by material engineering, regulatory alignment, and channel-specific demand. Executives who treat the category as a strategic interface between product performance, compliance, and brand trust will be better positioned to capture the opportunities embedded in the growth path. For organizations seeking deeper segmentation, competitive benchmarking, and customized procurement or investment scenarios, the full PW Consulting research report provides the detailed data and scenario-based analysis needed to translate these market-level insights into operational decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Insulated Cup Sleeves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chassis-by-Wire Market: Why 19.5% CAGR and Brake-by-Wire Shift Change Everything
By pmarketresearch, 2026-09-18
The Chassis-by-Wire Revolution: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Market
Market Current Status & Core Challenges
The global chassis-by-wire system market has entered a phase of rapid expansion, driven by the convergence of electrification, software-defined vehicle architectures, and escalating demands for advanced driver assistance capabilities. Valued at approximately USD 8.4 billion in 2025, the sector has demonstrated a compound annual growth rate of 19.5 percent over the recent historical period and is projected to sustain this aggressive trajectory through the forecast horizon ending in 2032. This growth reflects a structural shift away from hydraulic and electromechanical linkages toward fully digital, electronically mediated control systems across braking, steering, suspension, and transmission interfaces. The transition is not merely incremental; it represents a foundational rearchitecture of how vehicles interpret driver intent, manage dynamic stability, and interface with autonomous driving stacks.
Despite the robust growth trajectory, the industry faces several critical inflection points that will determine which players capture sustainable value. First, functional safety and redundancy remain paramount. Chassis systems are inherently safety-critical, and replacing mechanical fail-safes with electronic architectures demands rigorous validation, dual-redundant control loops, and fail-operational designs. The absence of universally harmonized standards outside major regulatory jurisdictions introduces compliance complexity and slows cross-market product rollouts. Second, the integration depth required to realize the full value of chassis-by-wire architectures is reshaping supplier-OEM relationships. Standalone actuators are increasingly insufficient; OEMs demand cohesive software platforms, real-time vehicle dynamics control, and seamless connectivity with domain controllers. Suppliers that cannot deliver integrated, software-enabled solutions risk commoditization. Third, the supply chain for high-reliability power electronics, precision sensors, and safety-certified semiconductors remains constrained. Scaling production while maintaining ASIL-D compliance creates bottlenecks, particularly as multiple OEMs and tier suppliers simultaneously accelerate commercialization timelines.
Key Drivers Shaping the Market
Technological innovation stands as the primary catalyst for chassis-by-wire adoption. The maturation of high-response electric actuators, low-latency communication buses, and advanced torque and position sensors has enabled steering, braking, and suspension systems to operate with precision previously achievable only through mechanical linkages. More importantly, these components are now being bundled into cohesive platforms that support over-the-air updates, predictive stability control, and seamless integration with advanced driver assistance systems. The shift toward software-defined vehicles amplifies this effect, as chassis functions become programmable layers rather than fixed hardware assemblies. Suppliers that have historically operated in isolated component silos are now competing on the basis of system-level integration, algorithmic control, and lifecycle software support.
Regulatory and standardization developments are simultaneously accelerating and shaping deployment pathways. Several major markets have moved to explicitly accommodate steer-by-wire and brake-by-wire architectures within their regulatory frameworks, provided that systems meet stringent functional safety and cybersecurity requirements. The push toward ISO 26262 compliance at ASIL-D levels, combined with cybersecurity standards such as ISO/SAE 21434, has raised the bar for entry but also created defensible moats for established players with proven validation pipelines. International standardization bodies are actively developing guidelines that clarify safety expectations for steer-by-wire systems in passenger and light commercial vehicles, offering a more predictable compliance landscape. At the same time, regional regulatory bodies have begun publishing national standards that explicitly incorporate steer-by-wire requirements, with participation from both OEMs and component suppliers. This institutional recognition reduces ambiguity for engineers and procurement teams, encouraging broader adoption beyond pilot programs.
On the demand side, consumer and fleet behavior is reinforcing the technology shift. Electrified platforms inherently free up packaging constraints associated with hydraulic lines and mechanical linkages, making by-wire systems more attractive from both a weight and design flexibility standpoint. Automakers pursuing advanced maneuvering features, reduced cabin intrusion, and enhanced driver comfort are increasingly viewing chassis-by-wire as a strategic enabler rather than a compliance checkbox. In the commercial segment, fleet operators and logistics-focused OEMs are evaluating digital chassis architectures for improved energy efficiency, predictive maintenance, and alignment with higher levels of automated operation. The commercial vehicle segment, while smaller in absolute terms than passenger cars, is gaining momentum as operators seek differentiated reliability and total cost of ownership profiles.
Supply chain and cost structure dynamics are also evolving. The transition to by-wire architectures redistributes value toward electronics, software, and system integration, while reducing reliance on traditional hydraulic components and metal-intensive linkages. However, the initial capital intensity of developing fail-operational architectures, dual-redundant controllers, and safety-certified microcontrollers remains high. Suppliers are responding by offering modular portfolios that span electric, hydraulic, and hybrid actuation options, allowing OEMs to phase adoption based on vehicle segment, safety certification timelines, and cost targets. Semiconductor and power electronics availability continues to influence production pacing, but strategic partnerships between chipmakers, tier suppliers, and OEMs are gradually stabilizing the supply base. The emergence of integrated chassis control platforms is also creating economies of scale, as shared software stacks and common sensor suites reduce per-unit engineering costs across vehicle programs.
Technology Innovation and System-Level Integration
The competitive advantage in chassis-by-wire is increasingly defined by how effectively suppliers can combine actuation hardware with control software, safety architecture, and vehicle dynamics algorithms. Companies that offer one-box or tightly integrated solutions are gaining traction with OEMs seeking to simplify wiring harnesses, reduce part counts, and accelerate software-defined chassis development. The ability to deliver steer-by-wire systems with stowable column options, electro-mechanical brake architectures, and integrated suspension actuation under a unified software layer is becoming a differentiator in premium and technology-forward vehicle segments. This integration push is also driving collaboration across the value chain, with semiconductor suppliers playing a more visible role in enabling high-safety motor control and real-time processing for by-wire applications.
PW Consulting
Policy, Standards, and Regulatory Clarity
Regulatory evolution is acting as both an enabler and a gatekeeper. As international and regional standards begin to articulate explicit requirements for steer-by-wire and brake-by-wire systems, engineers gain clearer design targets and validation pathways. The allowance of steer-by-wire architectures without mechanical backup under defined conditions in certain regulatory frameworks has reduced a long-standing barrier to full by-wire deployment. Simultaneously, the expectation of dual-controller architectures, redundant power supplies, and fail-operational behavior reinforces the need for robust engineering and testing capabilities. Suppliers with established functional safety certification records and proven cybersecurity processes are positioned to benefit from this regulatory maturation, while newer entrants must navigate a steep compliance curve.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated group of multinational suppliers with deep chassis engineering heritage, complemented by regional specialists and technology-focused entrants. The top three players account for a substantial share of industry revenue, while the top five collectively represent a majority of total market value. This concentration reflects the capital intensity, safety validation requirements, and long qualification cycles inherent to chassis-by-wire systems. However, the landscape is dynamic, with consolidation, partnership formation, and targeted acquisitions reshaping competitive positions.
Leading suppliers are pursuing distinct strategic playbooks. Continental AG has positioned itself around integrated electronic braking and chassis control solutions tailored for software-defined vehicles, emphasizing system-level coherence across brake-by-wire and broader chassis functions. ZF Friedrichshafen AG has expanded its portfolio to cover comprehensive brake-by-wire and steer-by-wire offerings, including one-box systems and a dedicated chassis solutions division that addresses light vehicles and software-defined chassis architectures. In mid-2025, ZF unveiled a broad brake-by-wire portfolio encompassing electric, hydraulic, and hybrid options, signaling flexibility to accommodate varying OEM safety strategies and cost targets. Robert Bosch GmbH continues to leverage its full chassis integration expertise, developing steer-by-wire and brake-by-wire systems that align with ADAS, automated driving, and electrified platform requirements.
Nexteer Automotive has built a focused steer-by-wire and brake-by-wire narrative, offering stowable column steer-by-wire options and an electro-mechanical brake system aimed at motion control and software-defined chassis integration. In 2025, the company launched its electro-mechanical brake system to enhance safety, comfort, and serviceability while reinforcing chassis-by-wire integration. Shortly thereafter, it achieved ASIL D functional safety certification for its steer-by-wire system with multi-layer redundancy and participated actively in China’s chassis-by-wire standards development. Nexteer’s engagement in Chinese standardization efforts, alongside supply of steer-by-wire and brake-by-wire systems to multiple domestic OEMs, illustrates how regional market access and standards influence strategy. Meanwhile, Li Auto implemented combined steer-by-wire and brake-by-wire in its L9 Livis model under a “big chassis” architecture, with subsequent deployments from other Chinese OEMs, signaling rapid commercial integration in one of the most active electrification markets.
Server Chassis Market
Regional and technology specialists are carving niches that complement the larger players. JTEKT Corporation specializes in steer-by-wire systems and chassis components, scaling production for EV and autonomous platforms. Schaeffler AG is advancing steer-by-wire and integrated actuation for vehicle motion control, while thyssenkrupp AG focuses on steer-by-wire with innovative feedforward control and vehicle motion control integration that operates independently of traditional steering column infrastructure. Kongsberg Automotive has emphasized fail-operational steer-by-wire systems, strengthened through the acquisition of Chassis Autonomy SBA AB to target autonomous and commercial vehicle applications. Infineon Technologies AG supplies the underlying chipsets and semiconductors that enable high-safety steer-by-wire and chassis-by-wire motor control, highlighting the strategic importance of the semiconductor layer in this ecosystem.
The market trajectory points toward continued consolidation at the system-integration tier, as OEMs prefer fewer, deeper partnerships that can deliver validated, software-enabled chassis platforms. At the same time, differentiation is intensifying in areas such as fail-operational architecture, cybersecurity, regional standards alignment, and packaging flexibility. New entrants with strong software stacks, specialized redundancy designs, or cost-competitive actuation technologies may find opportunities in commercial vehicles, autonomous shuttles, or specific regional markets where certification pathways are clearer and deployment cycles are shorter. The overall pattern is one of convergence around integrated platforms, paired with ongoing fragmentation in specialized capabilities and regional go-to-market strategies.
Future Trends and Commercial Opportunities
Over the next three to five years, the most consequential trend will be the mainstreaming of software-defined chassis architectures that treat steering, braking, and suspension as programmable, data-rich subsystems rather than isolated hardware. As more OEMs deploy combined steer-by-wire and brake-by-wire configurations, the value pool will shift from component supply toward system integration, control algorithms, and lifecycle software management. Commercial opportunities will accrue to suppliers that can offer validated redundancy, rapid calibration tools, and OTA-capable platforms that reduce time-to-market for next-generation vehicle programs. Companies that bridge the gap between component performance and vehicle dynamics optimization will be well positioned to capture premium pricing and longer-term service relationships.
A second trend is the convergence of chassis-by-wire adoption with higher levels of automated driving and commercial fleet electrification. As passenger cars and light commercial vehicles incorporate more advanced driver assistance and partial automation features, the need for precise, latency-sensitive chassis control will intensify. This creates opportunities for fail-operational steer-by-wire systems, integrated vehicle motion control, and architectures that simplify the interface between chassis actuators and autonomy stacks. The commercial vehicle segment, while historically slower to adopt, may accelerate as operators seek energy efficiency, predictable maintenance schedules, and platform commonality across fleets. Suppliers that tailor redundancy and validation approaches to commercial duty cycles, rather than simply adapting passenger car solutions, can open a differentiated niche.
A third trend involves regulatory and standards harmonization reducing deployment friction across markets. As international guidelines and national standards clarify safety expectations for steer-by-wire and brake-by-wire systems, engineering teams will face fewer ambiguous compliance questions, and OEMs will be more willing to commit to by-wire architectures in volume programs. This trend favors suppliers with mature functional safety processes and established cybersecurity frameworks, while also lowering barriers for regional players that can align quickly with local standards. The downside risk is that rapid regulatory evolution can still create uneven compliance requirements across jurisdictions, forcing suppliers to maintain multiple validation tracks. Additionally, semiconductor availability, cost volatility in power electronics, and the engineering complexity of fail-operational designs will continue to temper the pace of adoption in cost-sensitive segments. Strategic flexibility, modular portfolios, and clear safety case documentation will be essential to navigate these uncertainties.
Chassis Sensor Market
Strategic Recommendations for Decision Makers
For vehicle manufacturers and platform architects, the priority is to treat chassis-by-wire as a system-level capability rather than a components upgrade. Selecting partners that can deliver integrated steer-by-wire and brake-by-wire solutions with proven ASIL-D functional safety, fail-operational redundancy, and software-defined integration will reduce program risk and accelerate time-to-market. Aligning hardware choices with broader software architecture plans, including OTA capability and vehicle dynamics control strategies, will determine whether by-wire investments translate into competitive differentiation or merely compliance.
For investors and strategic planners, the opportunity lies in identifying suppliers and technology enablers with defensible safety validation pipelines, scalable redundancy architectures, and strong positions in emerging standardization processes. Companies that combine actuation hardware expertise with software control capabilities, or that provide critical semiconductor and sensor layers for high-safety chassis applications, are likely to capture disproportionate value as the market expands. Monitoring regional standards development and early commercial integrations in leading EV markets can provide leading indicators of volume adoption and partnership shifts.
For procurement and supply chain leaders, diversification and qualification strategy are essential. Given the safety-critical nature of chassis-by-wire systems, relying on a single source for redundant controllers, power electronics, or actuator assemblies introduces concentration risk. Building qualified secondary sources, aligning on cybersecurity and functional safety documentation requirements early, and securing visibility into semiconductor and power electronics roadmaps will help stabilize production schedules. Engaging with suppliers that offer modular electric, hydraulic, and hybrid options can provide flexibility to balance cost, safety certification timelines, and vehicle segment requirements.
Given the pace of technical evolution, regulatory change, and commercial integration activity, decision makers benefit from detailed, segment-level intelligence that maps supplier capabilities, regional standards trajectories, and deployment timelines to specific vehicle programs. Access to comprehensive market research and customized analysis can clarify which architectures, partnerships, and geographic pathways offer the strongest risk-adjusted opportunity in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Chassis-by-Wire System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com