

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Biliary Catheters Market: Why 5.48% CAGR Signals a Strategic Shift by 2032

Globular Trends in the Worldwide Biliary Catheters Market: Strategic Opportunities for Industry Leaders
Market Overview: Scale, Trajectory, and Critical Challenges
The global biliary catheters market has entered a phase of sustained expansion, driven by an evolving interventional gastroenterology landscape and growing demand for minimally invasive biliary drainage solutions. Valued at approximately $645.5 million in the base year of 2025, the market has demonstrated consistent growth from $503.18 million in 2020. This trajectory reflects a compound annual growth rate of 5.48 percent over the forecast period extending through 2032, with projected revenues approaching $937.75 million by the end of the forecast horizon. Such figures underscore a market that is not merely expanding in absolute terms but maturing in complexity, as clinical protocols, reimbursement frameworks, and product engineering converge to shape procurement and adoption decisions.
PW Consulting
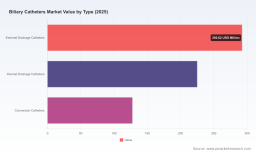
The geographic distribution of demand reveals a market where North America and Europe continue to anchor the largest revenue shares, supported by established endoscopy infrastructure, high procedural volumes, and mature reimbursement pathways. Asia Pacific represents a rapidly intensifying region, where rising healthcare expenditure, expanding specialty clinic networks, and growing adoption of percutaneous biliary interventions are accelerating volume growth. Latin America and the Middle East and Africa contribute smaller but strategically relevant portions of the market, often characterized by procurement cycles tied to public health initiatives and regional capacity-building programs. Across these regions, the product mix leans heavily toward external drainage catheters, which maintain the largest share by type, followed by internal drainage catheters and conversion catheters that serve more specialized clinical pathways. Hospitals remain the dominant end-user segment, reflecting the central role of inpatient interventional suites and radiology departments in biliary drainage procedures, while specialty clinics and ambulatory surgical centers represent growing channels for routine and follow-up interventions.
Despite the favorable growth trajectory, the market faces a set of structural challenges that will define competitive dynamics over the coming years. First, the regulatory classification of biliary catheters and accessories under Class II special controls introduces a persistent compliance burden. Manufacturers must navigate clearance pathways that demand rigorous demonstration of safety, performance, and intended use, particularly when introducing design modifications or new material formulations. Second, reimbursement architecture exerts significant influence on adoption patterns. Procedural coding for catheter placement, exchange, and imaging guidance creates a billing environment where clinical utility must be paired with clear documentation and coding accuracy. Any shifts in coverage policy, coding interpretation, or hospital cost pressure can rapidly alter procurement behavior. Third, the market exhibits meaningful concentration, with the top three competitors accounting for over forty percent of revenue and the top five exceeding fifty-eight percent. This concentration signals both the presence of established incumbents with strong distribution relationships and the potential for consolidation, as smaller manufacturers seek scale or partnerships to compete effectively. Together, these factors create a market where growth is available, but capturing it requires disciplined execution across regulatory, clinical, and commercial dimensions.
Key Drivers: Technology, Regulation, Demand, and Supply Chain Dynamics
The expansion of the biliary catheters market is propelled by a convergence of clinical, technical, and systemic forces. At the forefront is technological innovation in catheter design and delivery systems. Manufacturers are increasingly differentiating products through features such as locking loop mechanisms, radiopaque markers, hydrophilic coatings, and enlarged drainage apertures. These enhancements address practical clinical needs: improved positional stability during prolonged drainage, clearer fluoroscopic visibility during placement, reduced friction during insertion, and higher drainage efficiency for complex strictures or obstructed ducts. The availability of multiple configurations, including large-hole drainage catheters and hydrophilic-coated variants, reflects an industry response to the diversity of biliary anatomy and procedural contexts. In parallel, the use of nitinol reinforcement in select drainage catheters illustrates a focus on kink resistance and structural durability, attributes that reduce complications and improve reliability in long-term or tortuous drainage pathways.
Worldwide Pancreatic and Biliary Stent Market
Regulatory and reimbursement dynamics form a second critical driver. Biliary catheters and accessories are classified as Class II devices under special controls, a framework that balances access with oversight by requiring submission of performance data and adherence to recognized standards. Recent regulatory clearances illustrate how incremental innovation can still unlock market entry. For example, a wireguided balloon dilation catheter for biliary applications recently received FDA 510(k) clearance under a classification covering stents, drains, and dilators for biliary ducts, signaling continued openness to devices that bridge dilation and drainage workflows. Similarly, a biodegradable pancreatic stent gained clearance under the biliary catheter and accessories regulation, highlighting how adjacent product categories can leverage existing regulatory pathways to introduce materials and designs that may influence future biliary drainage strategies. On the reimbursement side, procedural codes governing percutaneous biliary drainage, exchange, and imaging guidance create a structured but scrutinized economic environment. Hospitals and clinics evaluate catheter choices not only on clinical performance but also on coding efficiency, documentation burden, and total cost of care, making reimbursement alignment a decisive factor in purchasing decisions.
Demand-side changes represent a third driver. The procedural volume for biliary drainage is expanding as interventional endoscopy and interventional radiology continue to gain traction for managing obstructions, strictures, leaks, and post-surgical complications. Clinicians increasingly favor percutaneous and endoscopic approaches that minimize invasiveness, reduce recovery time, and support outpatient or short-stay pathways where feasible. This shift is amplified by staffing and capacity constraints in many healthcare systems, which incentivize solutions that streamline procedures, reduce complication rates, and support repeat interventions without compromising outcomes. The growth of specialty clinics and ambulatory surgical centers as procurement channels reflects this trend, as these settings seek durable, user-friendly devices that fit high-throughput workflows and support standardized protocols.
Supply chain and cost structure considerations round out the driver set. The market includes a mix of large multinational manufacturers and specialized regional producers, creating a competitive ecosystem where scale, sourcing reliability, and manufacturing precision all matter. Material selection, coating consistency, and dimensional tolerances influence both performance and cost, while regional manufacturing footprints can affect lead times, logistics resilience, and pricing flexibility. In an environment where hospitals are sensitive to total cost and supply continuity, suppliers capable of delivering dependable quality, clear technical support, and responsive service gain a measurable advantage. The presence of regional manufacturers in markets such as India and Taiwan also indicates an ongoing diversification of supply sources, which can introduce cost-competitive alternatives and expand availability in emerging procurement contexts.
Competitive Landscape: Strategic Positioning and Market Evolution
The competitive field in biliary catheters is shaped by a combination of established device manufacturers and focused specialists, each pursuing distinct strategic advantages. Leading participants emphasize product portfolios that span multiple catheter types, procedural techniques, and delivery approaches. Some suppliers have built reputations around locking loop options and radiopaque markers designed for percutaneous biliary drainage, aiming to reduce migration risk and improve procedural visibility. Others differentiate through multipurpose styles compatible with direct stick or Seldinger techniques, providing clinicians with flexibility across varied access scenarios. A further set of players highlights large drainage apertures and hydrophilic coatings, positioning their devices around drainage efficiency and ease of insertion. This diversity of design philosophy indicates a market where clinical differentiation remains viable, but only when paired with robust evidence, reliable supply, and strong service support.
Strategic positioning among incumbents often revolves around three pillars: portfolio breadth, procedural alignment, and integration with procedural kits. Portfolios that cover external, internal, and conversion catheters allow suppliers to address a wider range of clinical indications and maintain relationships across multiple procedure types. Procedural alignment appears in designs that accommodate common access techniques and in the availability of kits that bundle catheters with necessary accessories, simplifying procurement and standardizing setup. Integration with broader interventional portfolios is also notable, as some manufacturers embed biliary catheters within larger drainage and interventional product lines, leveraging cross-selling and clinical familiarity to reinforce market presence. These approaches help incumbents defend share in a concentrated market while creating barriers for new entrants that lack equivalent clinical relationships or procedural coverage.
The market is evolving along several trajectories. Consolidation pressure persists given the revenue concentration among leading firms, which may encourage acquisitions, partnerships, or licensing arrangements as smaller manufacturers seek scale and broader distribution. At the same time, differentiation is increasing in the opposite direction, as specialized designs and material innovations create niches for focused players who can deliver distinct clinical value. New entrants and regional manufacturers add further complexity by introducing cost-competitive options and expanding supply diversity, particularly in growth regions where local support and affordability influence purchasing. Regulatory developments will continue to shape this evolution: clearances that validate new designs or materials can open doors for innovators, while the Class II special controls framework ensures that all participants maintain a baseline of demonstrated safety and performance. Meanwhile, reimbursement dynamics will act as a constant filter, rewarding devices that support efficient coding, clear documentation, and predictable procedural workflows. The net effect is a landscape where scale and relationships matter, but precise clinical utility and adaptable commercial models increasingly determine who gains share.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Looking ahead, the biliary catheters market is likely to be shaped by three interrelated trends. The first is continued product refinement oriented toward procedural efficiency and complication reduction. Expect broader adoption of catheters with enhanced drainage area, improved visibility features, and coatings or reinforcements that reduce friction and kinking. As clinicians accumulate experience with these design improvements, procurement patterns may favor devices that demonstrably support faster setup, more reliable positioning, and fewer exchanges, especially in high-volume settings where time and outcomes directly affect throughput and cost.
The second trend is the growing importance of procedural ecosystem alignment. Devices will increasingly be evaluated not in isolation but as part of integrated workflows that include access technique, imaging guidance, coding efficiency, and post-procedure management. Suppliers that provide clear guidance on coding relevance, procedural setup, and exchange protocols may gain an edge, particularly as hospitals seek to reduce administrative friction and standardize care pathways. This trend creates opportunities for manufacturers that invest in clinician education, procedural support materials, and documentation-friendly product information.
Medical Catheters Market
The third trend is regional expansion coupled with supply chain diversification. Growth in Asia Pacific and other emerging procurement regions will likely accelerate as infrastructure improves and procedural volumes rise. At the same time, the presence of regional manufacturers and varied sourcing options may increase price competition and broaden availability. This dynamic presents both opportunity and risk: it can expand addressable volume and create partnerships for global suppliers, but it can also pressure margins and require careful quality assurance and service planning. Uncertainty remains around the pace of reimbursement evolution, the stringency of regulatory review for design changes, and potential shifts in procurement budgets as healthcare systems balance cost control with procedural demand. Companies that monitor these signals closely and align product strategy with local clinical and economic realities will be better positioned to convert growth into sustainable share.
Strategic Actions for Decision Makers
For manufacturers, the priority is to sharpen clinical differentiation while reinforcing commercial reliability. Invest in design features that address measurable procedural needs, and support those features with clear documentation, compatible procedural kits, and responsive technical service. Ensure that regulatory and reimbursement considerations are embedded in product planning from the outset, so that new designs are not only technically sound but also aligned with coding and procurement realities. Building relationships with high-volume centers and specialty clinics can help validate performance in real workflows and strengthen adoption over time.
For investors, the market rewards disciplined capital allocation toward companies with defensible clinical positioning, stable supply operations, and scalable commercial infrastructure. Evaluate not only product portfolios but also the strength of procedural support, the consistency of regulatory execution, and the ability to navigate reimbursement frameworks. Opportunities may arise through targeted partnerships, acquisitions of niche technologies, or investments in regional manufacturing capability that improves supply resilience and market access. Attention to concentration dynamics is important, as consolidation could reshape competitive positions and create both risks and openings.
For procurement leaders and clinical decision makers, the focus should be on total value rather than unit price alone. Assess catheters based on drainage performance, insertion reliability, compatibility with existing access techniques, and support for efficient documentation and coding. Standardizing where appropriate can reduce variation and simplify training, while selective use of specialized designs can address complex cases more effectively. Engaging suppliers that provide clear procedural guidance and dependable service can help maintain throughput and reduce avoidable complications. As the market continues to evolve, access to detailed segment-level intelligence and tailored commercial insights can support more precise planning and risk management. Readers seeking deeper segmentation data, competitive benchmarking, and customized strategic guidance may consider reviewing PW Consulting’s comprehensive research report on this market.
For detailed analysis of this topic, please visit the official page: Worldwide Biliary Catheters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com