

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Electric Drivetrain Components Market: Why 20.48% CAGR Redefines the 2032 Outlook

Worldwide Automotive Electric Drivetrain Components Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
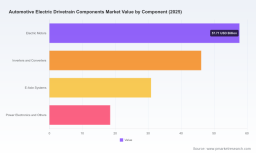
The global market for automotive electric drivetrain components has entered a phase of aggressive expansion, driven by the electrification of passenger and commercial vehicle fleets. From 2020 to 2025, the sector compounded at a rapid pace, with revenue climbing from approximately $41.25 billion to $153.16 billion. The momentum does not show signs of abating; projections through 2032 indicate the market will surpass $564 billion, maintaining a compound annual growth rate of 20.48%. This trajectory suggests that electrification is no longer a niche segment but a dominant force reshaping the powertrain landscape. The scale of this growth implies a fundamental restructuring of supply chains, manufacturing capabilities, and product architecture across the automotive value chain.
Despite the robust headline numbers, the industry stands at a critical juncture defined by three key challenges. First, the supply chain for critical raw materials remains a vulnerability. The concentration of processing capacity for rare earth elements, such as neodymium required for permanent magnets in traction motors, poses significant geopolitical and operational risks. With China controlling a vast majority of global processing capacity as of 2025, manufacturers are exposed to potential export restrictions and price volatility. This dependency forces component suppliers to reconsider motor designs, exploring magnet-free alternatives or securing diversified sourcing agreements to mitigate disruption.
Second, the regulatory environment is evolving from simple electrification mandates to complex performance standards. Recent updates, such as the EU's Automotive Package revised in December 2025, introduce flexibility mechanisms for emissions averaging between 2025 and 2027 but maintain a strict 90% tailpipe emissions reduction target from 2035. Furthermore, Euro 7 regulations now introduce brake and tyre particulate emission limits alongside battery durability requirements. These rules directly impact electric drivetrain design, necessitating components that not only deliver power efficiently but also manage particulate matter and endure longer lifecycles. Compliance is no longer just about selling an electric vehicle; it is about engineering every component to meet rigorous environmental and durability standards.
Third, cost structures are under pressure due to material price volatility and technology investment requirements. While lithium prices have corrected significantly from 2023 peaks, other materials like cobalt and nickel remain volatile, and copper demand is rising with electrification but faces supply constraints. Simultaneously, the adoption of silicon carbide (SiC) semiconductors in inverters improves efficiency but comes with high production costs and supply vulnerabilities. Balancing the need for high-performance, efficient components with the imperative to reduce bill-of-materials costs is a central tension for original equipment manufacturers and tier-one suppliers alike.
Key Drivers of Market Dynamics
Several interconnected factors are propelling the electric drivetrain components market forward, transforming it from a regulatory compliance exercise into a core competitive battleground.
Technological Innovation and Efficiency Gains
Innovation is the primary engine of growth, specifically in power electronics and motor integration. The shift toward silicon carbide (SiC) semiconductors in inverters represents a significant technological leap. SiC devices offer higher efficiency and thermal performance compared to traditional silicon-based components, allowing for smaller, lighter inverters that extend vehicle range. However, the high cost and supply constraints of SiC mean that adoption is currently focused on premium and high-volume models where range anxiety is a critical purchase barrier. Manufacturers who can secure stable SiC supply or develop cost-effective alternatives gain a distinct advantage in the high-efficiency segment.
Motor technology is also seeing diversification. While permanent magnet motors dominate due to their power density, the supply risks associated with rare earth elements are driving interest in magnet-free solutions. Companies are developing high-performance electric motors that do not rely on neodymium or dysprosium, reducing exposure to raw material bottlenecks. Additionally, integration trends are accelerating. The move toward e-axle systems and 7-in-1 integrated drive units consolidates multiple components into a single compact package. This integration simplifies assembly, reduces weight, and lowers costs, making it particularly attractive for mass-market electrification.
Policy and Regulatory Environment
Government policies continue to be a powerful catalyst. Beyond the EU's tightened CO2 standards and Euro 7 requirements, regions worldwide are implementing incentives and mandates that accelerate EV adoption. The EU's flexibility for 2025-2027 averaging provides manufacturers a temporary buffer, but the long-term trajectory remains strict. This regulatory certainty encourages investment in dedicated electric drivetrain production lines. Furthermore, regulations regarding battery durability and recyclability are pushing component suppliers to design for longevity and serviceability. The focus is shifting from just initial performance to the entire lifecycle of the drivetrain, influencing how inverters, motors, and thermal management systems are engineered and validated.
Demand-Side Shifts and Vehicle Segmentation
Consumer and corporate behavior is reshaping demand patterns. Battery Electric Vehicles (BEVs) continue to capture the largest share of the electrification market, driven by expanding model availability and improving charging infrastructure. However, Plug-in Hybrid Electric Vehicles (PHEVs) remain relevant, particularly in segments where charging access is limited or for commercial fleets requiring flexible range. This dual demand means component suppliers must cater to both pure electric and hybrid architectures. The rise of premium EVs also demands higher performance specifications, such as 800V architectures, which require robust high-voltage components like advanced onboard chargers and DC-DC converters. Manufacturers like InfiMotion are targeting these premium segments with specialized 800V drivetrains, demonstrating that high-performance electrification is a viable growth niche alongside mass-market solutions.
Supply Chain and Cost Structure Evolution
The supply chain is undergoing a structural transformation. The volatility in lithium, cobalt, and nickel prices highlights the need for strategic procurement and hedging strategies. As copper demand rises with electrification, supply constraints could become a bottleneck, prompting investment in recycling and alternative materials. Additionally, the geographic concentration of processing for critical minerals is pushing manufacturers to localize supply chains or form strategic partnerships to secure access. Cost efficiency is no longer just about labor arbitrage; it is about securing raw materials, optimizing component design for manufacturability, and leveraging scale. Companies that can navigate these supply chain complexities while maintaining quality and cost competitiveness will define the market leadership of the next decade.
Competitive Landscape and Leadership Strategies
The competitive arena for electric drivetrain components is characterized by a mix of established automotive suppliers and specialized technology firms. The market shows notable concentration, with the top three players holding a significant share, while the top five extend their reach further. This concentration suggests that scale, technological capability, and long-term customer relationships are critical barriers to entry. Major players are leveraging their existing manufacturing bases and engineering expertise to capture value across the electrification transition.
Leading companies are pursuing distinct strategic positions. German automotive supply giants such as Robert Bosch, ZF, and Continental are focusing on integrated solutions. ZF, for instance, is advancing its SELECT modular electric drive platform and AxTrax 2 electric portal axle, complemented by TherMaS thermal management systems that enhance EV range. Recent showcase activities highlight ZF's push into modular electric drive systems for city and intercity buses, utilizing SiC inverters and three-speed transmissions. This modular approach allows flexibility across vehicle types, from passenger cars to commercial transport. Bosch continues to supply comprehensive electric drivetrain transmissions, silicon carbide power electronics, and inverters, leveraging its broad portfolio to serve both passenger and commercial vehicles. Continental delivers electric powertrain components including motors and inverters as part of a broader electrification portfolio, emphasizing integration and system-level optimization.
Automotive Parts and Components Market
American and Canadian players are also making significant moves. Magna International provides EtelligentDrive BEV powertrain systems and eDrive units across various power levels, catering to AWD EVs and hybrids. Their 2025 annual report highlights continued supply of primary and secondary electric drive systems, underscoring their role as a key tier-one partner. BorgWarner is supplying high-voltage electric motors and 800V onboard chargers/DC-DC converters with SiC semiconductors, positioning itself in the high-voltage architecture segment. Dana Incorporated focuses on e-axles and electrified drivetrain solutions for commercial and passenger vehicles, leveraging its driveline heritage.
Worldwide Rail Components Market
Japanese and Korean manufacturers are strong contenders, particularly in motors and e-axles. Nidec is pushing the boundaries with 3rd and 4th-generation E-Axle systems, including 7-in-1 integrated units and magnet-free high-performance E-Axles. Exhibitions of these technologies demonstrate Nidec's commitment to innovation and mass production readiness. Denso and Aisin offer electrification systems including motors, inverters, and e-axles optimized for EVs and hybrids. Hitachi Astemo supplies electric motors, inverters, and complete powertrain systems, while Hyundai Mobis manufactures integrated electric drive systems and e-axles for 400V/800V platforms, backing the growing Korean EV ecosystem.
European specialists like Valeo and Schaeffler are carving niches based on specific technologies. Valeo develops compact e-drive systems and magnet-free electric motors in partnership with MAHLE, alongside regenerative braking technologies. This focus on magnet-free solutions and braking integration addresses both material supply concerns and regulatory requirements for particulate emissions. Schaeffler provides e-motors, power electronics, and integrated e-axles through its E-Mobility division, complementing traditional bearing and transmission expertise with electrification capabilities.
New entrants and specialized firms are also disrupting the landscape. InfiMotion Technology, with operations in China and Sweden, develops 800V L700 PMSM electric drivetrains and gearboxes for premium EVs. Partnerships with global premium manufacturers to deliver high-horsepower drivetrains for new models illustrate how specialized suppliers can capture high-value segments. GKN Automotive provides e-axles and torque vectoring systems, adding performance differentiation to electrified drivelines.
The market is evolving through both consolidation and differentiation. Integrated platforms are becoming the norm, as suppliers seek to offer complete drive units rather than individual components. This trend favors players with broad portfolios and the ability to co-engineer with OEMs. At the same time, differentiation is emerging in areas like SiC adoption, magnet-free motors, thermal management, and high-voltage architectures. Companies that can balance scale with technological specialization will be best positioned to navigate the shifting competitive dynamics.
Future Trends and Outlook
Looking ahead to the next three to five years, several trends are poised to shape the electric drivetrain components market.
First, the adoption of integrated and modular architectures will accelerate. As OEMs seek to simplify vehicle assembly and reduce costs, demand for e-axles and multi-component integrated drive units will grow. Suppliers that can offer scalable modular platforms, adaptable to different vehicle sizes and performance requirements, will capture significant market share. The trend toward modularity is evident in recent product showcases featuring systems for both city buses and passenger vehicles, highlighting the versatility required in modern drivetrain solutions.
Second, material innovation and supply chain resilience will become strategic imperatives. The push for magnet-free motors and the challenges associated with SiC supply will drive investment in alternative materials and manufacturing processes. Companies that develop robust strategies for rare earth independence or secure long-term SiC supply agreements will mitigate risk and potentially gain cost advantages. Recycling and circular economy initiatives may also gain traction as regulations tighten around battery durability and material traceability.
Third, the regulatory focus on holistic vehicle performance will influence component design. Euro 7 and similar regulations worldwide will require drivetrain components to contribute to lower particulate emissions and longer durability. This may lead to innovations in regenerative braking, thermal management, and motor control algorithms that optimize efficiency and wear. Suppliers that anticipate these requirements and design components accordingly will offer added value to OEMs navigating compliance.
Commercial opportunities lie in serving the expanding BEV market, the persistent demand for PHEV components, and the high-performance premium segment. However, risks remain. Raw material price volatility, geopolitical tensions affecting supply chains, and the pace of regulatory changes could impact margins and demand forecasts. Additionally, the competitive intensity may lead to price pressure, especially in commoditizing segments. Success will depend on agility, technological leadership, and the ability to forge strategic partnerships across the value chain.
Strategic Recommendations for Decision Makers
For manufacturers and suppliers, prioritizing technological differentiation is essential. Investing in SiC capabilities, magnet-free motor designs, or advanced thermal management systems can create competitive moats. Simultaneously, securing supply chain resilience through diversified sourcing, long-term contracts, or vertical integration in critical materials should be a strategic priority. Modular platform development can also provide flexibility to serve multiple vehicle segments efficiently.
Investors should focus on companies with strong IP portfolios, scalable manufacturing capabilities, and exposure to high-growth segments such as 800V architectures and commercial EV drivetrains. Monitoring regulatory developments and raw material trends is crucial for assessing risk and opportunity. Companies that demonstrate progress in cost reduction while maintaining performance standards are likely to deliver sustainable value.
Procurement and OEM strategists should engage early with suppliers to co-develop solutions that meet upcoming regulatory requirements, such as Euro 7 particulate limits and battery durability standards. Diversifying the supplier base for critical components like inverters and motors can mitigate supply risks. Evaluating suppliers based on their ability to provide integrated solutions and support lifecycle requirements will help optimize total cost of ownership.
Detailed segmentation data, regional breakdowns, and customized scenario analysis are available in comprehensive research reports that provide deeper granularity on market dynamics, competitive positioning, and forward-looking indicators. Access to such detailed intelligence enables stakeholders to refine strategies, identify niche opportunities, and navigate the complexities of the electric drivetrain components market with confidence.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Electric Drivetrain Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com