

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Probe Cards Market: Why 7.45% CAGR and Asia Pacific Dominance Redefine Growth

Navigating the Worldwide Probe Cards Market: Strategic Trends and Commercial Opportunities (2025–2032)
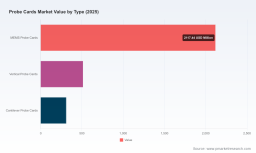
The global market for probe cards entered a phase of structural expansion in 2025, with total revenue reaching approximately USD 2.94 billion. Over the historical window from 2020 through 2025, the segment demonstrated volatile but ultimately upward momentum, reflecting both cyclical semiconductor demand and the accelerating need for wafer-level test infrastructure. Looking ahead to 2032, revenue is projected to surpass USD 4.8 billion, driven by a consistent compound annual growth rate of 7.45 percent. This trajectory signals more than steady demand; it indicates a market undergoing technological maturation, geographic rebalancing, and increasing specialization tied to advanced packaging and high-performance computing workloads.
It is important to recognize the limited window between headline growth and operational reality. The market remains highly concentrated, with three firms capturing more than half of total revenue and five firms accounting for nearly three-quarters. This concentration creates both stability and fragility. Incumbent suppliers benefit from entrenched qualification cycles, long-term design-in relationships, and deep process knowledge, yet it also means that late entrants and regional players must find sharp differentiation to escape the margins of the middle market. At the same time, the customer base is fragmenting by design complexity. Foundries and logic manufacturers, memory device producers, and analog/Radio Frequency fabricated ecosystems each place different demands on probe card performance, lifespan, and interface architecture, making one-size-fits-all solutions increasingly untenable.
Within that backdrop, the industry faces several defining challenges. The first is technological transition at advanced nodes. As wafer geometries shrink and multi-die architectures become standard, probe cards must sustain finer pitch, higher pin counts, and more stable contact reliability across thousands of test cycles. The second challenge is timing, particularly the alignment between probe card availability and fab ramp schedules. Longer lead times can create bottlenecks at the most critical moment in product launches, especially when test capacity becomes a gating factor for yield maturation. The third challenge is cost pressure combined with scope expansion. Customers increasingly expect suppliers to support not only traditional wafer acceptance test but also more complex validation for 3D and 2.5D integration, high-bandwidth memory, and advanced logic stacks. Meeting these expectations requires more than incremental refinements; it demands new materials strategies, precision manufacturing, and closer co-development with device makers.
For business leaders, the immediate implication is straightforward: probe cards are no longer a commoditized consumable. They are a strategic interface between process technology and test yield, and their performance increasingly determines how quickly new nodes and new packaging formats can reach volume production. Companies that understand where the market is intensifying—and where it is splintering—will be better positioned to plan product roadmaps, secure qualified supply, and make informed capital decisions.
Key Drivers Reshaping the Probe Cards Market
Several forces are converging to shape demand, supply, and competitive positioning over the next several years. The most consequential is the pace of device architecture change. Advanced nodes, high-bandwidth memory stacks, and heterogeneous integration are pushing test interfaces to their practical limits. As design rules tighten, probe cards must deliver higher contact density, improved signal integrity, and more consistent mechanical behavior across large wafer areas. That requirement alone is accelerating adoption of micro-electro-mechanical systems-based probe cards, which can support finer pitch and higher pin counts more effectively than many legacy approaches. Vertical probe card designs are also gaining relevance because they can provide improved reliability and easier integration in certain advanced test configurations. The result is a market in which product architecture choices are being driven by test requirements that are themselves dictated by device complexity, not by probe card conventions.
Policy and regional industrial strategy form the second major driver. Semiconductor sovereignty efforts have encouraged governments to support domestic fabrication capacity, packaging ecosystems, and qualifying local suppliers. This is visible in new facility investments and regional expansion strategies that align probe card production more closely with where advanced fabs are being built. A notable example is the opening of an approximately EUR 80 million facility in Dresden aimed at supporting European semiconductor fabs, a move that reflects a broader shift toward localized supply and regional resilience. In parallel, tighter export controls and trade barriers are beginning to reshape cross-border equipment and component flows. These dynamics do not simply alter logistics; they influence which companies can serve which markets, how long qualification cycles take, and whether global suppliers must assemble regional production footprints to remain competitive.
The third driver is demand-side behavior across end-use markets. Memory remains a central application for probe cards, but the composition of memory demand is changing as high-bandwidth memory becomes tightly coupled with accelerator and AI workloads. Foundries and logic manufacturers continue to dominate revenue share, but the test requirements within that segment are diversifying rapidly. New architectures require probe card solutions that can handle more complex test patterns, higher bandwidth needs, and more demanding mechanical tolerance. At the same time, advanced packaging trends such as chiplets are changing the test conversation from single-die validation to multi-component interface validation. This broadens the scope of probe card design and encourages closer partnership between test suppliers and packaging or assembly houses.
Supply chain and cost dynamics complete the picture. Raw material constraints and geopolitical tensions have introduced meaningful variability into production planning. In recent years, lead times for probe card production have experienced delays of up to 20 percent in some cases, illustrating how fragile schedules can become when materials such as tungsten and copper are disrupted or when regional trade conditions shift. Ceramic substrates for probe cards, particularly 300mm formats, also represent a concentrated materials dependency, with a dominant share of the relevant materials market tied to those components. In response, manufacturers are increasing localized production and diversifying supply chains, reducing exposure to single-source bottlenecks. This shift has strategic implications: suppliers that can guarantee stable lead times, consistent quality, and resilient sourcing are increasingly differentiating themselves on reliability as much as on performance.
The overarching insight is that probe card demand is being shaped at the intersection of design complexity, regional policy, and supply resilience. Each of these drivers pushes the market toward higher specialization and tighter co-development, which in turn raises the value of suppliers that can move quickly, qualify early, and sustain production predictability.
Competitive Landscape and Leading Strategies
The probe cards market continues to be defined by a relatively small group of dominant suppliers supported by a broader field of specialized players. At the top tier, leading global providers of advanced wafer probe cards have built strong positions across logic, foundry, DRAM, and high-bandwidth memory applications. These companies compete not just on probe card hardware, but on the ability to sustain technology roadmaps, secure qualification with major manufacturers, and support complex test environments at scale. Their strength comes from a combination of process expertise, broad application coverage, and long-established relationships with high-volume device makers.
A second tier of major suppliers has expanded its relevance through advanced micro-electro-mechanical systems and vertical probe technologies, often targeting high-performance wafer testing for global foundries and integrated device manufacturers. Another cluster of well-established Japanese manufacturers focuses on precision probe cards for fine-pitch and advanced node testing, leveraging strong engineering heritage and close ties to Asian semiconductor ecosystems. Taiwan-based suppliers have strengthened their presence by emphasizing innovative solutions, with some expanding capacity to address AI and high-performance computing-related demand. South Korean suppliers remain important participants, especially where memory and logic testing intersect with domestic fabrication priorities. European and UK-based firms contribute specialized capabilities, including high-quality contact solutions, blade and cantilever designs, and vertical probe cards with high voltage or current capabilities. Together, these players create a market in which geography, technology focus, and application specialization all matter.
Recent developments show how companies are competing for positional advantage. One major supplier strengthened its micro-electro-mechanical systems position by acquiring a California-based firm, adding patents tied to vertical spring optimization for probe cards. That kind of move illustrates a broader pattern: incumbents are trying to lock in capability advantages that directly affect contact reliability and design flexibility. On the qualification side, one Japanese manufacturer secured recognition as a primary supplier for 2 nm probe card solutions after co-development work with TSMC, a milestone that underscores how advanced node access can be earned through sustained collaboration rather than product announcements alone. Another Asian supplier partnered with a major assembly and test player to co-develop chiplet-ready probe cards, signaling that test strategy is increasingly extending beyond the wafer into package-level validation. On the product side, a new series of 3D/2.5D micro-electro-mechanical systems probe cards for wafer acceptance test applications has entered the market with fine-pitch and high-pin-count support, reflecting the growing need for specialized tools in advanced packaging test flows. Meanwhile, regional expansion continues, with new facility investments in Taiwan designed to address demand from AI chip testing, and other firms pursuing localized production and supply chain diversification to reduce exposure to material disruptions.
The competitive landscape is evolving along several axes at once. Integration is increasing where large suppliers absorb niche technology or complementary intellectual property to broaden their portfolios. Differentiation is sharpening around advanced node qualification, high-bandwidth memory, chiplet-related test support, and materials or design innovations that improve contact performance. New entry is difficult at the top of the market because of qualification barriers and entrenched design-ins, but opportunities remain for specialists that can serve specific applications, support regional fabs, or provide tailored solutions where standard offerings fall short. The most resilient companies are likely to be those that combine technical precision with customer co-development, regional supply visibility, and the ability to move from prototype to volume with predictable timing.
PW Consulting
Forward Outlook: Three Trends Defining the Next Three to Five Years
The first trend to watch is the deepening alignment between probe card architecture and advanced packaging roadmaps. As 3D, 2.5D, and chiplet-based designs become more common in high-value product categories, probe card solutions will need to support more intricate test interfaces and more demanding mechanical requirements. Companies that invest early in designs suited to fine-pitch, high-pin-count, and high-density test conditions will be better positioned to participate in next-generation validation cycles. The commercial opportunity here is not simply selling more cards; it is becoming embedded in test plans before production ramps begin.
The second trend is the continued rebalancing of manufacturing geography. Regional fab expansion, policy support, and supply chain risk mitigation are encouraging localized production and material diversification. Suppliers with flexible production footprints and resilient sourcing strategies will have an advantage in meeting lead-time expectations and maintaining continuity during disruption. For customers, this trend creates both optionality and complexity: multiple regional sources can reduce dependency, but they also increase the need for qualification discipline and supplier management.
The third trend is the growing premium on reliability and predictability in test supply. As probe cards become more technically specialized and more tightly coupled to advanced node and memory roadmaps, the cost of late delivery or unstable performance rises. Buyers will increasingly reward suppliers that can demonstrate consistent lead times, stable materials availability, and strong co-development processes. At the same time, trade policy and export restrictions will remain a source of uncertainty, particularly for companies operating across multiple regions. These dynamics suggest that long-term competitiveness will depend as much on operational resilience as on product performance.
Probe Card Market
Actionable Guidance for Decision Makers
For probe card manufacturers, the priority is to align technology roadmaps with where device complexity is heading, not where it has already been. That means investing in architectures and process improvements suited to advanced logic, high-bandwidth memory, and heterogeneous packaging, while also building regional production options and diversified sourcing to protect lead times. Co-development relationships with key customers should be treated as strategic assets, because qualification timing and design-in access often matter more than incremental feature lists.
For investors, the market rewards players that combine credible advanced-node capability with operational resilience. Attention should be directed toward suppliers with strong qualification momentum, clear application focus, and evidence of capacity or technology moves that anticipate AI, memory, and advanced packaging demand. Concentration in the market is high, so differentiation, proprietary technology, and regional supply strategy are important indicators of durability.
For procurement and operations leaders, the commercial task is to reduce single-point dependency without sacrificing qualification rigor. Diversifying sources can improve resilience, but it must be paired with disciplined qualification, clear lead-time expectations, and close coordination with internal test roadmaps. As advanced package and high-bandwidth memory programs become more central, early engagement with test suppliers will help reduce schedule risk and avoid last-minute constraints.
Vertical Probe Cards Market
For decision makers seeking deeper segmentation, regional breakdowns, competitive tracking, and scenario-based insight, the full PW Consulting study on the worldwide probe cards market provides expanded detail and supporting analysis to inform planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Probe Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com