

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Chip Probing Market: Why Automation Tools Are Reshaping Growth

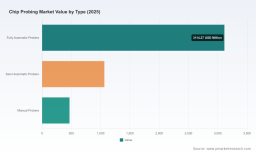
Navigating the Next Wave: Strategic Insights into the Worldwide Chip Probing Market
The worldwide chip probing market has entered a decisive phase of expansion, defined by surging test complexity and a structural shift toward higher parallelism. Valued at approximately $4.65 billion in 2025, the market has grown from $2.84 billion in 2020, reflecting a compound annual growth rate of 9.21 percent through 2032, when it is projected to approach $8.6 billion. This trajectory is not merely a function of volume; it signals a fundamental recalibration of how semiconductors are validated at the wafer level. As device architectures fracture into heterogeneous integration, chiplets, and advanced memory stacks, probing has moved from a supporting test step to a critical yield-enabling bottleneck. The base-year momentum underscores that capital is flowing into test infrastructure at a pace that outstrips historical norms, yet the expansion is unevenly distributed across technology nodes and application segments.
Beneath the headline growth, the industry confronts three interlocking challenges that will shape competitive outcomes over the next three years. First, sub-5 nanometer design complexity has slowed the introduction of new probe card architectures, with roughly one in four new designs encountering development delays as pin counts, signal integrity requirements, and thermal constraints intensify. Second, geopolitical export controls have introduced new friction into equipment flows. Refinements to the U.S. Foreign-Produced Direct Product Rule now capture certain wafer probing equipment with positioning accuracy finer than 3.5 micrometers for advanced computing applications, forcing suppliers and buyers to reconfigure supply chains and qualification pathways. Third, the economics of high-precision probing remain punishing. Fine-pitch probe cards can exceed $80,000 per unit in materials and precision assembly costs, while nearly two in five wafer test probe cards in recent years have incorporated advanced tungsten and nickel alloys to sustain durability under repeated contact cycles. These cost and complexity pressures are compressing margins for incumbents and raising the barrier for new entrants, even as demand accelerates.
The result is a market that rewards technological agility, vertical integration, and early alignment with advanced packaging and high-bandwidth memory roadmaps. Growth is no longer driven by uniform volume increases; it is being pulled by a subset of high-value applications that demand higher parallelism, lower contact resistance, and specialized RF or photonic test capabilities. Companies that can reconcile cost discipline with rapid design iteration will capture disproportionate share as the market scales toward the end of the decade.
Key Drivers Reshaping the Market
Technological Innovation and the Parallelism Imperative
The most consequential driver is the technical escalation of wafer-level testing requirements. Modern logic and system-on-chip devices, alongside high-bandwidth memory stacks, are pushing probe cards toward higher contact densities, finer pitches, and multi-site test configurations that maximize throughput. MEMS-based probe architectures and vertical probe designs have emerged as enabling technologies for these workloads, offering improved mechanical stability and better alignment with advanced node geometries. At the same time, test content is expanding beyond traditional DC and analog verification to include RF, mmWave, cryogenic, and silicon photonics characterization. This broadening test envelope is reshaping product roadmaps, as suppliers invest in specialized probe heads and integrated test systems that can address co-packaged optics and heterogeneous die-to-die interfaces. The practical effect is a market where performance differentiation increasingly hinges on the ability to deliver high-parallelism solutions without sacrificing yield or signal integrity.
Policy, Export Controls, and Infrastructure Acceleration
Policy dynamics are reshaping both the pace and geography of deployment. On one side, export control refinements have added complexity to equipment sourcing for advanced computing workloads, particularly where positioning accuracy and application context intersect with controlled thresholds. These rules do not halt demand, but they compel manufacturers to diversify supply, accelerate Qualification timelines, and in some cases re-architect test cells to remain compliant while preserving performance. On the other side, domestic semiconductor incentives are compressing time-to-production for new fab lines. Grant programs associated with national chip initiatives have helped accelerate probe card qualification for new facilities, shortening the window between process bring-up and volume test readiness. This dual force—more restrictive cross-border equipment flows paired with faster domestic fab ramp schedules—creates a distinct operating environment in which suppliers with localized manufacturing, flexible qualification processes, and broad technology portfolios gain strategic leverage.
Demand-Side Shifts: AI, HBM, and High-Performance Computing
Demand is being reconfigured by the rapid scaling of artificial intelligence accelerators, high-bandwidth memory, and high-performance computing platforms. These applications impose unusually stringent test requirements, including high contact density for multi-die validation, high-frequency signal fidelity for RF paths, and specialized handling for advanced packaging configurations. Lead-time signals already reflect this pressure: major probe card suppliers have reported extended delivery timelines, with some probe card lead times stretching to roughly six months as AI-related demand absorbs available capacity. Record financial results at several leading suppliers underscore the breadth of this demand surge, while also highlighting capacity as a binding constraint. The strategic implication is that demand is being shaped not just by unit volume but by test intensity—each advanced device now requires more probing content per wafer, amplifying the value of high-throughput, high-reliability probe solutions.
Supply Chain and Cost Structure Realities
Cost structure and material availability form the fourth pillar of change. Fine-pitch probe card production demands precision assembly and specialized alloys, pushing per-unit costs into a range that rewards scale and process maturity. The widespread use of advanced tungsten and nickel alloys in recent years reflects an industry-wide push to improve contact durability and reduce downstream yield loss, but it also ties supplier economics to material sourcing and manufacturing precision. Meanwhile, strategic partnerships and selective investments are beginning to reshape the supply base. Collaborations between test equipment producers and probe card specialists have deepened, combining complementary strengths in instrumentation, printed circuit board design, and probe technology. These alliances are accelerating development cycles and distributing risk in a market where design complexity and capacity constraints can otherwise slow responsiveness. The net effect is a supply environment in which cost discipline, material reliability, and partnership ecosystems are becoming as important as raw engineering talent.
Competitive Landscape and Leading Strategies
The competitive structure of the chip probing market is concentrated and capability-driven. The top three suppliers command a combined share in the high-sixy percent range, and the top five approach the low-eighties, reflecting the advantages of scale, established foundry and OSAT relationships, and deep application-specific engineering. Yet concentration has not translated into uniformity. Leaders are differentiating along technology axes—MEMS and vertical probe architectures, RF and photonics test readiness, cryogenic capability, and advanced packaging support—while also expanding through targeted acquisitions, capacity investments, and long-term supply agreements. The field is broad enough to accommodate specialized players in memory, logic, RF, and photonics, but the center of gravity is shifting toward suppliers that can address multiple high-growth segments without diluting technical focus.
PW Consulting
FormFactor exemplifies the integrated, high-parallelism strategy. Headquartered in Livermore, California, the company has built a portfolio around advanced wafer probe cards, including MEMS-based solutions for high-parallelism SoC, HBM, DRAM, and logic testing, alongside systems for RF, cryogenic, and silicon photonics probing. Its recent activity shows a deliberate push into capacity, partnerships, and adjacent technology domains. A new manufacturing facility in Farmers Branch, Texas, was acquired to support increased probe card demand driven by advanced packaging and HBM. In parallel, the company expanded its MeasureOne Partner Program with Rohde & Schwarz to advance on-wafer RF component characterization, and it was recognized with a 2026 Intel EPIC Supplier Award. On the inorganic side, the acquisition of Keystone Photonics extended silicon photonics and co-packaged optics wafer test capabilities. A strategic partnership with Advantest, involving minority investment and technology and PCB collaboration, further signals a preference for ecosystem alignment in probe card development. Taken together, these moves reflect a strategy that blends scale, specialized test content, and partnership-driven innovation.
Technoprobe, based in Cernusco Lombardone, Italy, competes through precision probe card design and a strong emphasis on vertical and MEMS technologies for high-volume wafer-level testing across logic, memory, and advanced packaging. Its recent supply agreement— a five-year commitment with WinWay Technology and MS SUN for MEMS probe cards based on Technoprobe’s proprietary TPEG technology—illustrates a strategy of locking in demand while extending technology reach through partners. This long-term contracting approach helps stabilize utilization and funds continued investment in high-parallelism and advanced node test solutions. MPI Corporation, headquartered in Hsinchu, Taiwan, has positioned itself around advanced probe card technologies and one-stop wafer sort test solutions, including TITAN RF probes spanning DC to 250 GHz and high-performance cards for RF, mmWave, photonics, and AI/HPC semiconductor testing. Its demand signal is notable: probe card lead times have stretched to six months amid strong AI chip demand, even as the company reported record 2025 revenue and profit alongside capacity expansion plans. MPI’s profile highlights how RF and mmWave competencies are becoming a differentiator as test content diversifies.
The regional dimension of competition is equally important. Micronics Japan and Japan Electronic Materials bring high-precision probe card expertise and close foundry collaborations, with strengths in advanced node testing, DRAM, Flash, and logic applications, as well as high-frequency materials and precision engineering. European participation remains meaningful through Feinmetall’s focus on contact probes and fine-pitch, high-reliability probe cards. In Asia, a dense cohort of suppliers—including SV Probe in Singapore, TSE and Korea Instrument in South Korea, and a cluster of Taiwanese and Korean specialists such as CHPT, WinWay Technology, Nidec SV TCL, Microfriend, STAr Technologies, and Wentworth Laboratories in the United States—demonstrates how regional manufacturing footprints and foundry relationships continue to shape access and responsiveness. This multifaceted landscape suggests two concurrent trends: consolidation among the most capable, multi-segment players, and sustained differentiation among specialists who can meet the exacting requirements of memory, RF, photonics, or advanced packaging niches. New entrants face a high bar, not only because of cost and precision demands, but because qualification cycles and customer integration depth favor incumbents with proven track records.
Probe Card Market
Future Trends and Commercial Opportunities
Looking toward 2030 and beyond, three trends are likely to define the market’s evolution. The first is the normalization of high-parallelism probing as a baseline requirement rather than a premium option. As chiplet-based designs, advanced packaging, and high-bandwidth memory become more pervasive, test cells will increasingly rely on multi-site configurations and vertical probe architectures that can address dense interface arrays with consistent contact performance. Suppliers that standardize high-parallelism platforms while retaining flexibility for application-specific variants will be best positioned to capture recurring demand and shorten qualification cycles for new device families.
Worldwide Probe Cards Market
The second trend is the convergence of probe cards with broader test ecosystems. RF, mmWave, cryogenic, and photonics test capabilities are moving from specialty add-ons to core considerations for a growing set of applications. This convergence opens commercial opportunities for integrated solutions that combine probe hardware, instrumentation alignment, and software-driven calibration, reducing the integration burden on device makers and test houses. It also favors suppliers that can orchestrate partnerships across the test chain, ensuring that wafer-level characterization keeps pace with device complexity without fragmenting accountability across too many vendors.
The third trend is geopolitical and operational decentralization. Export rule refinements and regional incentive programs are encouraging more localized qualification, manufacturing, and supply redundancy. For commercial players, this creates opportunities to build or strengthen regional capacity, align with domestic fab and packaging roadmaps, and offer predictable lead times in environments where supply assurance is becoming a competitive differentiator. The associated risk is that regulatory scope may continue to evolve, particularly around controlled accuracy thresholds and advanced computing end uses, requiring agile compliance strategies and flexible product configurations. Design complexity for leading-edge nodes will remain a persistent source of delay risk, and material cost volatility can pressure margins if not offset by scale or value-based pricing. Companies that treat these uncertainties as design inputs—by diversifying supply, modularizing probe architectures, and investing in early co-development with customers—will convert risk into durable advantage.
Strategic Actions for Decision-Makers
For probe card manufacturers and test equipment suppliers, the priority is to align capacity expansion with the highest-value demand nodes while preserving technology breadth. Investing in high-parallelism platforms, RF and photonics readiness, and advanced packaging test content should be paired with long-term supply agreements and selective partnerships that stabilize utilization and shorten development cycles. Localized manufacturing and qualification agility will increasingly matter as customers seek predictable lead times and regulatory resilience. Differentiation will come less from generic scale than from the ability to deliver repeatable performance across demanding applications while controlling per-unit cost through process maturity and material strategy.
For investors, the market’s growth is real, but share gains will be uneven. The most compelling opportunities lie with suppliers that demonstrate multi-segment capability, especially where MEMS, vertical probe, RF, and photonics competencies intersect with AI/HPC and HBM roadmaps. Monitoring lead-time signals, capacity announcements, and partnership or acquisition activity provides early indication of which players are converting demand into durable positioning. Valuation should account for the capital intensity of precision assembly, the importance of alkalinity in materials sourcing, and the potential for consolidation among mid-tier specialists who lack the breadth to compete across logic, memory, and advanced packaging.
For procurement and test strategy leaders, the practical imperative is to reduce integration risk while preserving optionality. Prioritize suppliers with proven qualification depth and the ability to support multiple test modalities, and structure agreements to balance volume commitments with flexibility for evolving device architectures. Engaging earlier in the design cycle—aligning probe card selection with packaging, interface, and test content decisions—can compress qualification timelines and mitigate the delays associated with leading-edge node complexity. Building redundancy into the supplier base, where feasible, helps manage exposure to export control shifts and capacity constraints without sacrificing performance.
The chip probing market is being reshaped by the simultaneous pull of advanced device complexity, policy-driven supply reconfiguration, and demand intensity from AI and high-performance computing. Navigating this environment requires more than broad market data; it demands segment-level visibility into technology roadmaps, supplier capabilities, and the contractual and regulatory dynamics that determine who captures value as the market scales. For decision-makers seeking granular segmentation, regional demand patterns, and tailored strategic recommendations, the full PW Consulting study provides the detailed evidence base and scenario analysis needed to translate these trends into concrete action.
For detailed analysis of this topic, please visit the official page: Worldwide Chip Probing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com