

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Casting Tip and Nozzle Market: Why 5.24% CAGR Reshapes Global Growth

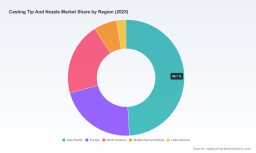
Strategic Trends and Commercial Opportunities in the Global Casting Tip and Nozzle Market
Market Overview and Core Challenges
The worldwide market for casting tips and nozzles has steadily matured into a critical enabler of modern metallurgical production. Valued at approximately $336.1 million in 2025, the market has expanded from $258.4 million in 2020, reflecting a compound annual growth rate of 5.24 percent through the early stages of the current decade. Looking ahead to 2032, the trajectory points toward roughly $480.9 million, a shift that underscores sustained demand for precision flow control and thermal management components across continuous and semi-continuous casting environments. While the growth rate is moderate rather than explosive, the underlying drivers point to meaningful structural upgrades rather than cyclical expansions. Manufacturers and foundries alike are moving beyond basic replacement parts toward engineered solutions that extend campaign lengths, reduce breakout incidents, and improve strand surface integrity.
Several converging challenges are testing the industry's adaptability. First, thermal and erosion resistance remain persistent bottlenecks. Casting environments expose tips and nozzles to extreme temperature gradients, chemical interactions with molten metal, and mechanical stress during insertion and withdrawal. When components fail prematurely, campaign interruptions, metal losses, and unplanned maintenance cascade through production schedules. Second, the supply base is navigating raw material volatility and processing constraints. High-performance refractories and ceramic composites depend on tightly controlled calcination, particle sizing, and forming methods, and any disruption in precursor availability or energy costs can compress margins or delay qualification cycles. Third, end-users are demanding more predictable performance without sacrificing flexibility. Facilities running multiple alloys, varying pour rates, or transitioning between aluminum and steel lines expect components that deliver consistent flow characteristics while accommodating frequent changeovers. Overcoming these pressures requires more than incremental material upgrades; it calls for integrated design thinking that aligns nozzle geometry, thermal profiles, and installation practices with real-world operating conditions.
The broader implication is that the market is transitioning from a commodity mindset toward engineered performance. Buyers increasingly evaluate total cost over the casting cycle rather than unit price alone, and suppliers that can demonstrate reliability, repeatability, and shorter changeover times are gaining preference. Simultaneously, the competitive field remains moderately fragmented, with market concentration reflecting a mix of specialized manufacturers and broader industrial players. This structure creates both opportunities for differentiation and risks of margin pressure where products become interchangeable. Companies that can translate material science, application expertise, and field support into measurable operational gains will be best positioned to capture value as buyers prioritize consistency and uptime over lowest upfront cost.
Key Drivers Shaping the Market
Technological innovation is one of the most visible forces reshaping the casting tip and nozzle landscape. Advances in ceramic fiber and aluminum silicate composite formulations have improved high-temperature stability, non-stick behavior, and dimensional consistency, which directly benefits aluminum casting operations where adhesion and thermal shock are persistent concerns. In steel continuous casting, zirconia-based tundish metering nozzles and precision inserts are increasingly relied upon for erosion resistance and controlled discharge, helping maintain stable flow during extended campaigns. Beyond materials, design refinement is accelerating. Nozzle and tip geometries are being optimized to deliver more uniform metal distribution, reduce turbulence, and support consistent solidification behavior. For secondary cooling in continuous casting, improvements in spray pattern uniformity and droplet control are helping producers manage strand temperatures more precisely, which can reduce surface defects and support higher throughput.
Regulatory and operational standards also play a meaningful role in shaping demand. Foundries and casting facilities operate under increasingly stringent expectations for safety, environmental compliance, and process control. While the component itself may not always be the direct subject of regulation, the operational requirements that stem from quality assurance, emissions management, and process reliability indirectly drive preference for products that reduce variability. In steel casting, for example, the need to prevent surface cracks and other strand defects through controlled secondary cooling encourages adoption of nozzles that deliver repeatable spray profiles. In aluminum operations, components that minimize contact-related sticking and support cleaner breakouts can help facilities reduce downtime and rework. These conditions reward suppliers whose products contribute to process stability and help buyers document consistent performance.
Fire Nozzle Market
Demand-side dynamics are shifting as metal producers balance quality, efficiency, and flexibility. Aluminum casting continues to represent the largest application context within this market, reflecting widespread use in high-volume production where controlled flow and thermal management are central to yield and surface quality. Steel casting remains another major pillar, with needs concentrated around tundish metering, ladle-to-tundish flow control, and secondary cooling. A growing emphasis on non-ferrous alloy casting is also expanding the scope of component requirements, as producers work with materials that can impose different thermal and chemical stresses. On the behavioral side, buyers are increasingly aligning procurement with operational outcomes: reduced air and water consumption in cooling systems, longer service life between changeouts, and greater campaign predictability. These priorities favor solutions that combine material reliability with practical usability, especially when they help plants maintain quality while managing throughput.
Supply chain and cost structure dynamics further influence competitive positioning. Producers of advanced refractories and ceramic components face the dual challenge of maintaining material consistency while managing energy-intensive processing steps and input costs. Where suppliers can streamline fabrication, stabilize batch-to-batch performance, and reduce installation complexity, they create tangible value beyond the component itself. At the same time, recent product updates from leading manufacturers indicate a clear emphasis on practical performance attributes such as zero shrinkage at high temperatures, suitability for twin-roll continuous casting, and enhanced non-stick properties for aluminum processing. These developments illustrate how commercial priorities are converging around reliability, ease of integration, and readiness for varied mill configurations. As a result, competitive advantage is increasingly determined by how well a supplier can deliver not just a part, but a solution that fits the operating environment and reduces total friction across the casting cycle.
Competitive Landscape and Leading Strategies
The market features a diverse set of players spanning specialty refractory producers, precision nozzle manufacturers, and companies with deep application focus in either aluminum or steel casting. Several firms have established strong positions by aligning product design with specific process pain points. In aluminum casting, suppliers offering complete tip assemblies designed for rapid insertion and reduced assembly effort are appealing to casthouse operators seeking to minimize setup time and variability during changeovers. In aluminum sheet, foil, and strip production using twin-roll continuous casting, companies emphasizing non-stick behavior and dimensional stability at elevated temperatures are catering to the need for consistent strip quality and reduced contact-related issues. For steel continuous casting, the most differentiated players tend to focus on flow control and secondary cooling precision, where nozzle design and spray uniformity directly influence strand quality and process productivity.
Strategic positioning among leading companies often revolves around three reinforcing advantages: material performance, application engineering, and service reliability. Material performance is foundational; zirconia-based metering nozzles and high-temperature ceramic inserts are commonly associated with erosion resistance and extended campaign life in steel casting, while aluminum silicate and ceramic fiber composites are valued where non-stick behavior and high-temperature stability matter. Application engineering is equally important because casting conditions vary widely by alloy, temperature, pour rate, and equipment geometry. Suppliers that provide interchangeable configurations, predefined installation practices, and guidance on flow control can reduce trial-and-error for buyers and improve repeatability across shifts. Service reliability completes the picture: timely availability of replacement components, predictable lead times, and technical support during qualification and troubleshooting help maintain campaign continuity, which is often more important to buyers than minor price differences.
Recent market developments reinforce the shift toward performance-led differentiation. Updates in aluminum casting nozzle and tip offerings have highlighted high-temperature calcination, non-stick characteristics, and suitability for twin-roll casting environments, reflecting an emphasis on operational consistency and reduced sticking. In steel casting, continued attention to tundish metering, ladle-to-tundish flow control, and secondary cooling spray patterns signals that precision and process stability remain central concerns. These moves suggest that companies are competing less on generic part availability and more on targeted problem solving.
The competitive landscape is evolving along multiple axes. Consolidation is plausible where scale in manufacturing, distribution, or application support can lower cost and broaden portfolio breadth, particularly for suppliers able to serve both aluminum and steel environments. At the same time, fragmentation persists because specific alloy systems, nozzle geometries, and mill configurations create room for specialized players with deep process knowledge. New entrants can still find opportunities by focusing on underserved niches, such as customized metering solutions, improved cooling spray patterns, or components designed for faster changeover in multi-alloy operations. The overall direction points toward greater segmentation by application needs and material requirements, with winners likely to be those that combine material robustness with practical usability and dependable support.
Jet Engine Nozzles Market
Future Trends and Commercial Implications
Over the next three to five years, one of the clearest trends will be continued prioritization of reliability and extended campaign performance. As metal producers face pressure to maintain quality while optimizing throughput, components that resist erosion, reduce sticking, and deliver consistent flow will gain preference. This trend favors suppliers that can demonstrate measurable improvements in service life, fewer unplanned interruptions, and stable performance across varying operating conditions. Commercially, this creates opportunities for products backed by strong field data and clear application guidance, especially when buyers can tie component performance to reduced downtime or improved yield.
A second trend will be increased attention to precision in cooling and flow control. In continuous steel casting, uniform spray patterns and controlled secondary cooling are likely to remain central to surface quality and productivity goals. In aluminum operations, the focus will likely stay on reducing contact issues and supporting smooth metal delivery across twin-roll and related casting configurations. As a result, there is commercial potential in solutions that improve process repeatability while helping facilities manage water and air usage more efficiently. Suppliers that can align nozzle design with real-world cooling and discharge requirements will be well placed to capture interest from operators seeking both quality and resource efficiency.
A third trend is the gradual move toward more integrated procurement and qualification approaches. Buyers are increasingly evaluating parts in the context of broader process goals, including changeover speed, installation consistency, and support during commissioning or troubleshooting. This creates room for differentiated offerings that reduce assembly complexity, standardize fit-up, and simplify supplier coordination across multiple casting lines. However, uncertainty remains. Raw material costs, energy intensity of high-temperature processing, and the pace of equipment upgrades in end-user facilities can influence adoption timing and margin resilience. Shifts in alloy demand, changes in domestic production philosophy, or supply interruptions can also alter purchasing patterns. Companies that build flexibility into product lines and maintain reliable supply and technical support will be better equipped to navigate these variables.
Actionable Guidance for Decision Makers
For manufacturers and producers, the priority should be to evaluate casting tips and nozzles based on total process impact rather than unit price alone. That means considering service life, installation time, flow consistency, cooling performance, and support during changeovers. Where multiple alloys or casting configurations are in use, standardizing on components that balance flexibility with predictable performance can reduce variability and simplify maintenance planning. It is equally important to align procurement with operational objectives such as surface quality, campaign continuity, and resource efficiency, then validate component choices through controlled trials that reflect actual plant conditions.
For investors, the market offers exposure to steady, demand-backed growth in enabling casting components, but differentiation will matter more than broad participation. The most compelling opportunities are likely to be found in suppliers with strong material capability, clear application focus, and the ability to reduce total friction for end-users. Evaluating track records in qualification support, supply reliability, and portfolio breadth across aluminum and steel environments can help identify businesses positioned to capture value as buyers prioritize consistency and uptime. Monitoring product updates that emphasize high-temperature stability, non-stick behavior, and precision cooling can also provide early signals of where commercial emphasis is heading.
PW Consulting
For procurement and sourcing teams, the most effective strategy is to structure evaluations around performance criteria that reflect the operating environment. This includes requesting application-specific data, comparing installation and changeover requirements, and clarifying lead times and support arrangements before committing to larger volumes. Where possible, coordinate with process engineers to ensure that component selection supports downstream goals such as strand quality, cooling uniformity, and campaign predictability. For organizations seeking a fuller picture of segment dynamics, regional patterns, and supplier-specific positioning, the complete research report provides more detailed breakdowns and tailored recommendations to support procurement planning and strategic review.
For detailed analysis of this topic, please visit the official page: Worldwide Casting Tip And Nozzle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com