

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Insulated Cup Sleeves Market: Why the 5.76% CAGR Tells a Deeper Resilience Story

The Worldwide Insulated Cup Sleeves Market: Strategic Trends and Commercial Opportunities Through 2032
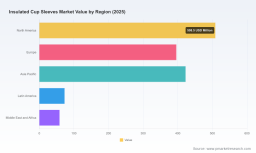
The global insulated cup sleeves market has evolved from a peripheral accessory into a strategically significant segment within the broader foodservice packaging ecosystem. Valued at USD 1,458.6 million in 2025 and projected to expand at a compound annual growth rate of 5.76 percent through 2032, the market reflects a structural shift in how hot and cold beverages are packaged, delivered, and perceived by end users. Historical revenue progression from 2020 through 2025 demonstrates consistent upward momentum, with the segment crossing the 1,400 million threshold in 2024 before accelerating into the mid-1,500 million range in 2026. The trajectory continues upward through the forecast horizon, surpassing 2,150 million by 2032, signaling sustained commercial relevance beyond short-term consumer fads.
This growth is not merely a function of volume expansion. It represents a convergence of regulatory pressure, sustainability mandates, material innovation, and shifting handling expectations across both commercial and residential channels. Insulated cup sleeves now serve dual purposes: thermal protection and brand communication, while increasingly operating as a compliance touchpoint in jurisdictions tightening rules around single-use packaging. For executives and investors, the market offers a window into how disposable food accessories are being redesigned to align with circular economy principles without sacrificing cost efficiency or user experience.
Despite the favorable trajectory, the industry faces several structural challenges that will define competitive outcomes over the next cycle. First, the transition toward higher recycled content and alternative fiber sources introduces variability in supply consistency, pricing, and performance characteristics. Manufacturers must balance sustainability targets with the physical requirements of thermal insulation, print fidelity, and stackability. Second, regulatory frameworks across Europe, North America, and parts of Asia are increasingly tying compliance costs to recyclability metrics and post-consumer content thresholds, reshaping procurement economics and pushing smaller producers into difficult positioning decisions. Third, the market remains moderately fragmented, with concentration levels indicating room for consolidation but also leaving space for niche players who can differentiate through material science, custom engineering, or regional service models. Navigating these dynamics requires more than volume scaling; it demands strategic clarity around material selection, compliance readiness, and end-user value propositions.
Key Drivers Reshaping the Insulated Cup Sleeves Market
Material Innovation and Thermal Performance Engineering
Material selection has moved from a cost-centric decision to a performance and compliance-driven strategic lever. Kraft paper and corrugated paperboard, whether sourced from virgin or post-consumer recycled fiber, continue to anchor the segment due to their balance of cost efficiency, printability, and consumer familiarity. However, manufacturers are increasingly deploying embossed architectures, textured surfaces, and engineered air-trapping geometries to enhance insulation without simply adding material weight. Embossed fiber formats, for instance, allow producers to reduce basis weight while maintaining thermal resistance, creating a direct link between design innovation and margin preservation. Water-based and polylactic acid coatings are also gaining traction as alternatives to conventional barriers, particularly where compostability or recyclability claims must be substantiated. These developments are not incremental; they are redefining the cost-performance envelope and enabling sleeve solutions that align with both handling expectations and end-of-life requirements.
Regulatory Pressure and Extended Producer Responsibility
Policy momentum is reshaping procurement behavior across multiple regions. The EU Single-Use Plastics Directive and associated Extended Producer Responsibility schemes now encompass single-use packaging items, including paper-based beverage accessories, requiring producers to finance collection and recycling infrastructure. In the United Kingdom, the expanding EPR framework for packaging introduces fees structured around recyclability and recycled content, directly influencing the economics of disposable sleeves. Similar dynamics are emerging in California through SB 54, which establishes extended producer responsibility for packaging and is steering foodservice procurement toward recyclable fiber-based formats. These regimes do not merely impose compliance costs; they alter the relative attractiveness of material choices, reward higher recycled fractions, and penalize designs that complicate recovery streams. Companies that anticipate these requirements in product architecture and sourcing strategies can convert regulatory pressure into a procurement advantage rather than a reactive expense.
Demand-Side Shifts Among Consumers and Commercial Buyers
End-user expectations are increasingly shaping sleeve design and specification. Coffee shops and cafes remain the dominant commercial channel, where sleeves function as both thermal protection and a canvas for branding, making printability, consistency, and fit critical. Household consumers represent a growing segment, driven by at-home beverage preparation, reusable cup ecosystems that still require disposable protection in certain contexts, and heightened sensitivity to tactile comfort and environmental claims. Corporate and institutional buyers add another layer of complexity, as procurement teams evaluate total cost of ownership, compliance alignment, and visibility into material provenance. Across these channels, the common thread is a demand for sleeves that perform reliably, communicate sustainability credibly, and integrate smoothly into existing cup formats without introducing friction in high-volume environments.
Supply Chain Reconfiguration and Cost Structure Dynamics
The cost structure of insulated cup sleeves is being recalibrated by fiber availability, recycled content sourcing, energy inputs, and regional manufacturing footprints. As producers increase reliance on post-consumer recycled fiber, they must manage variability in pulp quality, contamination risk, and processing requirements. At the same time, the push toward fossil-free production and lower carbon intensity is influencing facility investments and logistics decisions. Some manufacturers are positioning around localized production to reduce transport emissions and respond faster to regional compliance mandates, while others are scaling centralized capacity to optimize material purchasing and technical development. These contrasting models reflect a broader divergence in how companies are managing the trade-off between agility and scale, with implications for pricing stability and service levels across customer segments.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established packaging groups, specialized fiber innovators, and regionally focused producers. Leadership is increasingly defined not by volume alone but by the ability to align material science, sustainability credentials, and application-specific engineering. Several companies have built differentiation around distinct value propositions that illustrate where the market is heading.
One major player has expanded its portfolio around hot cup sleeves designed as accessories for single-wall paper cups, while also advancing insulated cup formats that incorporate a built-in thermal effect, reducing the need for separate sleeves in certain applications. Its emphasis on post-consumer recycled fiber and recognized forestry standards positions it at the intersection of performance and responsible sourcing. Another leading supplier has focused on deeply embossed fiber formats engineered for superior thermal insulation with reduced material consumption, emphasizing printability and a high degree of fossil-free production. This approach illustrates how design-led material use can simultaneously address cost, performance, and environmental targets. A China-based manufacturer has concentrated on custom recyclable paper sleeves compatible across common cup sizes, offering corrugated or textured designs that protect against heat or cold transfer while supporting custom printing and recycled fiber options. This model highlights the importance of application flexibility and regional customization in capturing demand across diverse foodservice configurations.
Worldwide Paper Cup Sleeve Market
Several companies have carved out strong positions in compostable and recycled-content sleeves, targeting operators and institutional buyers seeking credible end-of-life claims. One U.S.-based producer offers sleeves made from recycled paper content that are fully compostable and designed for comfortable handling across a range of cup sizes. Another focuses on sleeves made entirely from post-consumer recycled paper, aligned with sustainable foodservice applications. A Finnish manufacturer adds a premium kraft sleeve offering and insulated paper cup designs that integrate insulation into the cup itself, reducing dependence on separate sleeves in premium segments. Meanwhile, a global packaging group has advanced recyclable sleeve solutions with high post-consumer recycled content, reinforcing a circular packaging narrative across beverage applications. These varied strategies show that differentiation is increasingly multidimensional, spanning material composition, end-of-life pathway, thermal engineering, and brand trust.
Recent recognitions underscore how sustainability and performance are converging in corporate positioning. One global supplier received an industry award for a stretch sleeve solution containing up to 75 percent post-consumer recycled material and associated with significantly lower CO₂ emissions, supporting circular packaging in beverage sectors. The same company was later named Packaging Company of the Year at a major UK awards program, reflecting leadership in sustainability, innovation, and performance, including sleeve solutions. These milestones matter because they signal to procurement teams and investors that recyclable, high-recycled-content designs are moving from pilot concepts to commercially validated offerings with external validation.
Market structure is likely to continue evolving along two tracks. On one hand, consolidation and partnership will remain attractive for players seeking broader geographic coverage, integrated material sourcing, and scaled compliance capabilities. On the other hand, differentiation will protect specialized producers who can offer superior insulation per gram, credible compostability or recyclability claims, or rapid custom response for regional foodservice channels. New entrants will find opportunity not in commodity overlap but in targeted engineering, compliance-forward material choices, and service models that reduce friction for high-volume buyers. The result is a landscape where scale and specialization can coexist, but only if each player clearly owns a defensible value proposition.
Forward Outlook: Trends Shaping the Next 3–5 Years
Several interrelated trends are likely to define the insulated cup sleeves market through the early 2030s. First, design-led efficiency will become a central competitive battleground. As material costs and compliance costs rise, producers that can deliver equivalent or better thermal protection with less fiber, more precise embossing, and smarter cup-sleeve integration will capture margin and procurement preference. This trend favors companies that invest in prototyping, application testing, and close collaboration with cup manufacturers, because the most efficient solutions often emerge at the interface between cup and sleeve rather than within either component alone.
Second, compliance-aligned material procurement will shift from a defensive requirement to a sourcing advantage. Extended producer responsibility frameworks and recycled content expectations are expanding the premium on traceable fiber, lower fossil intensity, and designs that fit existing recovery streams. Buyers will increasingly treat recyclability, compostability, and recycled fraction not as marketing attributes but as procurement prerequisites. This creates opportunities for suppliers that can document content composition, provide consistent lot-to-lot quality, and align sleeve architecture with regional end-of-life infrastructure. It also raises the stakes for companies that rely on ambiguous claims or inconsistent material streams, since procurement scrutiny is likely to intensify.
Third, application segmentation will deepen as channel needs diverge. Coffee shops and cafes will continue to prioritize fit, print quality, and throughput reliability. Household consumption will reward comfort, reusability compatibility, and clarity around environmental attributes. Corporate and institutional procurement will weigh compliance documentation, total cost, and supply continuity more heavily. The practical implication is that one-size positioning will lose ground to channel-tuned offerings, with modular design platforms and configurable material options becoming more valuable than rigid standardized SKUs. The opportunity lies in building flexible production and specification systems that can serve multiple channels without sacrificing cost discipline.
These trends carry risk. If recycled fiber availability tightens or quality variability increases, cost structures could become less predictable, particularly for smaller producers. If regulatory definitions around compostability, recyclability, or recycled content diverge across regions, compliance complexity could erode the benefits of otherwise strong product designs. If cup manufacturers accelerate integrated insulation features, separate sleeve demand could shift in certain premium formats, redistributing volume rather than eliminating it. Companies that monitor these forces closely and maintain agile sourcing, design, and compliance capabilities will be better positioned to convert uncertainty into commercial advantage.
Worldwide Ice Silk Sleeves Market
Actionable Guidance for Decision Makers
For manufacturers and material suppliers, the priority is to invest in insulation efficiency and compliance-ready material streams in tandem. Reducing basis weight through embossing and structural design, expanding verified recycled content, and aligning sleeve architecture with regional recovery expectations can protect margins while strengthening procurement appeal. Equally important is building close feedback loops with cup producers and high-volume foodservice buyers, because the most valuable innovations often emerge from integrated fit, handling, and printing requirements rather than from material substitution alone.
For investors, the signal is to distinguish between commoditized scale plays and differentiated capability plays. Volume growth is real, but sustained outperformance is likely to concentrate among companies that can demonstrate credible sustainability performance, consistent quality at higher recycled fractions, and application-specific engineering that reduces total handling cost for end users. Due diligence should evaluate not only capacity and footprint but also traceability systems, regulatory readiness, and the strength of customer relationships in channels where sleeve specifications are becoming more rigorous.
For procurement teams and brand operators, the focus should shift from price-per-unit comparisons to total value across handling, compliance, and supply reliability. Sleeves that fit consistently, protect comfortably, and align with local recycling or composting infrastructure can reduce operational friction and reputational risk. Evaluating suppliers on documented material composition, print performance, and continuity of supply will become more important as specifications tighten and channel expectations diverge. Where possible, coordinating sleeve selection with cup format decisions can unlock efficiency gains that are not visible when the two are procured in isolation.
The market trajectory through 2032 suggests that insulated cup sleeves will remain a meaningful and evolving segment within foodservice packaging, shaped by material engineering, regulatory alignment, and channel-specific demand. Executives who treat the category as a strategic interface between product performance, compliance, and brand trust will be better positioned to capture the opportunities embedded in the growth path. For organizations seeking deeper segmentation, competitive benchmarking, and customized procurement or investment scenarios, the full PW Consulting research report provides the detailed data and scenario-based analysis needed to translate these market-level insights into operational decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Insulated Cup Sleeves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com