

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Polylaurolactam Market 2026–2032: Beyond the 5.6% CAGR Growth Trajectory

Strategic Trends and Commercial Opportunities in the Worldwide Polylaurolactam Market
Market Overview and Core Challenges
Sizing the Opportunity
The global polylaurolactam market has demonstrated steady expansion over the past five years, with revenue scaling from approximately $1.12 billion in 2020 to $1.49 billion in 2025. Moving forward, the trajectory points toward a continuation of this upward trend, with projected revenues reaching $2.18 billion by 2032 at a compound annual growth rate of 5.6%. This growth is not merely a function of industrial expansion but reflects a structural shift in material preferences across several high-value sectors. The market's resilience stems from polylaurolactam's unique combination of chemical resistance, flexibility, and lightweighting capabilities, which make it indispensable in applications where traditional materials fall short. The consistent upward trajectory suggests that demand drivers are deeply embedded in end-user industries rather than being purely cyclical.
Three Critical Challenges Shaping the Landscape
Despite the positive growth outlook, the industry faces several structural headwinds that will define competitive positioning over the next five years. The first challenge lies in raw material volatility. Laurolactam, the primary monomer for polylaurolactam, depends on petrochemical feedstocks such as cyclododecane derived from butadiene. Fluctuations in butadiene pricing directly cascade into laurolactam and subsequent PA12 costs, creating margin pressure and pricing uncertainty. Recent data from late 2025 indicated weak to slightly declining price trends in both Asia and Europe, reflecting broader soft chemical market conditions and subdued feedstock demand. However, this softness does not eliminate structural volatility; rather, it underscores the market's sensitivity to upstream petrochemical cycles.
PW Consulting
The second challenge involves the growing emphasis on sustainability and bio-based alternatives. Automotive OEMs have set explicit targets for 20–30% sustainable polymer content by 2030, pressuring manufacturers to transition away from fully fossil-based PA12 grades. While bio-based variants exist, scaling production while maintaining cost parity remains a significant hurdle. The regulatory and commercial push toward greener materials is not a passing trend; it is becoming a prerequisite for supply chain access in certain regions and industries. Companies that fail to adapt their product portfolios to include certified sustainable grades risk marginalization as downstream customers tighten procurement criteria.
Polycaprolactone Market
The third challenge centers on geographic capacity expansion and its impact on pricing dynamics. China has been actively expanding laurolactam and Nylon 12 production capacity, which continues to influence regional pricing and competitive intensity in Asia. This capacity build-out introduces both opportunities for localized supply chain resilience and risks of oversupply in certain market segments. The interplay between new capacity coming online and the pace of demand absorption will determine whether the market experiences healthy growth or margin compression in the near term. Companies must navigate this balance carefully, as overcapacity in one region can quickly spill over into global pricing expectations.
Key Drivers Analysis
Technological Innovation and Performance Breakthroughs
Innovation in polymer compounding and processing continues to unlock new applications for polylaurolactam, extending its relevance beyond traditional segments. Advances in extrusion and injection molding grades have improved processability and reduced cycle times, making the material more attractive to manufacturers seeking efficiency gains. In additive manufacturing, the development of optimized powder grades has enabled finer resolution and improved mechanical properties in 3D-printed components. These technological refinements are not incremental; they are expanding the addressable market by lowering adoption barriers and enabling performance outcomes that were previously difficult to achieve. Manufacturers investing in tailored grade development are finding that performance differentiation translates directly into premium pricing opportunities and longer-term customer relationships.
Regulatory and Policy Pressures
Policy frameworks are increasingly shaping procurement decisions, particularly in the automotive and industrial sectors. The push for sustainable polymer content is not limited to voluntary commitments; it is being codified into supplier qualification requirements and internal procurement standards. Regulatory attention to carbon footprint disclosure and circular economy principles is also raising the compliance bar for polymer suppliers. Companies that proactively develop bio-based grades and establish transparent lifecycle assessments are positioning themselves advantageously. The regulatory environment creates a dual dynamic: it raises the cost of compliance for laggards while offering first-mover advantages to those who can meet sustainability targets without sacrificing performance or cost competitiveness. The timing of policy implementation matters, as early alignment with emerging standards reduces the risk of sudden supply chain disruptions.
Demand-Side Shifts in End-Use Industries
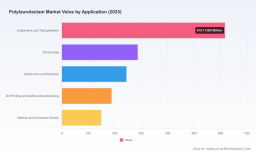
End-user industries are recalibrating their material choices based on performance, cost, and sustainability considerations. Automotive and transportation applications remain the largest demand driver, supported by lightweighting initiatives and the need for durable fuel lines, tubing, and under-the-hood components. Oil and gas applications continue to rely on PA12's chemical resistance for downhole and pipeline systems, though capital expenditure cycles in this sector introduce variability. Meanwhile, electronics and electrical applications are growing as miniaturization and thermal management requirements favor high-performance polymers. A particularly notable shift is the uptake of 3D printing and additive manufacturing, where polylaurolactam powders are gaining traction for prototyping and low-volume production runs. Medical and consumer goods applications, though smaller in absolute terms, benefit from PA12's biocompatibility and flexibility in specific formulations. The demand picture is becoming more diversified, reducing reliance on any single sector and creating multiple growth vectors.
Worldwide Lauryl Acrylate Market
Supply Chain and Cost Structure Evolution
Cost structures are being reshaped by feedstock dynamics, capacity geography, and production scale. The dependence on butadiene-derived cyclododecane means that laurolactam economics are tightly coupled to broader petrochemical markets. When butadiene prices are volatile, PA12 producers face difficult decisions around pricing, inventory management, and margin protection. At the same time, capacity expansions in Asia are altering the regional cost landscape, offering lower production costs in some areas but also intensifying competition. Integrated producers that control upstream feedstocks or operate at significant scale benefit from cost advantages and greater pricing flexibility. Conversely, smaller or more fragmented players may struggle to absorb volatility without eroding margins. The supply chain is also seeing increased attention to logistics and regional supply security, as customers seek to reduce exposure to long-distance dependencies and geopolitical disruptions.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
The market is highly concentrated, with a small group of global players commanding the majority of revenue. This concentration reflects the capital intensity of production, the technical expertise required for grade development, and the long-term supply relationships typical of high-performance polymer procurement. Leading producers have built their positions on a combination of scale, product breadth, and application-specific expertise. Evonik Industries AG anchors its strategy around large-scale PA12 production at its Marl Chemical Park, positioning itself as a reliable supplier for automotive, industrial, and 3D printing applications. Its sustainability-focused initiatives highlight efforts to align high-performance polymer production with evolving environmental expectations, reinforcing its appeal to customers prioritizing responsible sourcing. Arkema SA differentiates through its Rilsan PA12 portfolio, with particular emphasis on bio-based variants and specialty grades for tubing, fuel lines, and high-performance applications. This focus on sustainability-linked differentiation aligns directly with automotive OEM targets and positions Arkema as a strategic partner for customers navigating material transitions.
EMS-Chemie Holding AG has established a strong footprint through its Grilamid PA12 resins and compounds, targeting engineering applications across automotive, electronics, and industrial components. Its strategy emphasizes formulation flexibility and application support, enabling customers to optimize material performance for specific use cases. UBE Corporation supplies UBE Nylon 12 grades with a focus on precision molding and industrial uses, leveraging its Asia-Pacific production capabilities to serve regional demand efficiently. Its geographic positioning supports customers who prioritize responsive local supply and technical service. Wanhua Chemical operates as an integrated producer offering a full range of PA12 products for domestic and export markets. Its recent price increases of 5%–10% across its product range reflect a willingness to adjust pricing in response to market conditions and cost dynamics, signaling a more assertive commercial posture.
Market Structure Evolution
The competitive landscape is likely to evolve along multiple dimensions. Consolidation remains a plausible path as scale advantages become more pronounced and investment requirements for capacity and innovation grow. At the same time, differentiation is intensifying across product grades, sustainability credentials, and application support. New entrants face high barriers, but regional capacity additions, particularly in Asia, are altering the competitive balance by increasing supply options and pressuring pricing in certain segments. The market is not simply tightening around incumbents; it is becoming more stratified, with premium segments rewarding performance and sustainability innovation while commodity-adjacent segments face margin pressure. Companies that can navigate both dimensions—maintaining cost discipline while advancing differentiated offerings—are best positioned to capture value as the market matures. Strategic partnerships and vertical integration are also emerging as levers to secure feedstock access, improve cost predictability, and accelerate the development of sustainable grades.
Future Trends and Commercial Opportunities
Trend 1: Sustainability-Linked Product Segmentation
The market is moving toward clearer segmentation between conventional and sustainable PA12 grades. As automotive and industrial buyers embed sustainability targets into procurement, demand for bio-based and lower-carbon variants will grow even if these grades carry a premium. This creates an opportunity for producers to develop certified product lines, establish transparent lifecycle data, and secure long-term supply agreements with sustainability-conscious customers. The risk lies in the pace of cost reduction for bio-based production; if premiums remain high without clear value recognition from buyers, adoption may slow.
Trend 2: Additive Manufacturing as a Growth Accelerator
3D printing and additive manufacturing are expanding the use profile of polylaurolactam beyond traditional molding and extrusion. Powder-grade optimization, combined with growing adoption in prototyping, tooling, and low-volume production, offers a new demand channel that can be more responsive to innovation cycles than large-scale industrial procurement. Companies that invest in powder-grade development and application support for additive workflows can capture higher-margin segments and build relationships with users who may later scale into broader production applications. The uncertainty here relates to the pace of industrial adoption versus prototyping use; if additive applications remain primarily niche, the growth upside may be more limited than current enthusiasm suggests.
Trend 3: Regional Capacity Rebalancing and Pricing Dynamics
Asia's continued expansion in laurolactam and PA12 capacity will reshape regional supply and pricing dynamics. This can benefit customers seeking cost-effective supply and reduce dependency on distant sources, but it also introduces the possibility of localized oversupply and intensified competition. Producers outside Asia may need to emphasize service, technical support, and differentiated grades to maintain share, while Asian producers will need to balance capacity utilization with pricing discipline. For commercial players, this trend creates opportunities in regional supply chain optimization, import/export positioning, and strategic sourcing that accounts for shifting cost bases.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
- Accelerate the development and commercialization of bio-based and lower-carbon PA12 grades to align with automotive and industrial sustainability targets before regulatory and procurement pressures become more binding.
- Invest in grade-level differentiation for additive manufacturing and high-performance applications to capture premium segments and reduce exposure to commodity-like pricing pressure.
- Evaluate supply chain and feedstock strategies to improve cost predictability, including long-term supplier agreements, vertical integration where feasible, and regional production positioning that matches demand geography.
For Investors
- Prioritize companies with clear sustainability roadmaps and application-specific differentiation, as these traits are likely to command valuation support and customer loyalty in a market increasingly shaped by procurement criteria beyond price alone.
- Monitor capacity additions in Asia and their impact on regional pricing, as oversupply risk could compress margins for undifferentiated products while creating acquisition or partnership opportunities for well-positioned players.
- Assess exposure to additive manufacturing and high-growth application segments as potential upside drivers, but calibrate expectations against the pace of industrial adoption.
For Procurement and Supply Chain Leaders
- Diversify supplier bases to hedge against regional capacity shifts and feedstock volatility, while ensuring that alternative sources can meet performance and sustainability specifications.
- Engage suppliers early on bio-based and sustainable grade availability, securing visibility on timelines, certifications, and cost implications to avoid last-minute constraints as internal targets tighten.
- Build technical collaboration into procurement relationships, using application support and grade optimization to improve total cost of ownership rather than focusing solely on unit price.
Looking Ahead
The polylaurolactam market is at an inflection point where steady growth intersects with structural changes in sustainability expectations, application expansion, and regional capacity dynamics. For decision-makers, the imperative is to look beyond headline demand figures and understand how grade differentiation, feedstock volatility, and sustainability mandates will reshape competitive advantage. Detailed segmentation data, regional pricing analysis, and company-level benchmarking provide the granularity needed to translate these trends into actionable strategy. Readers interested in a comprehensive breakdown of market size by segment, competitive positioning, and customized scenario analysis can explore the full research report for deeper insights and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Polylaurolactam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com