

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Elastomeric Polyurethane Roof Coating: How 6.8% CAGR and Asia Pacific Growth Redefine Markets

Worldwide Elastomeric Polyurethane Roof Coating Market: Strategic Trends and Commercial Opportunities
Market Overview & Core Challenges
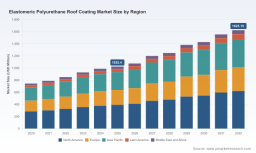
The global elastomeric polyurethane roof coating market has solidified its position as a critical segment within the broader construction chemicals and waterproofing industry. Valued at approximately 1,025.4 million USD in 2025, the market reflects a compound annual growth rate of 6.8 percent across the forecast horizon extending to 2032. This trajectory underscores a steady, resilient expansion pattern, driven by the inherent performance advantages of elastomeric polyurethane systems, including exceptional flexibility, UV resistance, crack-bridging capabilities, and seamless application profiles. The historical growth from 745.2 million USD in 2020 to the current baseline demonstrates consistent demand absorption across developed and emerging construction ecosystems, while the projected climb toward 1,625.15 million USD by 2032 signals a maturing but still highly dynamic commercial landscape.
Despite the favorable macroeconomic tailwinds, the industry currently navigates several structural inflection points that demand strategic recalibration. First, raw material price volatility remains a persistent operational headwind. The polyurethane value chain relies heavily on methyldiphenyl diisocyanate (MDI) and polyol feedstocks, both of which are subject to periodic supply-demand imbalances, energy cost fluctuations, and geopolitical trade realignments. Recent pricing data indicates that MDI prices in the United States fell to 1,890 USD per metric ton in August 2025, marking a 13 percent month-over-month decline and a 19 percent year-over-year drop. While such declines temporarily ease input cost pressures, they often coincide with broader market uncertainty and can compress margins for formulators who have already locked in higher procurement costs. Conversely, early 2026 announcements from major chemical producers signaling price increases for MDI and polyols highlight how quickly cost structures can shift, leaving manufacturers and distributors vulnerable without robust hedging strategies or flexible formulation architectures.
Second, the regulatory environment around fluorinated compounds and volatile organic compounds (VOCs) continues to tighten, particularly in North America and Europe. The U.S. Environmental Protection Agency (EPA) has advanced its hydrofluorocarbon (HFC) phasedown agenda, implementing import prohibitions on certain products containing HFCs effective January 2025 under the AIM Act Technology Transitions Program. While HFC restrictions primarily target refrigerant-based applications, the broader regulatory momentum influences polyurethane formulation philosophies, pushing formulators toward low-VOC, solvent-free, and bio-based alternatives. Compliance with evolving VOC limits, particularly in states with stringent air quality mandates, requires sustained R&D investment and can temporarily disrupt traditional product roadmaps. Third, the market exhibits moderate concentration dynamics, with the top three players capturing roughly 38.45 percent of total revenue and the top five accounting for approximately 52.1 percent. This concentration reflects the technical barriers to entry, established specification networks, and long-standing contractor relationships that incumbents have cultivated. However, it also creates space for specialized challengers and regional specialists who can differentiate through niche performance claims, localized service models, or faster customization cycles.
These challenges are not insurmountable, but they do reframe the competitive calculus. Companies that treat raw material volatility as a purely reactive cost issue rather than a strategic sourcing and formulation opportunity risk lagging behind peers who build flexibility into their supply chains and portfolio architectures. Similarly, regulatory tightening is best viewed not as a compliance burden but as a catalyst for product modernization and market differentiation. The market's expansion to 1,625.15 million USD by 2032 will not be evenly distributed; it will accrue to organizations that can align product innovation, regulatory readiness, and supply chain resilience with the evolving requirements of specifiers, contractors, and building owners.
Key Growth Drivers
Technological Innovation and Formulation Advancements
The core performance proposition of elastomeric polyurethane roof coatings continues to be reinforced by targeted technological advances. Formulators are increasingly differentiating through aliphatic versus aromatic system architectures, moisture-cure versus two-component curing mechanisms, and the integration of UV-stable top coats that extend service life on exposed substrates. The shift toward low-odor, low-VOC, and solvent-free formulations addresses both regulatory pressure and on-site application preferences, particularly in urban retrofits where ventilation constraints and occupant sensitivity limit the use of high-solvent products. Product line expansions that pair aromatic base coats with aliphatic top coats exemplify a practical engineering approach: the base coat delivers adhesion, crack-bridging, and moisture tolerance, while the top coat provides long-term UV stability and color retention. Recent specification updates from industry participants illustrate how these technical nuances translate into commercial value. In mid-2025, a major coating manufacturer released updated restoration specification guidance for elastomeric polyurethane systems applied over ethylene propylene diene monomer (EPDM) membranes, reinforcing the role of compatible, high-performance top coats in extending the service life of existing roof assemblies. Shortly thereafter, the same company updated availability and specification details for its aromatic base coat and aliphatic top coat systems in standard pack sizes, signaling a focus on specification clarity and contractor accessibility. Such moves highlight how formulation precision, specification support, and packaging flexibility collectively strengthen market positioning.
Policy, Regulation, and Building Performance Mandates
Regulatory and policy environments are reshaping demand patterns by elevating the importance of durability, sustainability, and indoor air quality in roof restoration decisions. Building code updates, energy efficiency targets, and local air quality regulations are pushing specifiers toward coatings that minimize VOC emissions while maintaining elongation, tensile strength, and reflectivity over extended service intervals. The ongoing HFC phasedown and related technology transition initiatives may not directly govern elastomeric polyurethane coatings in all cases, but the regulatory trajectory reinforces a broader market expectation: building materials must demonstrate environmental responsibility without compromising performance. This expectation advantages formulators that can document low VOC content, reduced odor profiles, and compatibility with green roof assemblies or cool roof reflectance goals. Additionally, public infrastructure spending and municipal retrofit programs increasingly favor liquid-applied, seamless waterproofing systems that reduce leak pathways and minimize disruption during application. The alignment between regulatory direction and product capability creates a durable demand pull, particularly in regions where aging roof stock and stringent performance standards coincide.
Demand-Side Shifts in Commercial and Industrial Sectors
End-user behavior is evolving along two principal axes: lifecycle cost consciousness and maintenance minimization. Commercial building owners and facility managers are increasingly treating roof coatings as a capital-efficient alternative to full membrane replacement, especially where structural deck conditions remain sound and the primary failure modes involve surface degradation, seam fatigue, or minor cracking. Elastomeric polyurethane systems appeal in this context because they conform to substrate movement, bridge hairline cracks, and reduce the likelihood of water intrusion without the demolition and disposal costs associated with tear-off projects. In industrial facilities, heavy mechanical traffic, chemical exposure, and thermal cycling demand coatings that combine flexibility with abrasion resistance and chemical tolerance. The market's application mix reflects this reality, with commercial buildings representing the largest demand pool, followed by residential construction and industrial facilities. Residential demand is gaining traction as homeowners and multifamily property managers seek cost-effective weatherproofing solutions that extend roof service life and improve energy performance. Across these segments, the specification decision is increasingly influenced by total installed cost, downtime reduction, and long-term maintenance predictability rather than initial material price alone.
Supply Chain Dynamics and Cost Structure Evolution
The polyurethane feedstock landscape is undergoing a period of recalibration that will influence competitive positioning through the forecast period. Global MDI and TDI prices remained broadly stable through 2025, with a cautious outlook for stabilization in 2026 driven by supply-side adjustments. This stability provides a window for formulators to optimize formulation economics, lock in supplier agreements, and invest in alternative feedstock strategies without the urgency of acute price spikes. However, trade policy introduces a significant variable. The United States has imposed escalating tariffs on Chinese-origin MDI, starting at 30 percent and reaching 145 percent, with potential further antidumping duties under review through March 2026. These measures affect polyurethane feedstock costs and may restructure sourcing patterns, encouraging regional supply diversification, inventory buffering, and closer integration with non-affected feedstock sources. The interplay between feedstock price stabilization and tariff-driven cost pressure creates a bifurcated operating environment: companies with diversified supplier bases, transparent cost pass-through mechanisms, and agile formulation portfolios are better positioned to maintain margin integrity, while those reliant on single-source or tariff-exposed supply chains face greater exposure to cost shocks. This dynamic also elevates the strategic importance of bio-based polyols and alternative isocyanate pathways as medium-term levers for supply resilience and sustainability storytelling.
Competitive Landscape & Leading Strategies
The competitive architecture of the elastomeric polyurethane roof coating market is defined by a blend of multinational specialty chemical groups, focused regional manufacturers, and application-oriented solution providers. This mix produces a landscape where technical credibility, specification relationships, and service reliability often outweigh pure price competition. Several incumbent profiles illustrate the strategic diversity shaping the market.
Sika Corporation maintains a broad, globally integrated platform spanning liquid-applied roofing and waterproofing systems. Its product architecture includes single-component low-odor polyurethane roof coatings and two-component, fast-curing, solvent-free base coats designed for crack-bridging and elastomeric performance. Sika's strategic positioning rests on scale, specification depth, and the ability to offer compatible resin systems across multiple waterproofing platforms. This breadth supports large-scale commercial and infrastructure programs where consistent performance documentation, technical service, and supply reliability are critical differentiators. Polycoat Products has carved a focused position around polyurethane coatings and elastomer solutions for waterproofing, emphasizing UV resistance, durability, and waterproofing performance for roof and deck applications. Its strategy highlights specialization: by concentrating on elastomeric polyurethane membranes and coatings for demanding substrates, Polycoat builds reputation equity among contractors and specifiers who prioritize application-specific performance over broad portfolio breadth.
Inland Coatings, Inc. exemplifies a specification-driven, product-clarity approach. Its AldoThane series pairs aromatic base coats with aliphatic UV-stable top coats to deliver seamless, flexible waterproof membranes across diverse roof substrates. Recent activity underscores the importance of specification support and product availability: updated specifications for restoration over EPDM membranes and refreshed availability details for core product sizes demonstrate how incumbents reinforce market presence by reducing specification friction and ensuring reliable access to proven systems. Tremco Commercial Sealants & Waterproofing brings a complementary angle through one-part moisture-triggered polyurethane roof coatings and exploration of bio-based polyurethane options for reinforced liquid-applied roofing systems. This trajectory signals a dual emphasis on application convenience and sustainability-aligned innovation, appealing to project teams that value simplified application logistics alongside evolving environmental expectations.
Other participants deepen the market's regional and application-specific texture. Urethane Polymers International, Inc. focuses on elastomeric single-component systems engineered for low-slope roofing under heavy mechanical and pedestrian traffic, an area where abrasion resistance and recoatability are decisive. Karnak Corporation and Stockmeier Urethanes USA supply elastomeric polyurethane coatings that serve as practical, specification-friendly options for restoration and maintenance programs. American WeatherStar emphasizes high-solids, moisture-cure formulations primarily for sprayed polyurethane foam roofing protection and related commercial substrates, aligning product design with the specific thermal and protective needs of foam-based assemblies. In parallel, manufacturers such as Hebei Ruide Building Waterproof Material Co., Ltd. reflect the broader internationalization of supply capability, producing polyurethane roof coatings with an emphasis on durability and performance in elastomeric applications, which contributes to cost-competitive pressure and expanding option sets for price-sensitive markets.
The market's evolution is trending toward both consolidation of technical authority and fragmentation of niche advantage. On one hand, larger players with integrated R&D, global supply networks, and extensive specification libraries are well positioned to capture share in complex commercial and infrastructure programs. On the other hand, specialized manufacturers that deliver clear performance claims, rapid customization, and strong regional service can defend and expand their positions by reducing specification risk for contractors and building owners. New entrants and smaller formulators are most likely to succeed when they target underserved substrate types, specific climate durability requirements, or application formats that larger portfolios treat as secondary. The recent product and specification activity across several incumbents also suggests a market where clarity of use cases, compatibility documentation, and availability matter as much as raw performance metrics. Companies that streamline the path from specification to procurement to application will capture disproportionate value in a market where installation quality and long-term service life are central to customer satisfaction.
Future Outlook & Strategic Implications
Over the next three to five years, the elastomeric polyurethane roof coating market is likely to trend along three reinforcing directions. First, low-VOC, solvent-free, and bio-based formulation pathways will move from differentiating features to baseline expectations in many specification contexts. As regulatory momentum continues and contractor/occupant sensitivity to odor and emissions grows, formulators that can deliver strong elongation, adhesion, and UV stability within constrained VOC profiles will secure preferential positioning in commercial and institutional bids. This trend creates commercial opportunity for companies that invest early in formulation validation, performance documentation, and specifier education, particularly where green building programs and local air quality rules intersect.
PW Consulting
Second, supply chain reconfiguration will become a more explicit competitive lever. Tariff dynamics on certain MDI sources, combined with periodic feedstock price volatility, will encourage regional sourcing diversification, strategic inventory positioning, and closer collaboration with suppliers on forecasting and allocation. Organizations that build transparent cost-pass-through frameworks and maintain formulation flexibility will be better equipped to manage margin pressure without sacrificing specification credibility. This environment also elevates the value of alternative feedstock strategies, including bio-based polyols and regionally balanced supply mixes, both as cost-risk mitigation tools and as sustainability narrative enhancers.
Third, the restoration and maintenance segment will expand as a share of total demand, driven by aging roof stock, capital constraints, and the attractiveness of liquid-applied systems that avoid tear-off disruption. Elastomeric polyurethane coatings are well aligned with this shift because they accommodate substrate movement, bridge cracks, and extend service life with comparatively low installation intrusion. Commercial buildings will remain the dominant application pool, but industrial facilities and residential multifamily projects offer meaningful upside where durability, traffic resistance, and weatherproofing performance are prioritized. The opportunity lies in pairing product performance with specification support, compatibility guidance, and field service that reduces installation risk and protects long-term outcomes.
Potential risks and uncertainties deserve attention. Feedstock cost volatility can reemerge quickly, especially if energy markets shift or trade measures intensify, compressing margins for companies without flexible procurement or pricing strategies. Regulatory trajectories may accelerate in certain jurisdictions, creating uneven compliance burdens and requiring formulation agility across regions. Competitive intensity could increase if new entrants or imported supply press price points in price-sensitive segments, potentially eroding differentiation if incumbents rely too heavily on historical specification relationships. Finally, macroeconomic fluctuations in construction activity can affect the timing and scale of retrofit programs, making demand forecasting more variable. These uncertainties do not diminish the market's growth potential, but they reinforce the importance of scenario planning, supply resilience, and product-portfolio flexibility.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align formulation roadmaps with emerging specification expectations while building supply chain options that reduce exposure to feedstock and tariff shocks. Invest in low-VOC, solvent-free, and compatible base/top-coat system architectures, and pair product launches with clear compatibility documentation and specification support that reduces risk for contractors and specifiers. Diversify feedstock sourcing, evaluate alternative polyol and isocyanate pathways where feasible, and develop pricing mechanisms that preserve margin integrity during cost swings without undermining bid competitiveness.
Polyurea Coatings Market
For investors, focus on companies that demonstrate technical differentiation, specification momentum, and supply resilience rather than those competing primarily on price. Look for portfolios that combine proven elastomeric performance with clear regulatory readiness and application flexibility, and assess whether target companies have strong regional service capabilities and repeatable specification wins in commercial restoration and industrial maintenance. In a market projected to expand steadily through 2032, sustainable advantage will accrue to firms that can convert product performance into specification trust and installation reliability.
For procurement and asset owners, prioritize total lifecycle value over initial material cost. Evaluate coatings based on compatibility with existing substrates, UV stability, elongation and crack-bridging performance, VOC profile, and the quality of specification and field support available from the manufacturer. Where possible, consolidate product relationships with suppliers that can provide consistent performance documentation, clear application guidance, and reliable availability, reducing project risk and protecting long-term roof performance.
As the market evolves, detailed segmentation data, regional demand nuances, and customized strategic guidance become increasingly valuable for precise decision-making. PW Consulting's full research report provides deeper breakdowns and tailored recommendations for manufacturers, investors, and procurement teams seeking to navigate this dynamic landscape with confidence.
Roof Coating Market
For detailed analysis of this topic, please visit the official page: Worldwide Elastomeric Polyurethane Roof Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com