

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Chassis-by-Wire Market: Why 19.5% CAGR and Brake-by-Wire Shift Change Everything

The Chassis-by-Wire Revolution: Strategic Trends and Commercial Opportunities in a Rapidly Evolving Market
Market Current Status & Core Challenges
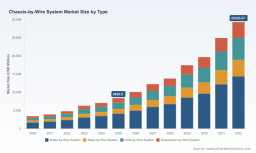
The global chassis-by-wire system market has entered a phase of rapid expansion, driven by the convergence of electrification, software-defined vehicle architectures, and escalating demands for advanced driver assistance capabilities. Valued at approximately USD 8.4 billion in 2025, the sector has demonstrated a compound annual growth rate of 19.5 percent over the recent historical period and is projected to sustain this aggressive trajectory through the forecast horizon ending in 2032. This growth reflects a structural shift away from hydraulic and electromechanical linkages toward fully digital, electronically mediated control systems across braking, steering, suspension, and transmission interfaces. The transition is not merely incremental; it represents a foundational rearchitecture of how vehicles interpret driver intent, manage dynamic stability, and interface with autonomous driving stacks.
Despite the robust growth trajectory, the industry faces several critical inflection points that will determine which players capture sustainable value. First, functional safety and redundancy remain paramount. Chassis systems are inherently safety-critical, and replacing mechanical fail-safes with electronic architectures demands rigorous validation, dual-redundant control loops, and fail-operational designs. The absence of universally harmonized standards outside major regulatory jurisdictions introduces compliance complexity and slows cross-market product rollouts. Second, the integration depth required to realize the full value of chassis-by-wire architectures is reshaping supplier-OEM relationships. Standalone actuators are increasingly insufficient; OEMs demand cohesive software platforms, real-time vehicle dynamics control, and seamless connectivity with domain controllers. Suppliers that cannot deliver integrated, software-enabled solutions risk commoditization. Third, the supply chain for high-reliability power electronics, precision sensors, and safety-certified semiconductors remains constrained. Scaling production while maintaining ASIL-D compliance creates bottlenecks, particularly as multiple OEMs and tier suppliers simultaneously accelerate commercialization timelines.
Key Drivers Shaping the Market
Technological innovation stands as the primary catalyst for chassis-by-wire adoption. The maturation of high-response electric actuators, low-latency communication buses, and advanced torque and position sensors has enabled steering, braking, and suspension systems to operate with precision previously achievable only through mechanical linkages. More importantly, these components are now being bundled into cohesive platforms that support over-the-air updates, predictive stability control, and seamless integration with advanced driver assistance systems. The shift toward software-defined vehicles amplifies this effect, as chassis functions become programmable layers rather than fixed hardware assemblies. Suppliers that have historically operated in isolated component silos are now competing on the basis of system-level integration, algorithmic control, and lifecycle software support.
Regulatory and standardization developments are simultaneously accelerating and shaping deployment pathways. Several major markets have moved to explicitly accommodate steer-by-wire and brake-by-wire architectures within their regulatory frameworks, provided that systems meet stringent functional safety and cybersecurity requirements. The push toward ISO 26262 compliance at ASIL-D levels, combined with cybersecurity standards such as ISO/SAE 21434, has raised the bar for entry but also created defensible moats for established players with proven validation pipelines. International standardization bodies are actively developing guidelines that clarify safety expectations for steer-by-wire systems in passenger and light commercial vehicles, offering a more predictable compliance landscape. At the same time, regional regulatory bodies have begun publishing national standards that explicitly incorporate steer-by-wire requirements, with participation from both OEMs and component suppliers. This institutional recognition reduces ambiguity for engineers and procurement teams, encouraging broader adoption beyond pilot programs.
On the demand side, consumer and fleet behavior is reinforcing the technology shift. Electrified platforms inherently free up packaging constraints associated with hydraulic lines and mechanical linkages, making by-wire systems more attractive from both a weight and design flexibility standpoint. Automakers pursuing advanced maneuvering features, reduced cabin intrusion, and enhanced driver comfort are increasingly viewing chassis-by-wire as a strategic enabler rather than a compliance checkbox. In the commercial segment, fleet operators and logistics-focused OEMs are evaluating digital chassis architectures for improved energy efficiency, predictive maintenance, and alignment with higher levels of automated operation. The commercial vehicle segment, while smaller in absolute terms than passenger cars, is gaining momentum as operators seek differentiated reliability and total cost of ownership profiles.
Supply chain and cost structure dynamics are also evolving. The transition to by-wire architectures redistributes value toward electronics, software, and system integration, while reducing reliance on traditional hydraulic components and metal-intensive linkages. However, the initial capital intensity of developing fail-operational architectures, dual-redundant controllers, and safety-certified microcontrollers remains high. Suppliers are responding by offering modular portfolios that span electric, hydraulic, and hybrid actuation options, allowing OEMs to phase adoption based on vehicle segment, safety certification timelines, and cost targets. Semiconductor and power electronics availability continues to influence production pacing, but strategic partnerships between chipmakers, tier suppliers, and OEMs are gradually stabilizing the supply base. The emergence of integrated chassis control platforms is also creating economies of scale, as shared software stacks and common sensor suites reduce per-unit engineering costs across vehicle programs.
Technology Innovation and System-Level Integration
The competitive advantage in chassis-by-wire is increasingly defined by how effectively suppliers can combine actuation hardware with control software, safety architecture, and vehicle dynamics algorithms. Companies that offer one-box or tightly integrated solutions are gaining traction with OEMs seeking to simplify wiring harnesses, reduce part counts, and accelerate software-defined chassis development. The ability to deliver steer-by-wire systems with stowable column options, electro-mechanical brake architectures, and integrated suspension actuation under a unified software layer is becoming a differentiator in premium and technology-forward vehicle segments. This integration push is also driving collaboration across the value chain, with semiconductor suppliers playing a more visible role in enabling high-safety motor control and real-time processing for by-wire applications.
PW Consulting
Policy, Standards, and Regulatory Clarity
Regulatory evolution is acting as both an enabler and a gatekeeper. As international and regional standards begin to articulate explicit requirements for steer-by-wire and brake-by-wire systems, engineers gain clearer design targets and validation pathways. The allowance of steer-by-wire architectures without mechanical backup under defined conditions in certain regulatory frameworks has reduced a long-standing barrier to full by-wire deployment. Simultaneously, the expectation of dual-controller architectures, redundant power supplies, and fail-operational behavior reinforces the need for robust engineering and testing capabilities. Suppliers with established functional safety certification records and proven cybersecurity processes are positioned to benefit from this regulatory maturation, while newer entrants must navigate a steep compliance curve.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated group of multinational suppliers with deep chassis engineering heritage, complemented by regional specialists and technology-focused entrants. The top three players account for a substantial share of industry revenue, while the top five collectively represent a majority of total market value. This concentration reflects the capital intensity, safety validation requirements, and long qualification cycles inherent to chassis-by-wire systems. However, the landscape is dynamic, with consolidation, partnership formation, and targeted acquisitions reshaping competitive positions.
Leading suppliers are pursuing distinct strategic playbooks. Continental AG has positioned itself around integrated electronic braking and chassis control solutions tailored for software-defined vehicles, emphasizing system-level coherence across brake-by-wire and broader chassis functions. ZF Friedrichshafen AG has expanded its portfolio to cover comprehensive brake-by-wire and steer-by-wire offerings, including one-box systems and a dedicated chassis solutions division that addresses light vehicles and software-defined chassis architectures. In mid-2025, ZF unveiled a broad brake-by-wire portfolio encompassing electric, hydraulic, and hybrid options, signaling flexibility to accommodate varying OEM safety strategies and cost targets. Robert Bosch GmbH continues to leverage its full chassis integration expertise, developing steer-by-wire and brake-by-wire systems that align with ADAS, automated driving, and electrified platform requirements.
Nexteer Automotive has built a focused steer-by-wire and brake-by-wire narrative, offering stowable column steer-by-wire options and an electro-mechanical brake system aimed at motion control and software-defined chassis integration. In 2025, the company launched its electro-mechanical brake system to enhance safety, comfort, and serviceability while reinforcing chassis-by-wire integration. Shortly thereafter, it achieved ASIL D functional safety certification for its steer-by-wire system with multi-layer redundancy and participated actively in China’s chassis-by-wire standards development. Nexteer’s engagement in Chinese standardization efforts, alongside supply of steer-by-wire and brake-by-wire systems to multiple domestic OEMs, illustrates how regional market access and standards influence strategy. Meanwhile, Li Auto implemented combined steer-by-wire and brake-by-wire in its L9 Livis model under a “big chassis” architecture, with subsequent deployments from other Chinese OEMs, signaling rapid commercial integration in one of the most active electrification markets.
Server Chassis Market
Regional and technology specialists are carving niches that complement the larger players. JTEKT Corporation specializes in steer-by-wire systems and chassis components, scaling production for EV and autonomous platforms. Schaeffler AG is advancing steer-by-wire and integrated actuation for vehicle motion control, while thyssenkrupp AG focuses on steer-by-wire with innovative feedforward control and vehicle motion control integration that operates independently of traditional steering column infrastructure. Kongsberg Automotive has emphasized fail-operational steer-by-wire systems, strengthened through the acquisition of Chassis Autonomy SBA AB to target autonomous and commercial vehicle applications. Infineon Technologies AG supplies the underlying chipsets and semiconductors that enable high-safety steer-by-wire and chassis-by-wire motor control, highlighting the strategic importance of the semiconductor layer in this ecosystem.
The market trajectory points toward continued consolidation at the system-integration tier, as OEMs prefer fewer, deeper partnerships that can deliver validated, software-enabled chassis platforms. At the same time, differentiation is intensifying in areas such as fail-operational architecture, cybersecurity, regional standards alignment, and packaging flexibility. New entrants with strong software stacks, specialized redundancy designs, or cost-competitive actuation technologies may find opportunities in commercial vehicles, autonomous shuttles, or specific regional markets where certification pathways are clearer and deployment cycles are shorter. The overall pattern is one of convergence around integrated platforms, paired with ongoing fragmentation in specialized capabilities and regional go-to-market strategies.
Future Trends and Commercial Opportunities
Over the next three to five years, the most consequential trend will be the mainstreaming of software-defined chassis architectures that treat steering, braking, and suspension as programmable, data-rich subsystems rather than isolated hardware. As more OEMs deploy combined steer-by-wire and brake-by-wire configurations, the value pool will shift from component supply toward system integration, control algorithms, and lifecycle software management. Commercial opportunities will accrue to suppliers that can offer validated redundancy, rapid calibration tools, and OTA-capable platforms that reduce time-to-market for next-generation vehicle programs. Companies that bridge the gap between component performance and vehicle dynamics optimization will be well positioned to capture premium pricing and longer-term service relationships.
A second trend is the convergence of chassis-by-wire adoption with higher levels of automated driving and commercial fleet electrification. As passenger cars and light commercial vehicles incorporate more advanced driver assistance and partial automation features, the need for precise, latency-sensitive chassis control will intensify. This creates opportunities for fail-operational steer-by-wire systems, integrated vehicle motion control, and architectures that simplify the interface between chassis actuators and autonomy stacks. The commercial vehicle segment, while historically slower to adopt, may accelerate as operators seek energy efficiency, predictable maintenance schedules, and platform commonality across fleets. Suppliers that tailor redundancy and validation approaches to commercial duty cycles, rather than simply adapting passenger car solutions, can open a differentiated niche.
A third trend involves regulatory and standards harmonization reducing deployment friction across markets. As international guidelines and national standards clarify safety expectations for steer-by-wire and brake-by-wire systems, engineering teams will face fewer ambiguous compliance questions, and OEMs will be more willing to commit to by-wire architectures in volume programs. This trend favors suppliers with mature functional safety processes and established cybersecurity frameworks, while also lowering barriers for regional players that can align quickly with local standards. The downside risk is that rapid regulatory evolution can still create uneven compliance requirements across jurisdictions, forcing suppliers to maintain multiple validation tracks. Additionally, semiconductor availability, cost volatility in power electronics, and the engineering complexity of fail-operational designs will continue to temper the pace of adoption in cost-sensitive segments. Strategic flexibility, modular portfolios, and clear safety case documentation will be essential to navigate these uncertainties.
Chassis Sensor Market
Strategic Recommendations for Decision Makers
For vehicle manufacturers and platform architects, the priority is to treat chassis-by-wire as a system-level capability rather than a components upgrade. Selecting partners that can deliver integrated steer-by-wire and brake-by-wire solutions with proven ASIL-D functional safety, fail-operational redundancy, and software-defined integration will reduce program risk and accelerate time-to-market. Aligning hardware choices with broader software architecture plans, including OTA capability and vehicle dynamics control strategies, will determine whether by-wire investments translate into competitive differentiation or merely compliance.
For investors and strategic planners, the opportunity lies in identifying suppliers and technology enablers with defensible safety validation pipelines, scalable redundancy architectures, and strong positions in emerging standardization processes. Companies that combine actuation hardware expertise with software control capabilities, or that provide critical semiconductor and sensor layers for high-safety chassis applications, are likely to capture disproportionate value as the market expands. Monitoring regional standards development and early commercial integrations in leading EV markets can provide leading indicators of volume adoption and partnership shifts.
For procurement and supply chain leaders, diversification and qualification strategy are essential. Given the safety-critical nature of chassis-by-wire systems, relying on a single source for redundant controllers, power electronics, or actuator assemblies introduces concentration risk. Building qualified secondary sources, aligning on cybersecurity and functional safety documentation requirements early, and securing visibility into semiconductor and power electronics roadmaps will help stabilize production schedules. Engaging with suppliers that offer modular electric, hydraulic, and hybrid options can provide flexibility to balance cost, safety certification timelines, and vehicle segment requirements.
Given the pace of technical evolution, regulatory change, and commercial integration activity, decision makers benefit from detailed, segment-level intelligence that maps supplier capabilities, regional standards trajectories, and deployment timelines to specific vehicle programs. Access to comprehensive market research and customized analysis can clarify which architectures, partnerships, and geographic pathways offer the strongest risk-adjusted opportunity in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Chassis-by-Wire System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com