

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
NIV Masks Market: 4 Forces Driving $4.89B Growth by 2032

Strategic Trends and Commercial Opportunities in the Worldwide Non-invasive Ventilation Masks Market
Market Overview: Navigating a Transforming Respiratory Care Landscape
The global non-invasive ventilation (NIV) masks market is experiencing a period of sustained expansion, driven by evolving respiratory care needs and a shifting clinical paradigm toward less invasive treatment modalities. Market valuation has grown steadily from 2020 through 2025, reflecting consistent demand across healthcare settings. The trajectory from 2026 to 2032 indicates continued appreciation, supported by expanding indications, aging demographics, and technological refinement. A compound annual growth rate of 6.21 percent positions the category as a resilient segment within the broader respiratory devices ecosystem, with revenue measured in millions of U.S. dollars.
Revenue distribution reveals that North America continues to represent the largest regional share, followed by Europe and Asia Pacific. The Americas benefit from mature reimbursement frameworks, high adoption of home-based respiratory therapies, and a well-established hospital procurement infrastructure. Europe maintains a strong foothold through structured clinical guidelines and broad access to non-invasive ventilation in both acute and chronic care pathways. Asia Pacific is increasingly contributing to growth momentum as healthcare systems scale capacity, respiratory disease prevalence rises, and access to advanced ventilation technologies improves across urban and semi-urban facilities. Latin America and the Middle East and Africa, while smaller in absolute terms, are developing markets where infrastructure investments and disease burden are gradually expanding the addressable patient base.
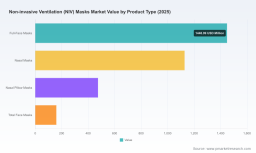
On the product side, full-face masks lead in revenue contribution, reflecting their broad application in acute and chronic non-invasive ventilation scenarios where secure sealing and high-pressure tolerance are essential. Nasal masks form a substantial second category, favored for patient comfort and suitability in longer-duration therapy. Nasal pillow masks and total face masks represent smaller but strategically important sub-segments, each addressing distinct clinical workflows and patient preferences. From an end-user perspective, hospitals and clinics remain the dominant application environment, driven by acute care demand and institutional procurement cycles. Home healthcare constitutes a significant and growing share, underscoring the shift toward decentralized respiratory management. Ambulatory care centers represent a more niche but expanding channel, particularly in settings that emphasize outpatient respiratory support and early discharge pathways.
Sleep Apnea Masks Market
Market structure is moderately concentrated, with a small group of leading manufacturers capturing a majority of revenue. This concentration reflects the technical barriers associated with mask design, sealing performance, material quality, and regulatory clearance requirements. At the same time, the presence of specialized and regional players indicates an industry in which differentiation through ergonomics, patient comfort, and clinical-specific configurations remains viable. Several key challenges are shaping the current market inflection point. First, product fit and patient adherence continue to be persistent clinical concerns; even advanced mask designs must contend with variability in facial anatomy, pressure tolerance, and prolonged wear comfort. Second, the balance between single-use clinical efficiency and cost containment is becoming more pronounced, particularly as hospitals evaluate total cost of care rather than unit price alone. Third, regulatory pathways and reimbursement frameworks are evolving in ways that influence both product development priorities and market access timing, especially in the United States where coverage criteria and device classification directly affect adoption velocity.
For executives and investors, the core implication is that the market is expanding, but growth is not uniformly distributed across products, channels, or regions. Competitive success depends on aligning design, clinical evidence, and access strategy with the environments where non-invasive ventilation is most actively deployed.
PW Consulting
Key Growth Drivers: Technology, Policy, Demand, and Supply Chain Dynamics
Several interconnected forces are accelerating the expansion of the NIV masks market. The first and most visible is technological innovation in mask design and interface engineering. Manufacturers are increasingly focusing on cushion materials, seal stability under varying pressure conditions, and headgear architectures that reduce pressure points while preserving therapeutic effectiveness. Medical-grade silicone remains a common interface material because of its flexibility, hypoallergenic profile, and ability to conform to facial contours for effective sealing. This material foundation supports ongoing refinement rather than radical substitution, enabling manufacturers to iterate on comfort and performance without compromising clinical reliability. Recent product introductions illustrate this trajectory, including mask portfolios that span nasal, full-face, and specialized configurations, with interchangeable components designed to adapt to different therapy setups. Such modularity is particularly relevant in hospital environments, where clinicians value flexibility across patient types and ventilation modes.
A second driver is the evolving policy and regulatory environment. In the United States, NIV masks are classified as Class II devices under 21 CFR 868.5895 and require 510(k) clearance for marketing as accessories for non-invasive ventilation. This regulatory structure creates a defined pathway for market entry, but it also places a premium on timely clearance, clinical differentiation, and documentation of intended use. Recent regulatory activity underscores how actively the competitive field is moving. Clearances have been obtained for hospital-focused vented and non-vented mask ranges, as well as for families of NIV masks intended for single-patient use in the hospital environment. These approvals matter because they expand the set of commercially available options and can shift procurement decisions by giving clinicians more choices in fit, circuit compatibility, and infection-control preferences. Regulatory momentum also signals to the market that non-invasive ventilation interfaces remain a priority category for device innovation and review.
The third driver lies on the demand side, where clinical practice and care-setting trends are reshaping adoption. There is a continuing shift toward earlier and broader use of non-invasive ventilation in both acute and chronic respiratory failure management, particularly when clinicians seek to avoid intubation or support patients outside the intensive care unit. At the same time, home-based respiratory care is becoming more central to long-term management strategies. CMS updated the National Coverage Determination for non-invasive positive pressure ventilation in the home for chronic respiratory failure consequent to COPD, expanding coverage for respiratory assist devices and home mechanical ventilators with revised criteria. Notably, the updated framework no longer requires overnight oximetry in certain cases and uses clinical thresholds such as PaCO2 ≥ 52 mmHg or documentation that sleep apnea is not the predominant cause. This kind of reimbursement evolution can broaden the eligible patient population and strengthen the economic case for home-based non-invasive therapy, indirectly supporting demand for appropriate masks and interfaces over time.
Non-invasive Ventilation Masks Market
A fourth driver is the changing supply chain and cost structure environment. Healthcare providers are increasingly attentive not only to device performance but also to the downstream economics of therapy, including consumables, staffing burden, and infection-control workflows. This has increased interest in products that can simplify setup, improve seal consistency, and reduce remasking or adjustment time. For manufacturers, cost pressures are encouraging disciplined material selection, manufacturing efficiency, and design choices that balance performance with scalability. The market is also seeing interest in products tailored to pediatric and infant care, where specialized sizing and comfort features can address a distinct clinical need and create opportunities for differentiation. Newer catalog additions targeting infants and children highlight how comfort-oriented engineering, swivel elbow designs, and adjustable fitting mechanisms are being used to meet the requirements of smaller patient populations.
Taken together, these drivers suggest that the NIV masks market is being shaped less by a single breakthrough and more by cumulative improvement across materials, regulatory readiness, reimbursement alignment, and clinical workflow. Companies that can integrate these elements into coherent product and access strategies are better positioned to convert clinical need into durable commercial traction.
Competitive Landscape: Positioning, Differentiation, and Evolving Market Structure
The competitive environment in the NIV masks market is defined by a combination of established multinational manufacturers and specialized players with strong clinical or regional focus. ResMed maintains a prominent position through hospital non-vented full-face NIV masks designed for single-use, with product options engineered to seal effectively under high pressures up to 40 cm H2O. This emphasis on high-pressure performance and single-use design aligns with acute-care requirements where seal reliability and infection-control considerations are paramount. Fisher & Paykel Healthcare offers a broad portfolio that includes full-face masks with vented and non-vented configurations in multiple sizes, as well as under-nose, bridge-free designs compatible with single-limb circuits. Its recent FDA 510(k) clearance for a hospital vented full-face mask range illustrates a strategy centered on expanding clinically relevant options and strengthening compatibility with common ventilation circuits. Philips Respironics contributes oro-nasal and face mask solutions with headgear and cushion designs intended for hospital-based non-invasive ventilation, reinforcing its presence in institutional care settings. Hamilton Medical has expanded its mask portfolio across nasal, full-face, and specialized configurations with interchangeable elbows and multiple sizes for adult and pediatric patients, reflecting a product architecture built around adaptability across therapy options.
Beyond these larger platforms, a second tier of competitors brings distinct value propositions. Dräger emphasizes customizable NIV masks as part of complete non-invasive ventilation solutions for acute care, with a focus on seal and fit to support gentle and cost-effective therapy. Dimar S.p.A. manufactures families of NIV masks for single-patient use in hospital environments, positioning itself as a provider of patient-interface accessories within broader ventilation workflows. GaleMed focuses on premium NIV CPAP masks designed for comfort and therapy performance, while Hans Rudolph has reimagined full-face masks with an emphasis on fit and care without sacrificing treatment effectiveness. DEAS supplies an extensive portfolio across anesthesia, ventilation, and non-invasive ventilation needs, and AirLife offers lightweight silicone full-face and nasal masks in vented and non-vented options across multiple sizes, underscoring clinician reliability and patient comfort. These companies illustrate that even within a concentrated market, there is meaningful differentiation in design philosophy, target setting, and end-user value proposition.
The strategic positioning of leading players tends to converge around a few priorities. The first is clinical fit and sealing performance, especially under high pressure or during extended use. The second is compatibility with different circuit types and hospital workflows, including vented versus non-vented configurations and single-limb circuit use. The third is patient comfort and ease of fitting, which affects adherence and reduces clinical adjustment time. A fourth priority is regulatory readiness and documentation, which has become increasingly important as procurement teams evaluate both clinical performance and compliance certainty. Companies that can combine these attributes with a clear intended-use narrative often gain an advantage in acute-care formulary decisions and, increasingly, in home-care and ambulatory channels where ease of use matters.
Market structure is evolving along several axes. Consolidation remains a possibility as larger platforms seek to strengthen respiratory portfolios and smaller players look for partnership or distribution pathways that broaden reach. At the same time, differentiation is intensifying rather than narrowing, because mask design is highly application-specific. A configuration that performs well in acute hospital ventilation may not be ideal for chronic home use, and vice versa. This creates room for specialized entrants that target particular patient populations, care settings, or clinical workflows. The presence of recent product launches and regulatory clearances across multiple companies suggests an industry in motion, with competitors actively expanding portfolios to address gaps in sizing, circuit compatibility, and comfort. Newer entries and catalog expansions in pediatric and infant segments further indicate that incumbents are not only competing on scale but also on clinical specificity.
For buyers and investors, the practical implication is that the market is not a simple hierarchy of incumbents and followers. It is a landscape in which leadership is contested through product architecture, regulatory timing, and alignment with the care settings where non-invasive ventilation is most actively adopted. Strategic advantage will likely accrue to those who can demonstrate consistent performance across the environments that matter most to their customers.
Future Outlook: Trajectories, Opportunities, and Watchpoints
Over the next three to five years, the NIV masks market is likely to be shaped by a small number of high-impact trends. The first is the continued expansion of home-based and ambulatory non-invasive ventilation, supported by evolving reimbursement frameworks and a broader shift toward managing chronic respiratory conditions outside the hospital. If coverage pathways remain favorable and clinical confidence in home NIPPV grows, demand for masks suited to long-term wear, ease of fitting, and patient convenience could increasingly influence product mix and procurement patterns. This creates an opportunity for manufacturers that can bridge acute-care performance with home-care usability, especially where patient adherence is a decisive clinical factor.
The second trend is the growth of application-specific and population-specific mask designs. The market is already seeing movement toward more modular portfolios, pediatric and infant configurations, and masks optimized for particular circuit types and therapy modes. As clinical protocols continue to differentiate between acute ventilation, chronic management, and transitional care, products that are purpose-built for these contexts may gain preference over generalized offerings. This trend favors companies that invest in fitting systems, sizing breadth, and design features that reduce mask adjustment and improve comfort across varied patient anatomies.
The third trend is the increasing importance of regulatory timing and evidence-driven differentiation. Because NIV masks are Class II devices requiring 510(k) clearance in the U.S., and because hospital procurement teams increasingly weigh compliance certainty alongside performance, the speed and clarity of regulatory approval can be a meaningful commercial factor. Companies that align product development with reimbursement and clinical evidence needs may be better positioned to capture adoption in high-value settings. At the same time, cost containment pressures will likely remain a persistent watchpoint; providers may favor solutions that reduce remasking, simplify infection-control workflows, and support predictable consumable spending.
These trends carry both opportunity and uncertainty. On the opportunity side, the combination of broader home-care use, more targeted product designs, and active regulatory activity points to a market in which well-positioned portfolios can gain share without relying solely on price competition. On the risk side, market growth may be uneven if reimbursement policies change, if clinical guidelines shift the balance between non-invasive and invasive approaches, or if supply chain and material costs alter margin expectations. Additionally, patient adherence challenges and the inherent variability of facial anatomy mean that even strong product designs must continue to earn confidence through real-world performance. The companies most likely to navigate this environment successfully will be those that treat mask design not as an isolated accessory category, but as an integral part of the broader non-invasive ventilation pathway.
Strategic Implications: What Decision-Makers Should Do Next
For manufacturers, the immediate priority is to align product roadmaps with the care settings and patient populations generating the strongest demand. This means investing in seal stability, comfort, and modular compatibility for hospital use while also ensuring that home-care and ambulatory offerings address adherence and ease of fitting. Regulatory planning should be treated as a strategic lever rather than a compliance checkbox, particularly given the active clearance environment and the commercial value of timely market access. Companies should also consider where portfolio breadth adds real clinical value versus where it simply increases complexity, because buyers are likely to reward designs that simplify selection and reduce workflow friction.
For investors, the key question is not whether the category will grow, but which segments and strategies will convert growth into durable margin and share gains. Preference may be given to players with differentiated product architecture, clear regulatory momentum, and strong alignment with reimbursement trends in home and hospital care. Particular attention should be paid to companies that can demonstrate value beyond unit price, including reductions in clinical adjustment time, improved adherence, and compatibility with evolving ventilation circuits. Portfolio exposure to pediatric, infant, and specialized acute-care configurations may offer additional optionality, especially if these segments continue to expand in clinical relevance.
For procurement and clinical decision-makers, the practical aim is to evaluate masks not only on immediate specifications but also on total therapy performance. This includes assessing seal reliability under anticipated pressure ranges, compatibility with existing circuits and workflows, sizing flexibility for diverse patient populations, and the evidence or clearance status that supports confident formulary inclusion. Given the pace of product introductions and regulatory updates, ongoing market intelligence can help procurement teams avoid delays in adoption and ensure that purchasing decisions reflect the latest clinically relevant options and access conditions.
As the market evolves, the winners will be those who connect product design, regulatory readiness, reimbursement awareness, and real-world usability into a coherent strategy. Detailed segment-level data, competitive benchmarks, and tailored scenario analysis can help organizations move from general market awareness to specific, executable decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Non-invasive Ventilation (NIV) Masks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com