

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Global Fast Electric Rolling Door Market Poised for a 7.85% CAGR Through 2032
By pmarketresearch, 2026-08-18
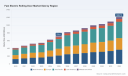
Fast Electric Rolling Door Market: Strategic Imperatives for 2026 Decision‑Makers
As organizations recalibrate facility operations for energy efficiency, throughput, and resilience, fast electric rolling doors have moved from a niche operational purchase to a strategic asset. PW Consulting’s new Fast Electric Rolling Door Market report (base year 2025) synthesizes five years of historical tracking (2020–2025) with scenario‑based forecasts through 2032. The headline: the addressable market is entering a sustained growth phase in 2026, with a compound annual growth rate (CAGR) of approximately 7.85% over the forecast window. This briefing highlights the report’s strategic value for 2026 planning while intentionally preserving the granular segmentation intelligence that is available only in the full report.
High Purity SiC Parts Market
Why 2026 is a Pivotal Year
-
Policy and procurement cycles are aligning. Energy efficiency mandates (notably provisions under 10 CFR 433 in the U.S.) and incentive structures have accelerated procurement timelines for solutions that reduce air exchange and thermal loss—attributes inherent to high‑speed rolling door systems.
EV Harness Market -
Input‑cost volatility, particularly in steel and aluminum markets, has created both risk and opportunity. Manufacturers and procurement teams that act in 2026 with hedging, design substitution, or pass‑through pricing strategies will materially outperform peers on margin stability.
Marine Wire Rope Market -
Technology differentiation (controls, impact resilience, modular designs) is reshaping total cost of ownership. Buyers are increasingly valuing lifecycle performance and uptime rather than lowest first‑cost, changing vendor selection criteria.
Market Trajectory: The Numbers You Need to Know
PW Consulting’s top‑level model shows a clear recovery and re‑acceleration in 2026 following steady growth in the prior half‑decade. The report’s base‑year analysis (2025) and forward projections through 2032 reflect a market expanding at roughly 7.85% CAGR—supporting strategic investment cases for manufacturers, integrators, and large end‑users contemplating fleet refreshes, retrofit programs, or new facility specifications.
Importantly, while headline growth is robust, the market is not uniform: material selection, door architecture (fabric vs. rigid constructions), and application context (logistics, cold chain, manufacturing) deliver distinct risk/reward profiles. PW Consulting’s full dataset provides the granular segmentation that procurement and product teams depend on; here we outline the implications without disclosing the proprietary splits.
Operational and Commercial Implications for 2026
-
Procurement strategy: Adopt a hybrid sourcing approach. Locking long‑lead material contracts where feasible mitigates exposure to steel price swings—historical analysis in the report shows price fluctuations can be large enough to erode margin or require price reset clauses in supplier contracts. Tactical use of multi‑year agreements with indexed adjustments is recommended for high‑volume programs.
-
Product planning: Prioritize modular control systems and retrofit‑friendly architectures. These features drive faster payback via reduced installation time and lower downtime costs—an increasingly critical purchase justification in logistics and cold‑storage environments.
-
Energy & sustainability: Align product roadmaps with energy efficiency standards and incentive windows. ENERGY STAR and other local programs have created near‑term financial incentives that change the ROI calculus for upgraded door systems; capital budgeting in 2026 should explicitly model these credits and the operational savings from reduced air exchange.
-
Pricing & margin management: Factor in input tariff risk. Recent tariff actions on steel and aluminum materially increased OEM cost bases; scenario planning with discrete tariff and price‑pass‑through assumptions should be mandatory in 2026 pricing reviews.
Competitive Landscape: Who Matters and Why
The fast electric rolling door market combines global engineering leaders, specialized regional fabricators, and an active aftermarket ecosystem. Competitive intensity varies by application: high‑throughput logistics and cold‑chain segments favor high‑performance, certified systems from established global suppliers, while localized security and hurricane‑zone applications remain the domain of regionally focused manufacturers.
-
Rytec Doors (Jackson, WI): Reputation for high‑performance commercial and industrial doors with deep installed base strength. Their recent product updates emphasize energy efficiency and impact resistance—key differentiators for warehouse operators prioritizing uptime and thermal control.
-
Albany Doors (Kenosha, WI): A leader in fabric and high‑speed roll‑up solutions. Albany’s product breadth and focus on logistics applications make them a go‑to for integrators specifying high‑duty‑cycle systems.
-
Hörmann (Steinhagen, Germany): A European heavyweight with advanced control platforms and a recent expansion into Southeast Asia, broadening local production and shortening supply chains for regional customers.
-
EFAFLEX (Bruckberg, Germany): Technology leader known for ultra‑fast spiral and vertical doors. Their recent Next‑Generation product family adds calibrated variants for premium, eco, and basic tiers—an explicit move to segment the value curve more finely.
-
Rite‑Hite (Milwaukee, WI): Known for robust fabric high‑speed doors and proprietary auto re‑feed mechanisms, appealing to high‑traffic dock operations seeking minimal downtime.
-
Cornell Iron Works , Cookson Door Products , Janus International , and Rolling Door Manufacturing : These firms illustrate the market’s regional depth—offering security‑grade, code‑compliant products (including hurricane‑zone solutions) and local installation/service networks that matter for many end users.
Market concentration is meaningful but not prohibitive: a combination of global champions and numerous niche players creates opportunities for both scale‑driven incumbents and agile specialists. M&A prospects often center on acquiring manufacturing scale in lower‑cost regions, adding controls/IP, or expanding service footprints—strategies reflected in recent transactions and product launches.
Recent Industry Moves and What They Signal
-
EFAFLEX’s November 2025 Next‑Gen rollout stratifies offerings into premium/eco/basic variants—indicating a shift toward configurable product platforms to win across different buyer personas.
-
Rytec’s 2025 line updates focusing on energy and impact resistance underscore the market premium for durability and lifecycle efficiency in warehouse environments.
-
Hörmann’s Southeast Asia acquisition (2025) demonstrates the growing importance of local production and shorter logistics for lead‑time‑sensitive projects.
-
New entrants and product launches in 2026 (e.g., ASTA America’s high‑speed rolling steel series) suggest continued innovation in speed and durability metrics—pressuring legacy platforms to modernize.
Risk Factors to Watch in 2026
-
Raw material volatility: Historical data points to material cost spikes that can distort annual P&L. The report includes sensitivity tables and procurement playbooks to stress‑test supplier exposure.
-
Regulatory shifts: Evolving energy codes and local standards (including tax credit expirations or renewals) can materially change adoption economics. Decision‑makers should align replacement cycles with policy windows.
-
Installation and aftermarket service: Field service networks are a competitive moat. Companies that underinvest in installation training and local service risk losing whole‑of‑life revenue streams.
What the PW Consulting Report Delivers (Practical Components)
-
Proprietary market sizing and 2026–2032 forecasting model (top‑level numbers highlighted here), with configurable scenario engines for material pricing and policy outcomes.
-
Supplier and technology matrix mapping product archetypes to application economics—designed to support fast vendor shortlists and RFP templates.
-
Procurement playbook including contract language samples, indexation strategies, and total cost of ownership calculators tailored to door architecture and duty cycle.
-
Go‑to‑market and channel strategies for manufacturers seeking to expand into new regions or verticals, plus M&A diligence checklists for strategic acquirers.
-
Service and aftermarket optimization guidance—how to structure SLA tiers, spare‑parts stocking policies, and digital monitoring to uplift recurring revenue.
Recommendations for 2026 Corporate Planning
-
For OEMs: Invest in modular control platforms and flexible manufacturing footprints now; the ability to deliver localized variants and rapid service will be a key differentiator.
-
For facility owners/operators: Prioritize lifecycle cost and energy impact in procurement decisions; model incentive capture (where available) and align rollouts with energy‑code timelines.
-
For investors and acquirers: Target bolt‑on plays that add service density, controls IP, or low‑cost regional manufacturing—these levers accelerate payback in a market growing at ~7.85% CAGR.
Next Steps
This briefing has highlighted the strategic contours for 2026 without revealing the segmented market intelligence that drives tactical decisions. PW Consulting’s full Fast Electric Rolling Door Market report contains the detailed regional/application splits, supplier share tables, and customizable financial models that procurement, product, and M&A teams require to act decisively this year. For organizations that need to convert the 2026 growth window into measurable advantage, the full report and accompanying Excel model are essential operational tools.
Contact PW Consulting to access the complete report package, tailored briefings, and scenario workshops that translate market projections into executable plans for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Fast Electric Rolling Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ion Beam Machining Market Poised for 7.85% CAGR, Report Forecasts Robust 2026–2032 Growth
By pmarketresearch, 2026-08-18
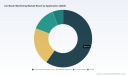
Ion Beam Machining Market 2026: Strategic Imperatives for Leaders — PW Consulting Preview
As PW Consulting publishes its flagship Ion Beam Machining Market report, this briefing outlines the high-level implications that senior executives, corporate strategists, and investment committees must factor into 2026 planning cycles. Built on a robust 2020–2025 historical base and a 2026–2032 forecast framework, the analysis projects a resilient expansion trajectory — driven by advanced semiconductor nodes, next‑generation photonics and optics, and intensifying demand for precision materials analysis. Our model anticipates the market to expand from a 2025 base of USD 215.75 Million to a materially larger industry by 2032, reflecting a compound annual growth rate (CAGR) of 7.85% across the forecast horizon. This release is a strategic “preview”: it surfaces the decision‑critical insights and actionable implications while preserving the granular segment-level intelligence for report subscribers.
AI Server Low Dielectric Glass Fiber Market
Why Ion Beam Machining Matters to 2026 Corporate Strategy
Ion beam machining (IBM) technologies — including focused ion beam (FIB), broad ion beam (BIB) and emerging plasma-based ion systems — are now mission‑critical in three strategic domains: advanced semiconductor manufacturing, high-precision optics/coatings, and materials science research & failure analysis. For technology OEMs and capital equipment investors, IBM is less a niche process and more a leverage point for enabling tighter tolerances, higher yields, and new device architectures (e.g., heterogeneous integration, photonic integration, and advanced packaging). The projected mid‑single‑digit to high‑single‑digit CAGR reflects both sustained demand for replacement and retrofit systems as well as a wave of new unit deployments tied to capacity expansions and R&D investments.
Wireless Network Simulator Market
Market Structure and Competitive Dynamics — What Leaders Should Read First
Two structural features define competitive dynamics and should shape boardroom deliberations in 2026:
Engine Compartment Protective Panel Assembly Market
- Consolidation and Concentration: The industry exhibits a moderate level of concentration among the top players, reflecting high technical barriers, IP intensity, and capital requirements. This concentration supports premium pricing for differentiated platforms but also creates acquisition windows for fast‑moving challengers and specialized service providers.
- Platform Diversification: Market leaders are pursuing multi‑technology portfolios — combining FIB, PFIB, and broad ion beam capabilities with software, automation, and service contracts — to capture end‑to‑end value and to reduce cyclicality tied to capex spending patterns of end customers.
Key incumbents profiled in our study exhibit distinct but complementary competitive plays. Some vendors emphasize precision thin‑film and optical coatings; others push integrated FIB‑SEM and high‑throughput failure analysis solutions. Meanwhile, specialized service providers and regional OEMs deploy nimble product programs and local service networks to win aftermarket share.
Recent Strategic Moves That Signal the Next Phase
- Product modularity and platform launches are accelerating: recent modular platforms bring together ion beam and plasma processes onto configurable toolsets, shortening time‑to‑qualification for multi‑process customers.
- Order flows into optical and laser supply chains point to renewed capex activity in select photonics segments, indicating pockets of above‑market growth outside pure semiconductor fabs.
- Broad ion beam tooling for sample preparation and cooling configurations have moved from laboratory staples into higher‑throughput production settings, unlocking new addressable use cases.
These directional shifts are evident in multiple vendor announcements over the past 18 months and are reflected in our scenarios for 2026 planning. For practitioners, the strategic question is not whether to play in ion beam, but how to structure participation — direct OEM play, system rental and service, software and automation, or vertical integration with end‑user fabs and research institutions.
Supply Chain and Technology Risks: What to Monitor Closely
Two risk vectors deserve board‑level attention in 2026:
- Raw material and source dependencies: Traditional FIB tools commonly rely on gallium liquid metal ion sources. This creates potential supply chain vulnerability to gallium availability and price volatility. Companies should stress‑test procurement and consider alternative ion sources or dual‑sourcing strategies where feasible.
- Process artifacts and rework needs: Post‑FIB implantation can introduce surface amorphization and contamination that necessitate follow‑up milling or low‑energy broad ion polishing. Product roadmaps that incorporate downstream mitigation (e.g., argon/xenon polishing, plasma treatments) will offer superior yield and lower total cost of ownership for end customers.
Regulatory and quality frameworks remain exacting — ion beam equipment must meet high‑vacuum and precision manufacturing standards. This reality elevates the importance of validated supply chains, accredited calibration services, and robust documentation for customers operating in regulated sectors.
Strategic Playbook — Four High‑Impact Moves for 2026
From our work with OEMs, fab operators, and private equity clients, the following four moves consistently preserve optionality and maximize upside in an IBM ecosystem growing at ~7.85% CAGR.
- Prioritize modularity and software differentiation: Invest in control software, AI‑driven process recipes, and modular hardware architectures that enable rapid reconfiguration. Software licensing and remote diagnostics materially increase annuity‑style revenue and improve gross margins.
- Pursue targeted M&A and partnership plays: Given the sector’s concentration dynamics, smaller acquisitions or licensing deals can accelerate entry into complementary process domains (e.g., PFIB, deposition/etch hybrids) faster than organic R&D alone.
- Shift to solutions and services: Expand into process development, application labs, and uptime guarantees. Service‑heavy contracts reduce customer capex sensitivity and create sticky long‑term relationships.
- Hedge supply risks and redesign consumable strategies: Secure multi‑year supply agreements for strategic feedstock, qualify alternate ion sources, and re‑engineer consumable lifecycles to reduce single‑supply dependencies.
What Our Full Report Delivers — Practical Tools for Decision‑Making
Our full Ion Beam Machining Market report goes beyond narrative and delivers executable assets that teams can use immediately in 2026 strategy cycles. Highlights include:
- Revenue and unit shipment models with scenario toggles for high/medium/low demand trajectories across the 2026–2032 horizon.
- Competitor scorecards and product roadmaps that benchmark technology readiness, service coverage, and commercialization timelines.
- CapEx and TCO calculators tailored to OEMs and end‑users that quantify payback periods under alternative utilization rates.
- An M&A screening matrix that flags targets by strategic fit, integration complexity, and accretion/dilution sensitivities.
- Supply chain risk heatmaps and mitigation playbooks addressing raw material sourcing, logistics constraints, and regulatory compliance checkpoints.
- Go‑to‑market blueprints for service expansion, including pricing models for subscriptions, uptime SLAs, and application lab commercialization.
- Executive dashboards for board reporting, with pre‑built visualizations for revenue run‑ways, margin scenarios, and capital planning.
Each tool is built to be directly plug‑and‑play within corporate financial models or to be adapted by private equity due diligence teams. While this preview highlights our core recommendations and strategic direction, the granular segmentation analytics, supplier share tables, and downloadable Excel models are gated in the full report to preserve subscriber value.
Competitive Appendix — Vendor Schemes to Watch
Our competitive synthesis profiles leading vendors across several strategic postures:
- Vendors focused on optical and thin‑film process integration are leveraging ion beam sputtering and deposition solutions to penetrate photonics and laser supply chains.
- Firms with integrated FIB‑SEM and plasma FIB roadmaps are capturing high‑value applications in failure analysis and volume imaging, enabling higher ASPs and service contracts.
- Specialized implanter and service providers are expanding their footprint by bundling processing services with equipment sales, creating hybrid commercial models that lower adoption friction for capital‑constrained customers.
Recent product launches and order flows underscore that incumbents are doubling down on modular platforms, higher throughput configurations, and service ecosystems — strategies that raise the bar for new entrants but create defined partnership pathways for niche innovators.
How to Use This Preview in Your 2026 Planning Cycle
For executive teams building 2026 strategic plans, this preview frames three immediate actions:
- Embed ion beam technological scenarios in capital planning: include upside/cushion scenarios tied to photonics and research capital cycles, not just mainstream fab investments.
- Update procurement and supplier strategies to reflect material source risk: run stress tests on gallium and alternative ion lines and prioritize multi‑source qualification.
- Allocate R&D and commercial resources to software and service offerings that convert cyclical hardware revenue into recurring annuities.
PW Consulting’s full report supplies the numbers, supplier maps, and decision tools required to operationalize each recommendation and quantify trade‑offs under a range of demand conditions.
Next Steps — Accessing the Full Report
This strategic preview is intentionally selective: it communicates the high‑level market trajectory and the decision levers that matter to leaders in 2026, while preserving the granular segment and vendor intelligence that forms the core of our premium analysis. For procurement teams, corporate strategists, and investors seeking the full dataset — including per‑segment forecasts, regional dynamics, and downloadable financial models — please visit the PW Consulting report page to license the complete Ion Beam Machining Market report and associated toolkits.
PW Consulting stands ready to support bespoke workshops, scenario stress tests, and M&A due diligence engagements that translate the report’s insights into executable 2026 strategies. Contact our industry team to schedule a briefing and receive a tailored package that aligns with your short‑ and medium‑term objectives.
For detailed analysis of this topic, please visit the official page: Ion Beam Machining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Stern Drive Boat Propeller Market to Expand at a 6.7% CAGR Through 2032
By pmarketresearch, 2026-08-18
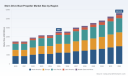
Stern Drive Boat Propeller Market — Strategic Preview for 2026: Why Executives Should Recalibrate Now
PW Consulting’s latest Stern Drive Boat Propeller Market report (base year 2025, forecast period 2026–2032) delivers a concise, actionable view for executives preparing 2026 budgets and roadmaps. The market has moved from an inflection point in the early 2020s into a structurally expanding phase: total industry revenue rose materially through the 2020–2025 historical window and reached approximately USD 3.57 billion in 2025. Our forecast model, incorporating supply-side constraints, material cost volatility, and evolving OEM channel dynamics, projects a steady trajectory through 2032 at a compound annual growth rate (CAGR) of 6.7%, culminating in a market north of USD 5.6 billion by the end of the forecast period.
Digital Wireless Weighing Sensor Market
Why this preview matters for 2026 decision-makers
-
Timing for capital allocation: With market expansion now evident, capacity investments and tooling decisions made in 2026 will influence cost structures and service levels throughout the next planning cycle.
Carbon Coated Binder Market -
Supply-chain sensitivity: Raw-material dynamics that tightened in 2024–2025 (notably nickel price swings) have shifted procurement from spot-driven tactics to multi-year contracting and hedge strategies — an operational shift that will determine margin resilience.
Fixed Brake Calipers Market -
Competitive positioning: The market shows moderate concentration (CR3 ~38.5%, CR5 ~52.8%), indicating clear leaders yet meaningful room for mid-market consolidation and specialist plays; this balance shapes M&A and partnership opportunities.
-
Technology windows: Propeller design innovations (including looped and dual-prop configurations) and material substitutions are maturing from R&D to commercial deployment, creating first-mover advantages for players who align product, OEM channels, and aftermarket strategies in 2026.
Snapshot of what PW Consulting’s report delivers (practical, operational content)
-
Market sizing and scenario modeling: a base-case, upside, and downside view through 2032 that isolates the impact of input-cost shocks and demand elasticity on revenue and margin pools.
-
Commercially focused segmentation analysis: granular segmentation by region, propeller type (material and blade configuration) and application (recreational vs commercial), with SKU-level demand drivers and replacement cycles clearly mapped — note: segment-level figures are purposefully reserved for full subscribers.
-
Cost-to-serve atlases and factory footprint optimization: heat maps showing relative labor, logistics, and raw-material exposures to inform relocation, insourcing, or co-manufacturing decisions.
-
Procurement playbook: hedging templates, supplier qualification scorecards, and inventory policy recommendations suited to compound volatility in nickel and alloy inputs.
-
Go-to-market and aftermarket strategies: differentiated approaches for OEM partnerships, dealer networks, direct-to-consumer aftermarket channels, and digital service enablement.
-
M&A and partnership roadmaps: prioritized target lists, synergy case assumptions, and integration risk templates for buyers and PE sponsors eyeing the space.
From insight to action: five strategic imperatives for 2026
-
Recalibrate procurement and inventory policies to reflect metal-price volatility. Nickel-aluminum bronze remains a dominant material choice in many marine propeller designs due to corrosion resistance, but nickel price swings between recent multi-year ranges have meaningfully impacted cost of goods sold. Procurement teams should adopt multi-scenario contracting and consider forward-buy windows tied to production cycles.
-
Prioritize product roadmaps around certified OEM compatibility and efficiency gains. Manufacturers that demonstrate fitment for major sterndrive OEM platforms and deliver measurable fuel-efficiency or thrust improvements will capture higher-margin OEM retrofit and aftermarket demand. Dual-prop/contra-rotating and novel blade geometries are moving from niche to mainstream testing — plan pilots with strategic OEM partners in 2026.
-
Balance scale and specialization in M&A choices. The market’s mid-level concentration presents targeted consolidation opportunities: scale deals can unlock procurement leverage, while bolt-on acquisitions focused on specialized alloys, machining capabilities, or geographic dealer networks can deliver differentiated commercial access.
-
Invest selectively in manufacturing automation and digital traceability. Cycle times and quality variance in propeller finishing and balancing are high-leverage areas where automation reduces rework and warranty exposure. Digital serial-traceability and lifecycle analytics will increasingly underpin OEM warranty negotiations and aftermarket monetization.
-
Design a dual-channel go-to-market for 2026: deepen OEM relationships while formalizing direct aftermarket programs. A hybrid model preserves OEM revenue streams yet captures lifecycle value from owners via installation, diagnostics, and performance upgrades.
Competitive landscape — tactical takeaways
The sterndrive propeller ecosystem combines legacy OEMs, specialized independent manufacturers, and a set of innovation-oriented challengers. Executives preparing 2026 strategies should view competition across three axes: OEM integration capability, material/manufacturing competence, and design innovation.
-
Michigan Wheel (Grand Rapids, MI): a long-standing supplier of high-performance aluminum and stainless-steel propellers with deep OEM fitment knowledge for key sterndrive platforms. Recent strategic moves to refocus core markets signal a tighter U.S.-centric commercial posture — an important consideration for partners seeking domestic sourcing and rapid aftermarket response.
-
Sharrow Marine (Detroit, MI): notable for patented looped propeller concepts delivering measurable efficiency gains. Their continued product expansion and dual-prop testing programs position them as a technology acquirer’s target or a preferred partner for OEMs seeking step-change performance improvements.
-
Solas Science & Engineering (Taiwan): a production scale player with broad sterndrive fitment coverage. Their trade-show activity and product demonstrations underscore a push to reinforce global distribution and aftermarket presence.
-
Volvo Penta (Gothenburg, Sweden) and Mercury Marine (Brunswick) (Fond du Lac, WI): OEM-integrators that combine drivetrain and propeller design. Competitors must plan around OEM-certified design constraints while exploring adjacencies in retrofit and performance variants.
-
Independent specialists (Turning Point, PowerTech, Konrad Marine, Hill Marine and similar names): these players compete on material craftsmanship, niche performance optimization, and aftermarket responsiveness. Their agility makes them important partners or acquisition targets for both OEMs and private equity.
Recent industry events underscore these dynamics: Michigan Wheel’s strategic divestiture of certain regional operations in 2025, Solas’ renewed product showcase activity in early 2026, and Sharrow Marine’s continued rollout of dual-prop development work all point to a market where portfolio focus, channel expansion, and design-led differentiation are being actively pursued.
Risk map — what could derail the base case in 2026?
-
Raw material shocks: prolonged spikes in nickel or alloy costs could compress margins and accelerate material substitution or design simplification.
-
OEM certification cycles: delays in certification for novel propeller geometries can push adoption timelines beyond planned marketing windows.
-
Geopolitical disruption in key manufacturing hubs: supply-chain rerouting or tariffs would raise landed costs and favor local content solutions.
-
Aftermarket channel fragmentation: failure to control installation and service experiences can erode brand equity and increase returns/warranty claims.
How to use this report in your 2026 planning cycle
-
Board-level briefings: use our scenario models to stress-test capital expenditure requests and to quantify upside from targeted product launches or aftermarket initiatives.
-
Commercial planning: align sales incentives and channel investments to the report’s go-to-market playbook that distinguishes OEM versus aftermarket revenue streams.
-
M&A diligence: use our target prioritization and synergy templates to accelerate screening and valuation work for both strategic and financial buyers.
-
Procurement and operations: adopt the procurement playbook and factory-footprint recommendations to lock in supply and protect margins versus raw-material volatility.
Conclusion — a narrow window to build durable advantage in 2026
The sterndrive propeller market is entering a growth phase defined by converging forces: steady end-market expansion (our models show robust growth through 2032 at a 6.7% CAGR), input-cost uncertainty, and accelerating product innovation. For executives, 2026 is not simply another planning year — it is a strategic inflection where procurement policy, product investments, and channel strategy will determine the winners and the laggards for the remainder of the decade. PW Consulting’s Stern Drive Boat Propeller Market report equips leaders with the scenario-tested insights, operational playbooks, and competitive intelligence to convert that inflection into sustainable advantage.
Obtain the full analysis
This press release highlights the strategic imperatives and operational levers from PW Consulting’s full report. The complete study contains the granular segment forecasts, SKU-level analysis, supplier scorecards, and proprietary scenario models needed to execute on the 2026 actions above. Access to the full dataset and appendices is available through our research portal.
For detailed analysis of this topic, please visit the official page: Stern Drive Boat Propeller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rack‑mounted Full Liquid CDU Market to Nearly Double from USD 105.0 Million in 2025 to USD 203.45 Million by 2032 at a 9.85% CAGR — North America (~42%) and Liquid‑to‑Liquid CDUs (~68.5%) Drive Demand
By pmarketresearch, 2026-08-12
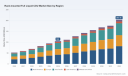
PW Consulting Releases Strategic Brief: Rack-mounted Full Liquid CDU Market — A Decision-Grade Preview for 2026
PW Consulting’s latest industry study on the Rack-mounted Full Liquid Coolant Distribution Unit (CDU) market delivers executive-grade intelligence designed to influence procurement, engineering and capital-allocation decisions in 2026. Our analysis synthesizes historical build rates (2020–2025), near-term market sizing and a 2026–2032 forecast horizon, and couples quantitative projections with operational playbooks for data center owners, hyperscalers, OEMs and systems integrators. This release is a curated preview: it exposes the strategic findings and actionable recommendations you need to decide quickly, while preserving the report’s granular tables and vendor-level scorecards for subscribers.
Driven Hydraulic Wrench Market
Market at a Glance — Why 2026 Is a Pivotal Year
The rack-mounted full liquid CDU market has moved from an early adoption phase into a structured growth market. PW Consulting estimates the market value reached USD 105.0 Million (base year 2025) and is forecast to grow at a compound annual growth rate (CAGR) of 9.85% over the 2026–2032 period, roughly doubling in value by 2032. This trajectory reflects a confluence of forces: the accelerated deployment of GPU-dense AI racks and HPC clusters, tighter facility reliability standards, and a shift toward higher coolant temperatures and direct-to-chip heat extraction strategies.
Ionizing Radiation Precision Instruments Market
Concentration metrics in the competitive landscape indicate a moderately consolidated market: the top three suppliers account for just under half of market revenue, while the top five push well beyond the halfway mark. This structure creates clear zones of competition — entrenched leaders who control scale and channel access, and nimble challengers who compete on modularity, thermal performance or integration services.
Worldwide Parenteral Nutrition Fat Emulsion Market
What the Report Delivers — Practical, Executable Assets
- Operational Playbooks: Installation-validated checklists for rack-level CDU deployment (electrical, hydraulic, piping isolation and commissioning sequences), plus integration blueprints for direct-to-chip and cold-plate architectures.
- Procurement & Vendor Selection Toolkit: RFP templates, evaluation rubrics, SLA clause libraries and spare-parts agreements tailored to rack-mounted CDU lifecycles.
- TCO & Scenario Models: Proprietary total-cost-of-ownership calculators that factor CapEx, energy impacts, fluid chemistry, maintenance regimes and asset modularity; editable scenario files for sensitivity analysis across electricity prices, inlet approach temperatures and failure rates.
- Regulatory & Standards Roadmap: Compliance checklists and adoption pathways aligned with the latest ASHRAE TC 9.9 guidance and forthcoming addenda to Standard 127 — essential for separating Facility Water Systems (FWS) and Technology Cooling Systems (TCS) and for credible performance certification.
- Supplier Scorecards & Shortlists: A synthesized vendor assessment across technology fit, scalability, service footprint and supply-chain risk — enabling rapid down-selection for pilots and production rollouts.
- Executive Briefings & Board-Ready Slides: Decision-support packages focused on purchase timing, financing alternatives, and integration timelines for AI/HPC procurement cycles.
Strategic Implications for 2026 Decision-Makers
- Operational resilience over lowest upfront price: With ASHRAE guidance emphasizing separation of FWS and TCS, data center operators should prioritize CDUs that offer certified isolation barriers, redundant or hot-swappable pumping, and clear serviceability access. The report maps failure-mode impacts to service-level targets so CFOs and CTOs can align on acceptable residual risk.
- Design for modular scale: GPU and accelerator densities are evolving quickly. Units that support modular scaling — from rack-level up to multi-rack clusters with predictable hydraulic balancing — reduce retrofit costs and shorten time-to-capacity.
- Thermal strategy matters: Narrow approach temperatures and elevated water operating points unlock higher free-cooling and waste-heat recovery opportunities. However, these choices carry implications for fluid selection, certification and supplier life-cycle support; our TCO models quantify the break-even across common design options.
- Supply-chain & materials vigilance: Global phase-downs of certain refrigerants and evolving supplier certification requirements raise component lead times and compliance costs. Procurement teams should integrate material-certification clauses into long-term contracts and build multi-sourcing where practical.
- Choose partners with end-to-end capabilities: Integration risk is frequently the largest hidden cost. Vendors that combine CDU hardware with controls, lifecycle services and rapid global spare-part support deliver lower total operational disruption during scale-up and peak load migration.
Competitive Landscape — Who Matters and Why
PW Consulting’s market mapping identifies a diverse set of influential suppliers, each presenting different value propositions for 2026 deployments:
- CoolIT Systems (Calgary, Canada) — Known for high-performance in-rack CDUs (CHx200, CHx80) optimized for dense HPC and AI servers; strength lies in compact liquid-to-liquid modules designed for direct integration with high-power servers.
- Super Micro Computer / Supermicro (San Jose, USA) — Offers in-rack and in-row CDUs with redundant, hot-swappable pumps and very high unit capacities; their systems are attractive to integrators needing rack-level resilience and vendor-aligned server fitment.
- DCX Liquid Cooling Systems (Warsaw, Poland) — Focuses on compact, high-capacity liquid-to-liquid CDUs (HYDRO CDU1) for AI centers where per-rack power density and minimized footprint are decisive.
- LiquidStack (Carrollton, USA) — Delivers solutions supporting narrow approach temperatures and elevated water operation for ultra-high-density deployments, with offerings that scale to very high per-unit capacities.
- Flex (via JetCool) (Austin, USA) — Recently launched modular rack-level CDU platforms that emphasize scalability (announced 2025), signaling a move towards large-scale, OEM-backed modular solutions for hyperscalers.
- Motivair (by Schneider Electric) (Lancaster, USA) — Recently announced scalable CDUs targeting next-generation AI deployments (January 2026), leveraging Schneider’s systems integration depth for floor-to-rack solutions.
- Asetek (Denmark) — Competes on warm-water InRackCDU systems for efficient, serviceable rack cooling where moderate per-rack capacities are the design point.
- nVent (Minneapolis, USA), Dell Technologies (Round Rock, USA), Eaton (Dublin/US operations) — These established players bring reliability, channel reach and integration services; they are frequently preferred when operators prioritize vendor consolidation and enterprise-grade support.
Recent product moves — such as Flex’s modular launch in late 2025 and Motivair’s high-capacity MCDU announcement in early 2026 — highlight a competitive emphasis on modular scalability and higher per-rack capacities. Dell’s continued promotion of rack-mount RCDU solutions reinforces that major OEMs are actively positioning to supply integrated server/CDU stacks for AI and HPC customers.
Regulatory & Standards Context — What Keeps Risk Managers Awake
Two regulatory trends should be part of every 2026 procurement checklist. First, ASHRAE TC 9.9’s recent emphasis on CDU-based isolation between Facility Water Systems and Technology Cooling Systems elevates design review requirements for third-party certs and field commissioning documentation. Second, updates to ASHRAE Standard 127 (with new test-method addenda covering liquid-to-liquid CDUs) will change how suppliers’ performance claims are validated — and therefore how buyers compare products on an apples-to-apples basis.
Finally, environmental policy levers — including the Kigali Amendment’s phase-down of specific refrigerants — are increasing certification and compliance costs for thermal components and may alter supplier cost structures and lead times. Our report provides mitigation strategies, recommended contractual protections and sourcing pathways that limit exposure to material-driven cost escalation.
How PW Consulting’s Report Supports Tactical Pilots and Strategic Roadmaps
- Pilot-to-Production Playbook: Stepwise adoption templates for moving from single-rack pilots to row- and room-level liquid cooling mosaics, with staged capital outlays and operational checkpoints.
- Vendor Negotiation Guides: Benchmarked service windows, warranty terms and spare-part policies distilled from supplier interviews and primary deployments.
- Integration Checklists: Controls interoperability, telemetry expectations and cybersecurity hardening for CDU control systems and BMS/EMS integration.
- Scenario-Based Risk Matrices: Energy-price sensitivity, elevated-water-performance scenarios and maintenance staffing models that reveal the levers with the largest impact on cost of operations.
Next Steps — Where to Find the Full Intelligence
This release is a strategic preview intended to orient 2026 decisions and highlight the areas where immediate action yields disproportionate value. The full PW Consulting Rack-mounted Full Liquid CDU Market report contains the detailed regional and application splits, vendor line-item revenue forecasts, downloadable TCO spreadsheets, vendor scorecards and procurement templates reserved for report subscribers. These elements are intentionally withheld from this public summary to preserve the proprietary analytics and to enable clients to act on validated, decision-grade intelligence.
Contact PW Consulting or visit our report page to access the full dataset, schedule a private briefing, or engage our consultants for a customized vendor selection and pilot plan. In a market evolving as quickly as rack-mounted liquid CDUs, timely insight and disciplined execution will separate winners from laggards in 2026.
For detailed analysis of this topic, please visit the official page: Rack-mounted Full Liquid CDU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Indirect Auto Finance Market Poised to Reach USD 474.0 Billion by 2032
By pmarketresearch, 2026-08-12
Indirect Auto Finance Market — 2026 Strategic Outlook
PW Consulting’s new Indirect Auto Finance Market report provides a focused, decision-grade view for executives preparing 2026 strategies. Built on rigorous historical analysis and forward-looking scenario modeling, the study distills the macro trajectory, competitive dynamics, regulatory inflection points, and practical playbooks that lenders, OEM captives, dealers, and fintech partners will need to navigate accelerating complexity in dealer-originated consumer vehicle finance.
Public Safety Dispatch Consoles Market
Executive snapshot
The indirect auto finance ecosystem has entered a renewed growth phase after a period of volatility. Our model shows the market expanding from approximately USD 168.45 Billion in 2020 to roughly USD 298.5 Billion in 2025, with a base-year profile calibrated to 2025 financials. Looking forward, the market is projected to compound at an annualized rate of 6.85% across the 2026–2032 forecast window, reaching an estimated USD 474.0 Billion by 2032 under the central scenario. These headline metrics frame the strategic choices facing market participants in 2026: scale, capital sourcing, credit appetite, and digital distribution will determine winners and laggards.
Avocado Butter Market
Why this report matters for 2026 decision cycles
-
Timing: Boards and C-suite teams setting budgets and product roadmaps for 2026 must align capital plans with an industry that is both growing and re-pricing risk. Our report translates macro growth into actionable pathways for origination, securitization, and capital deployment.
Luxury Home Audio Market -
Regulatory shift-readiness: With material regulatory activity affecting how nonbank originators are defined and supervised, institutions must be ready to redesign compliance and reporting functions. The report offers scenario-driven impact assessments to prioritize one- and two-year remediation steps.
-
Dealer-channel economics: Since the vast majority of auto loans continue to be originated via dealer channels, optimizing dealer-lender bilateral economics—without sacrificing credit performance—will be a core lever. The report supplies a modular toolkit for reconfiguring dealer incentives, repricing mechanisms, and inventory funding strategies.
-
Competitive positioning: A rising share of dealer-originated volume is shifting toward banks and non-captive lenders. The report maps competitive vectors for captives, banks, and independents and provides playbooks to defend or accelerate market share.
What’s inside: practical, implementable content
This is not a brochure—our research is purpose-built to put plans into motion. Key deliverables include:
-
Validated market sizing and near-term forecasts (2026–2032) with sensitivity cases for demand shocks, rate movements, and affordability stress.
-
Scenario playbooks: three calibrated scenarios (central, downside, upside) with quantified impacts on originations, loss rates, and funding needs to inform capital planning and stress testing.
-
Operational playbooks for dealer-originated flows: step-by-step approaches for improving conversion, reducing charge-offs, and shortening time-to-fund while maintaining compliance.
-
Regulatory impact matrix and remediation roadmap: prioritized actions to respond to changing definitions of “larger participants,” disclosure expectations, and fair lending interpretations.
-
Product and pricing playbooks: modular templates for rate-card design, risk-based pricing governance, and dealer compensation structures aligned with portfolio objectives.
-
Capital and funding strategies: decision frameworks for whole-loan sales, securitization tranches, warehouse lines, and bilateral funding to optimize cost of capital under different originations mixes.
-
Technology & data roadmaps: recommended investments in decisioning engines, dealer portals, and performance analytics to compress loss cycles and uplift throughput.
-
Competitive intelligence appendices: curated profiles and strategic positioning assessments of principal active players in the indirect channel.
Competitive landscape — who matters and why
The indirect auto finance space is meaningfully concentrated, but still offers room for disruption. The top three providers account for a substantial share of market volume, and the top five consolidate over half of all activity—an important contextual fact when setting share targets or evaluating M&A. Market concentration creates advantages in scale for distribution, capital access, and dealer reach, while also leaving white space for specialized providers and digital challengers to capture niche or underserved segments.
We profile the strategic orientations of core market participants to help clients benchmark positioning:
-
Ally Financial — a leading non-captive lender that leverages broad dealer networks and depth in retail installment and floorplan financing. Their scale in dealer relationships and treasury functions provides a template for integrated dealer financing strategies.
-
Capital One Auto Finance — bank-affiliated, emphasizing competitive rates and digital approval experiences. Their model underscores how digital conditional-approval frameworks shorten the buyer journey and increase cross-sell.
-
Toyota Financial Services, GM Financial, Ford Motor Credit, American Honda Finance — captive finance arms that use brand-aligned product bundles, lease options, and loyalty-focused underwriting to preserve OEM sales economics. Captives remain pivotal for OEM go-to-market control and price elasticity management.
-
Chase Auto Finance and Wells Fargo Auto — large-bank lender profiles that combine dealer distribution with balance-sheet scale and sophisticated funding programs.
-
Westlake Financial Services — an independent specialist that demonstrates how underwriting specialization and dealer-focused servicing can profitably address higher-risk segments underserved by prime lenders.
Recent market intelligence points to structural movement: independent analyses published in early 2026 indicate banks and non-captive lenders are gaining share in dealer-originated volume, and dealer-related finance debt has shown double-digit year-over-year growth in certain channels. For strategy teams, this underlines two imperatives—first, sharpen the distributor value proposition; second, revisit capital and risk-allocation frameworks to monetize growing dealer pipelines.
Regulation and macro dynamics that will shape 2026 outcomes
The policy and macro backdrop is rapidly evolving and must be integral to any 2026 plan. Highlights from our Dynamics analysis include:
-
Supervisory redefinition risk: Regulatory attention on thresholds for “larger nonbank auto finance participants” creates potential new compliance and reporting obligations for firms crossing originations thresholds. This is already influencing originator behavior when sizing dealer relationships and balance-sheet deployments.
-
Fair-lending interpretation changes: A notable policy development clarified the scope of disparate impact claims under ECOA in late 2025, altering litigation and supervision risk profiles for indirect channels where dealer markup and discretion are present.
-
Demand sensitivity: Market intelligence suggests a modest near-term moderation in originations due to affordability pressures—some forecasts point to a small downtick in 2026 origination volumes. Our scenarios quantify the impact on revenue, loss ratios, and capital needs so leaders can stress-test budgets.
-
Dealer origination dominance: Independent research continues to validate that the majority of auto loans are dealer-originated and subsequently placed with lenders, reinforcing the strategic importance of dealer experience management and reseller economics.
Strategic imperatives for market participants in 2026
Based on our integrated market, competitive, and regulatory analysis, PW Consulting recommends four priority moves for executives setting 2026 agendas:
-
Recalibrate origination footprint: Actively manage dealer relationships and channel incentives to optimize mix and preserve access to high-conversion partners. Consider selective expansion into underserved dealer cohorts where pricing power can be sustained.
-
De-risk through capital architecture: Diversify funding sources and prepare contingency securitization pathways to insulate originations from short-term liquidity stress. Capital planning should be scenario-driven and integrated with product/design decisions.
-
Hardwire regulatory readiness: Run targeted gap analyses against likely supervisory thresholds and fair-lending controls; prioritize remediations that reduce operational friction without materially sacrificing revenue.
-
Accelerate digital dealer integration: Invest in decisioning engines, real-time funding, and dealer UX to compress cycle times, reduce fallout, and limit dealer discretion in markup—thereby improving credit outcomes and reducing supervisory attention.
How this report is structured to support execution
Every chapter of the report is aligned to execution. Market-sizing and forecasting modules feed into the capital and stress-test appendices; competitive landscaping includes actionable diagnostics and countermeasures; regulatory assessments are prioritized by likelihood and business impact, with concrete implementation timelines. The result is a concise, prioritized roadmap for 90-, 180-, and 365-day actions that managers can fold into operating plans.
Next steps
For teams preparing 2026 budgets, product launches, or dealer-partner strategies, this report functions as both an early-warning system and an operations manual. PW Consulting’s analysts are available to run customized slices of the model—tailoring scenarios to specific origination mixes, funding structures, and regulatory exposures—so firms can convert strategic clarity into measurable actions.
To access the full set of forecasts, scenario outputs, and implementation playbooks, request the complete Indirect Auto Finance Market report on our website. The executive summary in this release previews the strategic logic and highlights the high-level forecasts; the full report contains the granular decision-support models and step-by-step playbooks necessary to operationalize a winning 2026 strategy.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Sound Insulation NVH Market (Base Year 2025) Poised to Reach USD 21,123.45 Million by 2032 at a 5.85% CAGR
By pmarketresearch, 2026-08-12
Automotive Sound Insulation & NVH Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive snapshot
PW Consulting today publishes a strategic industry brief that synthesizes quantitative market sizing, regulatory trajectories, technology shifts, and competitive dynamics shaping the Automotive Sound Insulation & NVH (noise, vibration, harshness) market as OEMs navigate the 2026 inflection point. The brief’s macro finding is unambiguous: total industry revenues have expanded from a multi-billion-dollar baseline at the start of the decade to an estimated USD 14.19 billion in the report’s base year (2025), and our model projects continued momentum through the forecast window with a compound annual growth rate of 5.85%. This growth trajectory underscores NVH as both a resilience lever for traditional powertrains and a strategic differentiator for electric vehicle (EV) interiors.
Worldwide Wind Energy Equipment Cabin Bolts Market
Why this brief matters for 2026 decision-makers
- Regulatory deadlines converging in 2026 (notably stricter EU noise limits and the mandatory rollout of updated UNECE R51.03 testing regimes) convert NVH from a comfort optimization to a compliance-critical function. Executives must prioritize investments that mitigate regulatory risk while preserving margin.
- Electrification changes the NVH problem-set: lower powertrain noise raises the relative importance of cabin-born noise paths, body-borne vibration, and ancillary systems. The 2026 planning cycle is the last major window for OEMs and Tier 1s to rebase supplier agreements and engineering roadmaps ahead of model-year 2028 content freezes.
- Market scale and steady growth (CAGR 5.85%) create a favorable environment for technology-led consolidation, targeted M&A, and partnerships that offer material substitution, weight reduction, or mono-material recyclability at scale.
Report composition — what we deliver
PW Consulting’s brief balances executive-ready guidance with rigorous analytical transparency. Key deliverables include:
Battery Liquid Cooler Market
- Independent market sizing: historical series and a granular forecasting engine that explains the drivers behind the transition from the historical baseline to the 2025 base and the projected 2026–2032 trajectory.
- Regulatory impact assessment: a scenario analysis quantifying the commercial and technical implications of EU and UNECE noise standards, with mitigation cost curves and compliance timelines mapped by vehicle architecture.
- Technology deep-dive: performance benchmarking of material classes (rubber compounds, polymer foams, engineered fibers, and hybrid/composite solutions), life-cycle carbon implications, and manufacturing feasibility at OEM volumes.
- Supply chain and cost-to-serve mapping: sourcing risk heatmaps, capital intensity metrics for key manufacturing footprints, and logistics scenarios for nearshoring vs. concentrated sourcing.
- Competitive intelligence and deal flow advisory: profiles, capability matrices, recent initiatives, and M&A archetypes to accelerate inorganic growth or strategic alliances.
- Actionable playbooks: procurement negotiation levers, engineering-to-cost (E2C) approaches for NVH specification harmonization, and a phased implementation roadmap aligned to 2026 compliance milestones.
Competitive landscape — strategic takeaways
The NVH ecosystem remains fragmented by application and material specialization, with the largest incumbent players combining product innovation, vertical integration, and geographic reach. Market concentration metrics indicate moderate aggregation: the top three suppliers capture a meaningful share of revenues, and a top-five cohort controls more than half of the addressable market—conditions that favor scale players in pricing and platform-level adoption.
Worldwide Heavy Duty Steam Rice Cooker Market
Profiles in context: what leading suppliers are doing
- Autoneum Holding AG — A market leader in fiber-based acoustic and thermal management, Autoneum’s recent public showcases emphasize lightweight mono-material carpets and PET-based constructions designed for recyclability and EV-specific comfort. For OEMs seeking low-mass, high-performance cabin architectures, Autoneum’s platform-level solutions reduce integration friction.
- Vibracoustic SE — Specializing in powertrain decoupling and ride-related components, Vibracoustic’s recent supply wins in premium electric truck programs illustrate the continuing relevance of targeted mechanical NVH controls even as electrification reduces combustion-source noise.
- BASF SE and The Dow Chemical Company — Both chemical majors continue to push polymer innovation for microcellular foams, engineered elastomers, and cavity-fill systems. Their material science roadmaps are critical for OEMs that require both acoustic performance and manufacturability at high cycle rates.
- 3M Company — With a portfolio of thin, lightweight acoustic insulators and damping films, 3M remains a go-to supplier for retrofitable and interior surface treatments that help OEMs hit short-term NVH targets without heavy retooling.
- Sumitomo Riko, Henkel, and ElringKlinger — These firms fill strategic niches across mounts, adhesive dampers, and sealing/ acoustics. Their product breadth is particularly valuable for integrators managing cross-domain NVH challenges between powertrain, body, and HVAC subsystems.
Recent signals and what they imply for 2026 planning
- Product showcases and trade shows in 2025 spotlight sustainability and mono-material designs. For procurement and materials teams, this signals a pivot to recyclability criteria in supplier scorecards, not merely unit cost.
- Application wins for EV platforms (notably in premium pickup and utility segments) show that mechanical NVH components retain strategic value. Firms should not assume electrification eliminates demand for mounts, air springs, or engineered bushings—rather, specifications shift.
- Regulatory timing is non-negotiable: with enhanced urban noise weighting and high-load testing phased in by mid-2026, engineering groups must accelerate validation cycles for any new NVH material or architecture that has not yet completed certified testing.
Strategic implications — prioritized actions for 2026
- Embed NVH as a cross-functional KPI. NVH must sit alongside weight, cost, and emissions in platform scorecards. Assign accountable owners in R&D and product planning and align supplier contracts to outcome-based acoustic metrics.
- Advance material substitution pilots now. Given the projected growth and regulatory berth, short pilots on mono-material carpets, engineered PET felts, and low-density microcellular foams can de-risk qualification timelines and provide bargaining leverage in 2027 purchasing cycles.
- Re-evaluate supplier portfolios through a compliance-and-sustainability lens. The market’s moderate concentration rewards strategic partnerships with Tier 1 leaders that can guarantee scale, but niche suppliers can be critical for differentiated NVH performance—use targeted M&A or JV structures to secure capabilities.
- Prepare for testing regime changes. Update validation benches and acoustics labs to reflect UNECE R51.03 Phase 3 test profiles; plan for iterative certification cycles and allocate capex for accelerated test throughput.
- Monetize NVH as a value lever in marketing for EVs. Quiet cabins are a brand differentiator; coordinate product, marketing, and dealer channels to translate acoustic performance into perceived quality premiums.
Risk matrix & upside scenarios
The primary near-term risks to planned investments are: prolonged supplier qualification timelines, raw-material price volatility affecting foam/elastomer margins, and delayed regulatory clarifications in non-EU jurisdictions. Offsetting upside scenarios include faster-than-expected adoption of lightweight bio-based fibers and broader OEM willingness to pay for superior acoustic differentiation in premium segments. PW Consulting’s scenario suite quantifies these levers and maps their P&L sensitivity for both OEMs and Tier suppliers.
How PW Consulting supports executive decisions
Our brief is designed to be a decision-ready instrument for C-suite and business-unit leaders preparing 2026 budgets and 2027 product commitments. We pair market analytics with negotiation playbooks, supplier scorecards, and an M&A shortlist methodology tailored to NVH. For organizations pursuing more bespoke support, PW Consulting offers accelerated workshops that convert the brief’s strategic recommendations into executable 90–180 day plans, including sourcing pilots, laboratory upgrades, and alliance negotiations.
Next steps — where to find the full intelligence
This release is an executive preview intended to surface the most consequential trends and recommended actions as stakeholders prepare for regulatory and market inflection in 2026. The full report contains the complete forecasting model, detailed supplier profiles, segmented demand drivers, cost-to-serve matrices, and downloadable scenario tools. To access the comprehensive dataset, confidential company deep dives, and tailored advisory options, please visit PW Consulting’s Automotive Sound Insulation & NVH report page or contact our advisory team for a briefing and sample extracts.
Closing thought
As NVH shifts from a differentiator to a compliance-anchored discipline in the coming 12–18 months, companies that integrate acoustic strategy into platform planning — and treat materials and supplier selection as strategic investments rather than line-item costs — will capture both regulatory resilience and customer-perceived quality premiums. PW Consulting’s brief equips leaders to make those trade-offs with clarity and urgency.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PM2.5 Monitors Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise but insight-rich preview of our forthcoming PM2.5 Monitors Market study. This piece is designed to orient senior executives, procurement leads, investors, and public-sector planners as they set priorities for 2026. It demonstrates the analytical depth of the full report while deliberately withholding granular segmentation outputs and proprietary scorecards — the exact intelligence that will drive operational choices and M&A moves is available in the complete study on our website.
PM2.5 Monitors Market
Market trajectory you need to internalize
The PM2.5 monitors market has moved from a niche regulatory niche into a mainstream technology category that straddles environmental policy, public health, and IoT-enabled services. Our modeling, based on a detailed historical series (2020–2025) and an explicit forecast window (2026–2032), shows a clear expansion path: the market reached an institutionalized scale by the 2025 base year and is projected to grow at a compounded annual growth rate (CAGR) of roughly 6.98% across the forecast period. By the end of the outlook horizon, the market is materially larger than in 2025, reflecting both sustained regulatory upgrade cycles and growing private-sector adoption of continuous monitoring.
PM2.5 Monitors Market
For executives, the takeaway is simple: procurement, product development, and channel strategies framed around a single-year mindset will miss the structural growth in demand. Capital allocation for monitoring networks, service contracts, and data platforms must be planned across multi-year tranches to align with regulatory timetables and technology refresh cycles.
PM2.5 Monitors Market
Regulatory inflection points that accelerate demand
-
Standard tightening: The U.S. Environmental Protection Agency’s reduction of the primary annual PM2.5 National Ambient Air Quality Standard has been a catalyst for network upgrades. That regulatory tightening translated into practical procurement waves as networks moved to comply with stricter thresholds.
-
Method designations and approvals: Updated lists of reference and equivalent methods (including recent designations in late 2025) directly alter the vendor landscape by elevating devices that meet reference-grade performance. Vendors that hold or actively pursue these designations become default suppliers for regulated networks and competitive in bid processes for municipal and state contracts.
-
Network modernization: Several jurisdictions that historically relied on filter-based FRMs have transitioned to continuous analyzers. That shift has implications for capital timing, operational budgets, and data comparability between legacy and modern systems.
These regulatory signals are not academic. They create discrete windows during which municipalities and national authorities commit to upgrade or expand monitoring capacity — windows that vendors, integrators, and financiers must target with tailored offerings and finance structures.
Competitive landscape: fragmented but credibility-driven
The market remains moderately fragmented, with top-tier suppliers accounting for a small but meaningful slice of global revenue. Market concentration metrics indicate that the largest three players control roughly a quarter of the market, with the top five approaching one-third — a structure that favors both specialized entrants and consolidation plays. In practice, this means two viable strategic postures for vendors and investors: commit to scale and pursue consolidation, or specialize deeply in validated reference-grade instrumentation and data services.
Key vendor archetypes and implications:
-
Regulatory reference-grade incumbents: Established manufacturers offering FRM/FEM-capable instruments have a durable advantage for government networks. Their certification pathways and long-term service arrangements often secure multi-year revenues tied to network operations. Recent EPA-level designations have reinforced the market positions of several long-standing suppliers.
-
Innovative entrants with validated performance: Newer vendors that obtain reference- or equivalent-method recognition can leapfrog into regulated procurements. Certification events in 2025 demonstrate that when a device proves reference-grade performance, market access expands rapidly.
-
Portable and citizen-science players: The lower-cost, portable, and wearable segments are expanding in parallel — driven by corporate wellness, smart-building applications, and consumer awareness. These devices shift the competitive focus toward sensor calibration, data harmonization, and lightweight analytics rather than pure hardware sales.
-
Systems and platform integrators: Firms that combine hardware supply with cloud-based analytics, QA/QC workflows, and managed services can capture higher-margin recurring revenue and lock in long-term data service contracts with municipal and enterprise clients.
Representative vendors covered in the full study — spanning reference-grade manufacturers, OEMs of beta attenuation and tapered element oscillating microbalance (TEOM) systems, portable sensor specialists, and integrators — are analyzed across validation status, route-to-market, service footprint, and capability synergies. Recent developments we track carefully include the EPA’s late-2025 designations and high-profile vendor certifications that materially affect competitive positioning.
What the PW Consulting report delivers (practical, operational outputs)
-
Robust market sizing and a transparent forecasting model (history: 2020–2025; forecast: 2026–2032) that links demand to regulatory milestones, capex cycles, and product lifespans.
-
A regulatory tracker that maps designation timelines, standard setting, and state-level network plans to procurement windows.
-
Vendor profiles and a comparative framework that score firms on validation status, installed base, service capability, and platform readiness.
-
Technology assessment covering measurement principles (beta attenuation, TEOM, optical particle counters, gravimetric samplers), drift characteristics, calibration strategies, and IoT integration patterns.
-
Go-to-market playbooks for manufacturers and system integrators: RFP tactics, financing structures for fleet upgrades, and channel strategies for hybrid public–private opportunities.
-
Procurement and specification checklists, including QA/QC process templates and sample bid evaluation criteria tailored for municipal and corporate buyers.
-
Scenario-based investment cases and M&A target shortlists for strategic acquirers and private equity, with metrics to prioritize candidates.
-
Methodology appendix: primary interviews, calibration lab validations, and sensitivity testing so buyers and investors can audit our assumptions.
To preserve the tactical value of our analysis for subscribers, the full report refrains from public disclosure of proprietary segment splits and device-level pricing benchmarks. Those items are available exclusively in the paid study and are unavoidable inputs when executing procurement or M&A activity.
Strategic implications for 2026 planning — by stakeholder
-
Municipal and state air agencies: Prioritize interoperability and device validation. Where possible, procure FEM/FRM-designated instruments for compliance networks and leverage hybrid strategies (continuous analyzers + low-cost sensor arrays) to expand spatial coverage without compromising compliance-grade data.
-
Equipment manufacturers: Invest in demonstration programs that accelerate recognition by regulatory authorities. Certification is a gateway to the largest and stickiest contracts; concurrent investments in aftermarket services can convert hardware sales into recurring revenue.
-
Systems integrators and platform providers: Build standardized ingestion pipelines and QA/QC toolsets that normalize data across device types and generations. Offer managed services that reduce operational burden for public-sector customers facing tight budgets.
-
Investors and acquirers: Look for targets with validated measurement performance, strong service contracts, or cloud analytics that promise recurring cash flow. The relatively modest headroom in market concentration suggests attractive roll-up opportunities in regional markets.
-
Corporate sustainability teams: Factor in multi-year replacement cycles and data quality requirements when specifying monitors for campuses and facilities. High-frequency, verifiable data becomes a corporate asset for regulatory engagement and stakeholder communication.
Immediate next steps for teams planning 2026 budgets and programs
-
Map compliance timelines against capital planning cycles. Use multi-year procurement frameworks to smooth budget impact and secure vendor lead times.
-
Prioritize pilot projects that pair certified reference instruments with low-cost sensor networks to validate hybrid approaches under local conditions.
-
Require vendor demonstrations tied to QA/QC acceptance criteria and ensure long-term maintenance contracts are benchmarked professionally.
-
Engage early with potential partners who have confirmed method designations or who are on certification roadmaps; that shortens procurement cycles and mitigates regulatory misalignment risk.
Our full PM2.5 Monitors Market report unpacks these actions into executable timelines, vendor scorecards, and procurement-ready specifications. It is intentionally structured as a decision-support tool for teams that must translate regulatory pressure into compliant, cost-effective monitoring networks.
How to access the complete intelligence
This preview highlights the strategic arcs and high-level metrics you need to include in 2026 planning. The full report contains the proprietary segmentation, vendor rankings, pricing matrices, and downloadable models that your procurement, product, or M&A teams will use to finalize decisions. Visit the PW Consulting research portal to review the executive package, secure client briefings, and access our modeling toolkit.
If you would like a tailored briefing for your organization — including scenario modeling against your specific fleet, geography, and budget constraints — our consultants are available to convert the study’s insights into a 90-day action plan.
For detailed analysis of this topic, please visit the official page: PM2.5 Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Car Entertainment Systems to hit USD 345.4M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-30
Car Entertainment System Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused preview of our latest Car Entertainment System Market study — a strategic briefing designed to shape executive decisions in 2026. The market has entered a new phase: from a recovery and digital-integration cycle in the early 2020s to a sustained expansion driven by software-defined vehicle architectures, immersive in-cabin experiences, and tighter integration between infotainment and safety domains. Using 2025 as the base year, our modeling shows the global market expanding from approximately USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and forecasted to reach USD 345.4 Million by 2032, representing a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 period. This trajectory creates windows of opportunity — and distinct execution risks — that require targeted strategic action in 2026.
Car Entertainment System Market
Why this study matters for 2026 decision-makers
-
Timing of platform bets: The industry is shifting from hardware-led differentiation to software- and services-led differentiation. OEMs and Tier‑1 suppliers who decide on platform architectures and software partnerships in 2026 will lock in multi-year product roadmaps and partner ecosystems.
Car Entertainment System Market -
Monetization inflection: Subscription models, over‑the‑air (OTA) feature rollouts, and aftermarket upgrade pathways are moving from pilot projects to commercial programs. Strategic choices on pricing, feature bundling, and revenue-sharing will materially affect lifetime value.
Car Entertainment System Market -
Certification and regulatory alignment: New certification frameworks for Android Automotive and AAOS-based IVI systems introduce compliance overheads and preferred testing routes—decisions on where and how to validate systems now carry program-level implications.
-
Consolidation and supplier strategy: The market remains relatively fragmented (CR3 ~24.6%; CR5 ~26.2%), creating a dual dynamic — room for niche innovation and an attractive runway for consolidation. Strategic M&A, joint ventures, or exclusive supply agreements could be decisive moves in 2026.
What the full report delivers (actionable, not academic)
-
Proprietary market sizing and forecasting model (base year 2025; historic tail to 2020; forecast 2026–2032) with scenario outputs for high/medium/low adoption pathways, enabling sensitivity analysis for CAPEX and revenue planning.
-
Technology radar that ranks platform approaches (native AAOS vs. proprietary stacks), audio and display innovations (spatial audio, HDR certifications), SoC integration strategies, and connectivity/vehicle domain convergence.
-
Commercial playbooks: OEM vs. aftermarket go‑to‑market templates, pricing and subscription frameworks, partner selection checklists, and go/no-go gates for feature monetization pilots.
-
Operational toolkits: supplier sourcing scorecards, qualification matrix for IC and SoC partners, certification roadmaps (including Android Automotive/AAOS testing), and a compliance impact matrix for procurement and quality teams.
-
M&A and partnership playbook: valuation benchmarks, consolidation scenarios, and integration risk checklists tailored to the current fragmentation levels and competitive dynamics.
-
Risk scenarios and mitigation: supply-chain shocks, software security incidents, regulatory shifts, and consumer-UX adoption hurdles — each with contingency plans and milestones for 12‑ to 36‑month horizons.
Competitive landscape: how to read incumbent moves
Our competitive analysis focuses on strategic positioning, software and ecosystem relationships, product roadmaps, and commercial reach. Below are the key players and the implications of their recent moves.
-
Harman International (Stamford, CT) — Strengths: premium connected systems, immersive audio, integrated UX. Strategic signal: Harman’s industry-first HDR10+ automotive certification (announced late 2025 / reinforced in 2026) is evidence of investment in media-quality differentiation and OEM co-development for premium segments. For partners, Harman represents a platform play for experiential, content-driven monetization.
-
Pioneer Corporation (Tokyo) — Strengths: aftermarket leadership, navigation and audio systems. Strategic signal: Pioneer’s SPHERA (early 2026) — an aftermarket in-dash receiver embedding Dolby Atmos into Apple CarPlay — underscores the aftermarket as a rapid-prototyping ground for advanced audio UX and a channel to capture incremental consumer spend. OEMs should watch aftermarket innovations as demand signals for future OEM features.
-
DENSO TEN Limited (Kobe) — Strengths: AV products and automotive electronics. Strategic signal: DENSO TEN continues to play the classic Tier‑1 role — integrating hardware reliability with evolving software stacks — making it a candidate partner for OEMs prioritizing integration depth and production-grade quality.
-
Panasonic Automotive Systems (Yokohama) — Strengths: in‑vehicle infotainment, navigation, premium audio. Strategic signal: Panasonic’s systems remain attractive to OEM programs that seek end‑to‑end integration across cabin subsystems and premium UX. The firm’s focus on modular IVI platforms supports faster OEM time-to-market.
-
Mitsubishi Electric Automotive America (Northville, MI) — Strengths: connected infotainment, integrated cockpit, rear-seat entertainment. Strategic signal: Mitsubishi Electric is positioned to capture platforms that require heterogeneous cockpit experiences across occupant zones — a growing demand vector as vehicle interiors become multi-purpose spaces.
-
Bosch (Stuttgart) — Strengths: infotainment ECUs, central computing, connectivity. Strategic signal: At CES 2026 Bosch demonstrated a fusion of infotainment and driver assistance on a single SoC-based cockpit & ADAS integration platform. That convergence underscores a strategic tilt toward domain consolidation — a structural shift that will redefine supplier boundaries and integration complexity.
-
Continental AG (Hanover) — Strengths: information management, connectivity solutions. Strategic signal: Continental remains a key systems integrator; its strength in connectivity and data management positions it for roles in vehicle-to-cloud monetization and centralized cockpit services.
Additional market activity (e.g., Fiacre Telematics’ showcase of commercial-vehicle infotainment at mobility expos) evidences niche growth vectors where customized solutions and regional regulatory alignment matter most.
Regulatory and certification dynamics to watch in 2026
-
P3 Group’s role as Google’s third‑party laboratory for Android Automotive testing and the formalization of AAOS certification frameworks creates a de facto gate for many OEMs and suppliers. This reduces technical ambiguity but raises program costs and time-to-certification.
-
Practical implication: product teams must bake AAOS test plans into development sprints, and procurement must select certified test partners early to avoid downstream delays. The report includes an executable certification checklist and vendor selection rubric.
Priority strategic moves for 2026
-
Embed software-first thinking into product roadmaps: Move from one-off feature launches to modular, OTA-enabled platforms with clear update governance and rollback plans.
-
Lock in certification pathways early: Allocate budget and program timelines for AAOS certification and preferred third‑party lab engagements.
-
Define clear monetization experiments: Pilot subscriptions and feature tiers in targeted regions or customer segments; instrument pilots to capture conversion and churn metrics.
-
Prioritize integrations that reduce system complexity: Consider consolidation of cockpit domains where safety‑critical and infotainment workloads converge; evaluate SoC partners with demonstrated multi-domain performance.
-
Build strategic partnerships across the ecosystem: app-platform providers, cloud service vendors, audio content partners, and certified test labs — not just hardware vendors.
-
Use M&A selectively to accelerate capability gaps: With modest top-5 concentration, tuck-in acquisitions or JV structures can quickly secure software talent, content deals, or aftermarket distribution.
-
Invest in cybersecurity and privacy-by-design: With increasing vehicle connectivity, embedded IVI systems are high-value targets; security investments must be part of the product budget, not an afterthought.
How PW Consulting can accelerate your 2026 program
Our full Car Entertainment System Market report is built as an execution guide: downloadable financial models, procurement scorecards, certification roadmaps, a partner‑selection matrix, and scenario-based investment cases tuned to the 2026 decision calendar. The public preview you’re reading now intentionally omits granular segment breakouts and granular regional/application-level revenue tables — those detailed splits and program-level benchmarks are included in the subscriber report to preserve commercial integrity and to give paying clients immediate, prioritized value.
If your 2026 roadmap requires defensible investment cases, faster certification, or a market-entry playbook for OEM and aftermarket channels, the full study provides the templates and advisory engagement options to convert strategic intent into milestones and measurable outcomes.
In short: the Car Entertainment Systems market is growing, recentering around software and experiential differentiation, and is opening strategic windows for firms that move decisively in 2026. Our report tells you where to place those bets and how to reduce execution risk — with the granular segment data and region/application splits available in the full release.
For detailed analysis of this topic, please visit the official page: Car Entertainment System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acoustic Saxophone Market to Reach USD 344.8M by 2032 at 5.8% CAGR
By pmarketresearch, 2026-07-30
Acoustic Saxophone Market 2026: Strategic Imperatives for Industry Leaders
Executive snapshot
As PW Consulting’s lead industry analyst, this introduction frames the strategic value of our Acoustic Saxophone Market study for corporate decision-making in 2026. The market has shown resilient expansion through the recent cycle — rising from USD 163.15 Million in 2020 to USD 215.0 Million in our base year (2025) — and is projected to continue on an upward trajectory, reaching approximately USD 344.8 Million by 2032. Our forecast period (2026–2032) models a compound annual growth rate (CAGR) of 5.8% (USD, revenue unit: Million). These macro dynamics create a window of opportunity for product innovation, channel optimization, and strategic consolidation, but they also mask acute operational risks that require active mitigation.
Acoustic Saxophone Market
Why this study matters for decisions in 2026
-
Timing: 2026 is a pivot year. Demand signals (new product uptake, sustained consumer interest in performance-grade instruments, and growing amateur participation) intersect with supply-side shocks and regulatory shifts. Executives who align portfolio decisions with the quantitative scenarios in this report will be better positioned to capture premium segments and protect margins.
Acoustic Saxophone Market -
Clarity on scale and slope: The market’s scale in 2025 and the trajectory to 2032 provide the necessary context to evaluate R&D programs, capacity investments, and channel expansion initiatives. Treat the reported CAGR as a directional planning baseline; our study overlays it with scenario-specific demand elasticity and product lifecycle assumptions to support capex and go-to-market timing choices.
Acoustic Saxophone Market -
Competitive posture: Market concentration is meaningful — the top three players account for a majority share (CR3 ~55%), and the top five control roughly four-fifths of the market (CR5 ~80%). These metrics underscore a marketplace where scale economies, brand heritage, and distribution depth materially affect pricing power and entry barriers.
Market dynamics shaping strategic options
The acoustic saxophone market in 2026 is being reshaped by four linked forces: cost inflation in raw materials, production footprint reconfiguration, product innovation driving premium demand, and evolving go-to-market models.
-
Input-cost pressure and supply disruption: Brass raw-material costs jumped materially (industry data shows a 27% increase in 2023), a shock that reverberated through manufacturing margins and logistics. That spike contributed to delivery delays — in some regions, delays impacted over 7% of planned shipments — and forced manufacturers to reassess inventory buffers, hedging strategies and supplier diversification.
-
Manufacturing geography and regulatory impact: Confirmed facility closures and relocations are changing competitive calculus. Recent regulatory filings show at least one major U.S. manufacturer moving operations offshore, while others preserve European artisanal capacity for premium lines. These structural moves create trade-offs between labor cost, lead time, and "made-in" brand equity that firms must quantify when deciding localization vs. centralization.
-
Product-led differentiation: 2026 product activity demonstrates the market's bifurcation. Leading manufacturers launched new professional and ergonomic lines early in the year; in short order, some introductions achieved material unit velocity (e.g., an advanced alto model surpassed notable unit sales within months, and a newly designed ergonomic student/intermediate line exceeded ten-thousand-unit thresholds by year-end). This validates premiumization strategies, but it also signals that product quality, playability, and resonance innovation remain primary purchase drivers.
-
Channel and aftermarket evolution: Retail and education channels are evolving. Bundled offers for learning & training, extended warranties, and bespoke customization services are increasing lifetime value. Digital direct-to-consumer channels and enhanced service models are rapidly becoming differentiators, particularly for mid- and high-end customers seeking customization and fast service.
Competitive landscape — what the leading firms reveal
The market is anchored by a mix of multinational incumbents and specialized craftsmen. Profiles of core competitors illustrate three competing strategic logics:
-
Scale and breadth (global OEMs): Established manufacturers with broad portfolios leverage distribution reach and multi-brand strategies to serve student-to-professional segments. Their priorities in 2026 are cost mitigation, channel optimization, and incremental product upgrades to protect volume.
-
Specialist premium manufacturers: Artisan and boutique makers emphasize tonal heritage, ergonomics, and finish options. They preserve margin through craftsmanship and limited runs, benefiting from demand for bespoke and stage-ready instruments.
-
Value-driven mass-market producers: Firms focusing on durability and price performance target education and amateur segments, investing in robust designs and ergonomic improvements to reduce churn and increase unit velocity in institutional channels.
These archetypes are embodied by well-known companies across the industry: multinational instrument houses that combine institutional OEM scale with student and professional lines; boutique craftspeople who drive high-margin customization; and competitive Taiwanese and Japanese manufacturers who balance cost, quality and distribution. The market concentration noted earlier amplifies the advantage of incumbency but also surfaces attractive acquisition targets among smaller players whose manufacturing techniques, IP or niche brand equity complement larger portfolios.
What the report delivers (practical contents)
Our full PW Consulting study equips commercial, product and corporate strategy teams with tools and templates to act in 2026. Highlights include:
-
Market sizing & forecasts: Modeled to 2032 with scenario overlays (base, upside, downside) and sensitivity to raw-material and labor-price shocks.
-
Demand-driver analysis: Consumer segmentation, purchase triggers across professional, education and amateur cohorts, and unit economics for each cohort.
-
Channel & pricing playbook: Margin maps by channel, distribution recommendations, recommended retail pricing bands for staged product rollouts, and cross-sell/up-sell strategies for accessories and services.
-
Manufacturing & sourcing stress tests: Cost-pass-through models, supplier risk matrices, and relocation-impact simulations that quantify trade-offs between labor cost savings and brand/lead-time penalties.
-
Competitive heat maps: Strategic benchmarking against the leading manufacturers (including strengths in scale, product craftsmanship, innovation cadence, and channel penetration) and an M&A target shortlist defined by strategic fit and integration risk.
-
Operational playbooks: Tactical guidance for inventory hedging, material procurement strategies, localized production pilots, and aftermarket service programs to protect revenue during supply shocks.
-
Risk register & regulatory implications: Focused sections on labor and trade policy shifts, including implications of recent facility relocations and evidence of maintained artisanal production sites in Europe for premium lines.
Strategic recommendations for 2026
-
Hedge and diversify brass supply: Implement multi-sourcing contracts, explore alloy substitutes where acoustically acceptable, and contractually secure lead times for critical components to avoid delivery slippage across priority markets.
-
Dual-track manufacturing strategy: Preserve artisanal lines for brand-sensitive professional offerings while selectively outsourcing high-volume student models. Quantify the premium consumers attach to provenance and use it to defend margins on premium SKUs.
-
Accelerate product-led premiumization: Invest in ergonomic and acoustic R&D that can be monetized through limited-run premium finishes and customization options, informed by rapid-launch learnings from early-2026 introductions.
-
Rebalance channel mix toward direct engagement: Build or expand DTC channels and aftermarket service capabilities to increase lifetime value and improve customer learning pathways (student → intermediate → professional).
-
Pursue targeted inorganic moves: Use the current consolidation dynamics to acquire specialist makers or component technologies that augment IP, shorten time-to-market for premium features, or close distribution gaps.
Conclusion — the strategic payoff
Our analysis shows that the acoustic saxophone market’s growth to 2032 is substantial enough to justify measured investment, but the pathway to margin expansion is conditional on how companies manage supply risk, product differentiation and channel economics. With a concentrated competitive structure and confirmed cost shocks, 2026 is a decisive year for firms to reposition: those that combine disciplined sourcing, selective localization, and product-led premiumization will expand share and margin; those that delay will face margin compression or distribution erosion.
The full PW Consulting Acoustic Saxophone Market report contains the detailed segment-level breakouts, channel maps, company-by-company benchmarking and executable playbooks required to convert these insights into concrete 2026 action plans. For practitioners seeking the underlying data and strategic templates, the complete intelligence is available on our report page.
For detailed analysis of this topic, please visit the official page: Acoustic Saxophone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV & Fuel Cell Vehicles Market to Reach USD 539B by 2032
By pmarketresearch, 2026-07-30
Electric Vehicles and Fuel Cell Vehicles Market — Strategic Insights for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concentrated briefing that translates our latest Electric Vehicles (EV) and Fuel Cell Vehicles (FCEV) Market study into immediate strategic value for executives planning 2026 moves. This piece follows a “trailer” approach: it surfaces the analytical rigor and directional findings you need to judge relevance, while preserving the granular segmented datasets and proprietary models that are accessible in the full report.
Electric Vehicles and Fuel Cell Vehicles Market
Executive snapshot — the market in context
Our analysis uses 2025 as the base year, reviews historical trends from 2020–2025, and models a 2026–2032 forecast horizon. The combined EV + FCEV market has transitioned from an emerging growth phase into a structural build-out: from roughly USD 163 billion in 2020 it expanded to about USD 215 billion by 2025, and our baseline forecast projects the market to surpass USD 500 billion by the early 2030s. The modeled compound annual growth rate (CAGR) for the forecast window is 14.06%, reflecting sustained demand, vehicle electrification momentum, and progressive technology cost curves.
Electric Vehicles and Fuel Cell Vehicles Market
These headline numbers frame several practical implications for corporate strategy in 2026: the market is large enough to justify scale investments but still diffuse enough that differentiated plays, partnerships and selective vertical integration can materially change competitive positions.
Electric Vehicles and Fuel Cell Vehicles Market
Why this research matters for 2026 decision-making
- Timing and investment calibration:
With double-digit structural growth baked into our baseline, firms must decide in 2026 whether to accelerate capital deployment (manufacturing, assembly lines, hydrogen fueling partnerships) or to stage investments to capture margin improvement from technology learning curves. The market trajectory supports aggressive scaling for players who can reduce unit costs quickly; it also rewards targeted pilots for those prioritizing route optimization and customer experience.
- Product and portfolio choices:
Automakers and fleets face trade-offs among battery-electric, fuel-cell, and hybrid platforms. Regulation-driven affordability initiatives and shifting consumer segments mean product roadmaps should be optimized not only on unit economics but also on lifecycle emissions compliance and total cost of ownership at the fleet level.
- Supply chain de-risking:
Raw material and component cost targets announced by governments and industry bodies — including fuel cell cost milestones and hydrogen production targets — create actionable procurement triggers. 2026 is the year to lock multi-year agreements, qualify secondary suppliers, and invest in recycling or substitution research to mitigate PGM exposure and upstream bottlenecks.
- Regulatory and market-access playbooks:
New CO2 standards, incentive rebalances and regional policy shifts have made market-entry conditional on well-orchestrated pricing and compliance strategies. Positioning product variants to meet affordability thresholds and navigating region-specific registration dynamics are critical tactical priorities for 2026 launches.
What the report delivers — practical, decision-ready outputs
- High-fidelity market sizing and 2026–2032 forecasts (including scenario and sensitivity analyses).
- Actionable go-to-market roadmaps for OEMs, Tier-1 suppliers, fleet operators, and infrastructure investors.
- Technology and cost trajectories (battery, fuel cell stacks, power electronics, hydrogen handling) with break-even timelines and unit-cost ladders.
- Supplier and partner heatmaps, including capability matrices to expedite procurement and JV screening.
- Regulatory and incentives tracker mapped to commercialization milestones and launch windows.
- Investment case templates, M&A screens, and financial models calibrated to risk-adjusted returns under alternate adoption curves.
- Field-tested pilot blueprints, procurement clauses, and go/no-go decision checkpoints for 0–24 month programs.
Note: the report includes full regional and application segmentations and the underlying datasets that support these deliverables; selective high-level figures and trends are presented here to demonstrate methodological rigor while preserving the proprietary segmentation tables for report subscribers.
Competitive landscape — companies to watch in 2026
- Toyota Motor Corporation (Toyota City, Japan)
Strategic posture: Toyota continues to play a foundational role in fuel-cell commercialization, leveraging product iterations and system-level engineering to expand applicability across passenger, commercial and heavy-duty segments. The company’s announcement of a third-generation fuel cell system slated for multi-region rollout underscores a push to improve durability and lower lifecycle costs. For competitors and partners, Toyota’s scale and system know-how make it both a potential collaborator and a benchmark for component reliability.
- Hyundai Motor Company (Seoul, South Korea)
Strategic posture: Hyundai’s broad product set — spanning passenger vehicles to hydrogen trucks and buses — positions it to capture diverse hydrogen demand pockets. The refresh cycles for fuel-cell models and commercial vehicle developments suggest a playbook focused on platform reuse and aftermarket services as levers to monetize hydrogen ecosystems.
- Honda Motor Co., Ltd. (Tokyo, Japan)
Strategic posture: Honda’s move to produce plug-in fuel cell variants in the U.S. signals an emphasis on localized manufacturing and market-specific product adaptation. This highlights an operational theme for 2026: OEMs that marry regional production footprints with local policy engagement can accelerate market access while containing logistics costs.
- BMW AG (Munich, Germany)
Strategic posture: BMW’s planned series production of fuel-cell vehicles, leveraging collaborative technology pathways, reveals a risk-managed approach to hydrogen. By combining licensing/partnered technology with scaled manufacturing intent, BMW illustrates an approach suited to premium segments where value capture can justify higher early-cycle costs.
- Nippon Shokubai Co., Ltd. (Tokyo, Japan)
Strategic posture: Component and catalyst innovators are critical enablers of cost reduction. Advances in platinum-group-metal-free catalysts and related materials science are a lever for industrial players to outflank raw-material constraints and to reduce stack costs — an outcome that materially affects heavy-duty total cost equations.
Complementing these OEM and supplier dynamics, product expansions from specialist suppliers (hydrogen recirculation, blowers, system integrators) are sharpening the ecosystem, creating new supplier niches and partnership options. The market concentration metrics indicate a relatively unconsolidated landscape, providing opportunities for agile entrants and focused consolidations.
Industry dynamics and critical external signals
- Policy acceleration: Tighter CO2 standards and region-level mandates are reshaping pricing and portfolio decisions; affordability-driven product introductions are increasingly important.
- Adoption scale: Global electric car sales hit record volumes in 2025, reinforcing electrification as mainstream; this scale validates network and after-sales investments.
- Cost targets: Public-sector technology targets for fuel cell stack costs and hydrogen production create clear commercial inflection points — hitting those targets materially improves heavy-duty and long-haul business cases.
- Localized friction points: Early signs of registration slowdowns in some FCEV registries highlight the need to pair vehicle launches with refueling infrastructure and customer value propositions.
Scenario planning — triggers that change the game
- Base case: Realization of the modeled CAGR and infrastructural rollouts in line with public targets; gradual cost declines enable broadening commercial adoption.
- Upside case: Faster-than-expected hydrogen production cost reductions and accelerated fuel-cell cost improvements unlock rapid heavy-duty electrification and industrial-scale fleet conversions.
- Downside case: Raw-material shocks, slower infrastructure scaling, or policy reversals compress adoption rates and push ROI timelines beyond early investors’ thresholds.
Concrete 2026 actions — prioritized
- Immediate (0–12 months):
Secure supply hedges for key materials, finalize pilots with targeted fleet partners, and lock conditional offtake or offtake-linked financing for infrastructure projects. Use modular procurement templates to speed RFP cycles while retaining flexibility for design evolution.
- Near-term (12–36 months):
Scale production in regions where regulatory and cost conditions align, negotiate technology partnerships for stack and system integration, and build bundled service offerings (vehicle + refueling + telematics) to improve payback for fleet customers.
- Strategic (36+ months):
Pursue consolidation in targeted supplier segments, vertically integrate critical modules if warranted by scale economics, and consider cross-sector alliances to accelerate hydrogen supply and amortize infrastructure investments.
Final word — using this research in 2026
The 2026 strategic window is defined by a large and fast-growing total market, significant technology milestones within reach, and uneven but accelerating infrastructure development. PW Consulting’s EV & FCEV Market study equips decision-makers with the scenario-based forecasts, cost curves, supplier maps and executable playbooks needed to convert market opportunity into competitive advantage. If your 2026 decisions involve capacity commitments, product launches, M&A, or infrastructure investments, the full report will provide the segmented forecasts, model inputs and executable templates to move from intent to impact.
To access the complete datasets, regional and application breakdowns, and the operational toolkits referenced above, please consult the PW Consulting EV & FCEV Market report page or contact our advisory team to arrange a briefing and licensing of the full analytical package.
For detailed analysis of this topic, please visit the official page: Electric Vehicles and Fuel Cell Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com