

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
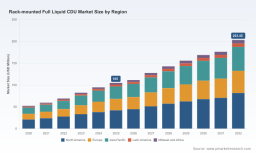
PW Consulting: Rack‑mounted Full Liquid CDU Market to Nearly Double from USD 105.0 Million in 2025 to USD 203.45 Million by 2032 at a 9.85% CAGR — North America (~42%) and Liquid‑to‑Liquid CDUs (~68.5%) Drive Demand

PW Consulting Releases Strategic Brief: Rack-mounted Full Liquid CDU Market — A Decision-Grade Preview for 2026
PW Consulting’s latest industry study on the Rack-mounted Full Liquid Coolant Distribution Unit (CDU) market delivers executive-grade intelligence designed to influence procurement, engineering and capital-allocation decisions in 2026. Our analysis synthesizes historical build rates (2020–2025), near-term market sizing and a 2026–2032 forecast horizon, and couples quantitative projections with operational playbooks for data center owners, hyperscalers, OEMs and systems integrators. This release is a curated preview: it exposes the strategic findings and actionable recommendations you need to decide quickly, while preserving the report’s granular tables and vendor-level scorecards for subscribers.
Driven Hydraulic Wrench Market
Market at a Glance — Why 2026 Is a Pivotal Year
The rack-mounted full liquid CDU market has moved from an early adoption phase into a structured growth market. PW Consulting estimates the market value reached USD 105.0 Million (base year 2025) and is forecast to grow at a compound annual growth rate (CAGR) of 9.85% over the 2026–2032 period, roughly doubling in value by 2032. This trajectory reflects a confluence of forces: the accelerated deployment of GPU-dense AI racks and HPC clusters, tighter facility reliability standards, and a shift toward higher coolant temperatures and direct-to-chip heat extraction strategies.
Ionizing Radiation Precision Instruments Market
Concentration metrics in the competitive landscape indicate a moderately consolidated market: the top three suppliers account for just under half of market revenue, while the top five push well beyond the halfway mark. This structure creates clear zones of competition — entrenched leaders who control scale and channel access, and nimble challengers who compete on modularity, thermal performance or integration services.
Worldwide Parenteral Nutrition Fat Emulsion Market
What the Report Delivers — Practical, Executable Assets
- Operational Playbooks: Installation-validated checklists for rack-level CDU deployment (electrical, hydraulic, piping isolation and commissioning sequences), plus integration blueprints for direct-to-chip and cold-plate architectures.
- Procurement & Vendor Selection Toolkit: RFP templates, evaluation rubrics, SLA clause libraries and spare-parts agreements tailored to rack-mounted CDU lifecycles.
- TCO & Scenario Models: Proprietary total-cost-of-ownership calculators that factor CapEx, energy impacts, fluid chemistry, maintenance regimes and asset modularity; editable scenario files for sensitivity analysis across electricity prices, inlet approach temperatures and failure rates.
- Regulatory & Standards Roadmap: Compliance checklists and adoption pathways aligned with the latest ASHRAE TC 9.9 guidance and forthcoming addenda to Standard 127 — essential for separating Facility Water Systems (FWS) and Technology Cooling Systems (TCS) and for credible performance certification.
- Supplier Scorecards & Shortlists: A synthesized vendor assessment across technology fit, scalability, service footprint and supply-chain risk — enabling rapid down-selection for pilots and production rollouts.
- Executive Briefings & Board-Ready Slides: Decision-support packages focused on purchase timing, financing alternatives, and integration timelines for AI/HPC procurement cycles.
Strategic Implications for 2026 Decision-Makers
- Operational resilience over lowest upfront price: With ASHRAE guidance emphasizing separation of FWS and TCS, data center operators should prioritize CDUs that offer certified isolation barriers, redundant or hot-swappable pumping, and clear serviceability access. The report maps failure-mode impacts to service-level targets so CFOs and CTOs can align on acceptable residual risk.
- Design for modular scale: GPU and accelerator densities are evolving quickly. Units that support modular scaling — from rack-level up to multi-rack clusters with predictable hydraulic balancing — reduce retrofit costs and shorten time-to-capacity.
- Thermal strategy matters: Narrow approach temperatures and elevated water operating points unlock higher free-cooling and waste-heat recovery opportunities. However, these choices carry implications for fluid selection, certification and supplier life-cycle support; our TCO models quantify the break-even across common design options.
- Supply-chain & materials vigilance: Global phase-downs of certain refrigerants and evolving supplier certification requirements raise component lead times and compliance costs. Procurement teams should integrate material-certification clauses into long-term contracts and build multi-sourcing where practical.
- Choose partners with end-to-end capabilities: Integration risk is frequently the largest hidden cost. Vendors that combine CDU hardware with controls, lifecycle services and rapid global spare-part support deliver lower total operational disruption during scale-up and peak load migration.
Competitive Landscape — Who Matters and Why
PW Consulting’s market mapping identifies a diverse set of influential suppliers, each presenting different value propositions for 2026 deployments:
- CoolIT Systems (Calgary, Canada) — Known for high-performance in-rack CDUs (CHx200, CHx80) optimized for dense HPC and AI servers; strength lies in compact liquid-to-liquid modules designed for direct integration with high-power servers.
- Super Micro Computer / Supermicro (San Jose, USA) — Offers in-rack and in-row CDUs with redundant, hot-swappable pumps and very high unit capacities; their systems are attractive to integrators needing rack-level resilience and vendor-aligned server fitment.
- DCX Liquid Cooling Systems (Warsaw, Poland) — Focuses on compact, high-capacity liquid-to-liquid CDUs (HYDRO CDU1) for AI centers where per-rack power density and minimized footprint are decisive.
- LiquidStack (Carrollton, USA) — Delivers solutions supporting narrow approach temperatures and elevated water operation for ultra-high-density deployments, with offerings that scale to very high per-unit capacities.
- Flex (via JetCool) (Austin, USA) — Recently launched modular rack-level CDU platforms that emphasize scalability (announced 2025), signaling a move towards large-scale, OEM-backed modular solutions for hyperscalers.
- Motivair (by Schneider Electric) (Lancaster, USA) — Recently announced scalable CDUs targeting next-generation AI deployments (January 2026), leveraging Schneider’s systems integration depth for floor-to-rack solutions.
- Asetek (Denmark) — Competes on warm-water InRackCDU systems for efficient, serviceable rack cooling where moderate per-rack capacities are the design point.
- nVent (Minneapolis, USA), Dell Technologies (Round Rock, USA), Eaton (Dublin/US operations) — These established players bring reliability, channel reach and integration services; they are frequently preferred when operators prioritize vendor consolidation and enterprise-grade support.
Recent product moves — such as Flex’s modular launch in late 2025 and Motivair’s high-capacity MCDU announcement in early 2026 — highlight a competitive emphasis on modular scalability and higher per-rack capacities. Dell’s continued promotion of rack-mount RCDU solutions reinforces that major OEMs are actively positioning to supply integrated server/CDU stacks for AI and HPC customers.
Regulatory & Standards Context — What Keeps Risk Managers Awake
Two regulatory trends should be part of every 2026 procurement checklist. First, ASHRAE TC 9.9’s recent emphasis on CDU-based isolation between Facility Water Systems and Technology Cooling Systems elevates design review requirements for third-party certs and field commissioning documentation. Second, updates to ASHRAE Standard 127 (with new test-method addenda covering liquid-to-liquid CDUs) will change how suppliers’ performance claims are validated — and therefore how buyers compare products on an apples-to-apples basis.
Finally, environmental policy levers — including the Kigali Amendment’s phase-down of specific refrigerants — are increasing certification and compliance costs for thermal components and may alter supplier cost structures and lead times. Our report provides mitigation strategies, recommended contractual protections and sourcing pathways that limit exposure to material-driven cost escalation.
How PW Consulting’s Report Supports Tactical Pilots and Strategic Roadmaps
- Pilot-to-Production Playbook: Stepwise adoption templates for moving from single-rack pilots to row- and room-level liquid cooling mosaics, with staged capital outlays and operational checkpoints.
- Vendor Negotiation Guides: Benchmarked service windows, warranty terms and spare-part policies distilled from supplier interviews and primary deployments.
- Integration Checklists: Controls interoperability, telemetry expectations and cybersecurity hardening for CDU control systems and BMS/EMS integration.
- Scenario-Based Risk Matrices: Energy-price sensitivity, elevated-water-performance scenarios and maintenance staffing models that reveal the levers with the largest impact on cost of operations.
Next Steps — Where to Find the Full Intelligence
This release is a strategic preview intended to orient 2026 decisions and highlight the areas where immediate action yields disproportionate value. The full PW Consulting Rack-mounted Full Liquid CDU Market report contains the detailed regional and application splits, vendor line-item revenue forecasts, downloadable TCO spreadsheets, vendor scorecards and procurement templates reserved for report subscribers. These elements are intentionally withheld from this public summary to preserve the proprietary analytics and to enable clients to act on validated, decision-grade intelligence.
Contact PW Consulting or visit our report page to access the full dataset, schedule a private briefing, or engage our consultants for a customized vendor selection and pilot plan. In a market evolving as quickly as rack-mounted liquid CDUs, timely insight and disciplined execution will separate winners from laggards in 2026.
For detailed analysis of this topic, please visit the official page: Rack-mounted Full Liquid CDU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com