

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EV & Fuel Cell Vehicles Market to Reach USD 539B by 2032

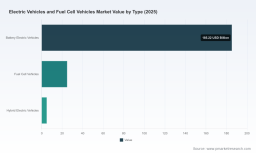
Electric Vehicles and Fuel Cell Vehicles Market — Strategic Insights for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concentrated briefing that translates our latest Electric Vehicles (EV) and Fuel Cell Vehicles (FCEV) Market study into immediate strategic value for executives planning 2026 moves. This piece follows a “trailer” approach: it surfaces the analytical rigor and directional findings you need to judge relevance, while preserving the granular segmented datasets and proprietary models that are accessible in the full report.
Electric Vehicles and Fuel Cell Vehicles Market
Executive snapshot — the market in context
Our analysis uses 2025 as the base year, reviews historical trends from 2020–2025, and models a 2026–2032 forecast horizon. The combined EV + FCEV market has transitioned from an emerging growth phase into a structural build-out: from roughly USD 163 billion in 2020 it expanded to about USD 215 billion by 2025, and our baseline forecast projects the market to surpass USD 500 billion by the early 2030s. The modeled compound annual growth rate (CAGR) for the forecast window is 14.06%, reflecting sustained demand, vehicle electrification momentum, and progressive technology cost curves.
Electric Vehicles and Fuel Cell Vehicles Market
These headline numbers frame several practical implications for corporate strategy in 2026: the market is large enough to justify scale investments but still diffuse enough that differentiated plays, partnerships and selective vertical integration can materially change competitive positions.
Electric Vehicles and Fuel Cell Vehicles Market
Why this research matters for 2026 decision-making
- Timing and investment calibration:
With double-digit structural growth baked into our baseline, firms must decide in 2026 whether to accelerate capital deployment (manufacturing, assembly lines, hydrogen fueling partnerships) or to stage investments to capture margin improvement from technology learning curves. The market trajectory supports aggressive scaling for players who can reduce unit costs quickly; it also rewards targeted pilots for those prioritizing route optimization and customer experience.
- Product and portfolio choices:
Automakers and fleets face trade-offs among battery-electric, fuel-cell, and hybrid platforms. Regulation-driven affordability initiatives and shifting consumer segments mean product roadmaps should be optimized not only on unit economics but also on lifecycle emissions compliance and total cost of ownership at the fleet level.
- Supply chain de-risking:
Raw material and component cost targets announced by governments and industry bodies — including fuel cell cost milestones and hydrogen production targets — create actionable procurement triggers. 2026 is the year to lock multi-year agreements, qualify secondary suppliers, and invest in recycling or substitution research to mitigate PGM exposure and upstream bottlenecks.
- Regulatory and market-access playbooks:
New CO2 standards, incentive rebalances and regional policy shifts have made market-entry conditional on well-orchestrated pricing and compliance strategies. Positioning product variants to meet affordability thresholds and navigating region-specific registration dynamics are critical tactical priorities for 2026 launches.
What the report delivers — practical, decision-ready outputs
- High-fidelity market sizing and 2026–2032 forecasts (including scenario and sensitivity analyses).
- Actionable go-to-market roadmaps for OEMs, Tier-1 suppliers, fleet operators, and infrastructure investors.
- Technology and cost trajectories (battery, fuel cell stacks, power electronics, hydrogen handling) with break-even timelines and unit-cost ladders.
- Supplier and partner heatmaps, including capability matrices to expedite procurement and JV screening.
- Regulatory and incentives tracker mapped to commercialization milestones and launch windows.
- Investment case templates, M&A screens, and financial models calibrated to risk-adjusted returns under alternate adoption curves.
- Field-tested pilot blueprints, procurement clauses, and go/no-go decision checkpoints for 0–24 month programs.
Note: the report includes full regional and application segmentations and the underlying datasets that support these deliverables; selective high-level figures and trends are presented here to demonstrate methodological rigor while preserving the proprietary segmentation tables for report subscribers.
Competitive landscape — companies to watch in 2026
- Toyota Motor Corporation (Toyota City, Japan)
Strategic posture: Toyota continues to play a foundational role in fuel-cell commercialization, leveraging product iterations and system-level engineering to expand applicability across passenger, commercial and heavy-duty segments. The company’s announcement of a third-generation fuel cell system slated for multi-region rollout underscores a push to improve durability and lower lifecycle costs. For competitors and partners, Toyota’s scale and system know-how make it both a potential collaborator and a benchmark for component reliability.
- Hyundai Motor Company (Seoul, South Korea)
Strategic posture: Hyundai’s broad product set — spanning passenger vehicles to hydrogen trucks and buses — positions it to capture diverse hydrogen demand pockets. The refresh cycles for fuel-cell models and commercial vehicle developments suggest a playbook focused on platform reuse and aftermarket services as levers to monetize hydrogen ecosystems.
- Honda Motor Co., Ltd. (Tokyo, Japan)
Strategic posture: Honda’s move to produce plug-in fuel cell variants in the U.S. signals an emphasis on localized manufacturing and market-specific product adaptation. This highlights an operational theme for 2026: OEMs that marry regional production footprints with local policy engagement can accelerate market access while containing logistics costs.
- BMW AG (Munich, Germany)
Strategic posture: BMW’s planned series production of fuel-cell vehicles, leveraging collaborative technology pathways, reveals a risk-managed approach to hydrogen. By combining licensing/partnered technology with scaled manufacturing intent, BMW illustrates an approach suited to premium segments where value capture can justify higher early-cycle costs.
- Nippon Shokubai Co., Ltd. (Tokyo, Japan)
Strategic posture: Component and catalyst innovators are critical enablers of cost reduction. Advances in platinum-group-metal-free catalysts and related materials science are a lever for industrial players to outflank raw-material constraints and to reduce stack costs — an outcome that materially affects heavy-duty total cost equations.
Complementing these OEM and supplier dynamics, product expansions from specialist suppliers (hydrogen recirculation, blowers, system integrators) are sharpening the ecosystem, creating new supplier niches and partnership options. The market concentration metrics indicate a relatively unconsolidated landscape, providing opportunities for agile entrants and focused consolidations.
Industry dynamics and critical external signals
- Policy acceleration: Tighter CO2 standards and region-level mandates are reshaping pricing and portfolio decisions; affordability-driven product introductions are increasingly important.
- Adoption scale: Global electric car sales hit record volumes in 2025, reinforcing electrification as mainstream; this scale validates network and after-sales investments.
- Cost targets: Public-sector technology targets for fuel cell stack costs and hydrogen production create clear commercial inflection points — hitting those targets materially improves heavy-duty and long-haul business cases.
- Localized friction points: Early signs of registration slowdowns in some FCEV registries highlight the need to pair vehicle launches with refueling infrastructure and customer value propositions.
Scenario planning — triggers that change the game
- Base case: Realization of the modeled CAGR and infrastructural rollouts in line with public targets; gradual cost declines enable broadening commercial adoption.
- Upside case: Faster-than-expected hydrogen production cost reductions and accelerated fuel-cell cost improvements unlock rapid heavy-duty electrification and industrial-scale fleet conversions.
- Downside case: Raw-material shocks, slower infrastructure scaling, or policy reversals compress adoption rates and push ROI timelines beyond early investors’ thresholds.
Concrete 2026 actions — prioritized
- Immediate (0–12 months):
Secure supply hedges for key materials, finalize pilots with targeted fleet partners, and lock conditional offtake or offtake-linked financing for infrastructure projects. Use modular procurement templates to speed RFP cycles while retaining flexibility for design evolution.
- Near-term (12–36 months):
Scale production in regions where regulatory and cost conditions align, negotiate technology partnerships for stack and system integration, and build bundled service offerings (vehicle + refueling + telematics) to improve payback for fleet customers.
- Strategic (36+ months):
Pursue consolidation in targeted supplier segments, vertically integrate critical modules if warranted by scale economics, and consider cross-sector alliances to accelerate hydrogen supply and amortize infrastructure investments.
Final word — using this research in 2026
The 2026 strategic window is defined by a large and fast-growing total market, significant technology milestones within reach, and uneven but accelerating infrastructure development. PW Consulting’s EV & FCEV Market study equips decision-makers with the scenario-based forecasts, cost curves, supplier maps and executable playbooks needed to convert market opportunity into competitive advantage. If your 2026 decisions involve capacity commitments, product launches, M&A, or infrastructure investments, the full report will provide the segmented forecasts, model inputs and executable templates to move from intent to impact.
To access the complete datasets, regional and application breakdowns, and the operational toolkits referenced above, please consult the PW Consulting EV & FCEV Market report page or contact our advisory team to arrange a briefing and licensing of the full analytical package.
For detailed analysis of this topic, please visit the official page: Electric Vehicles and Fuel Cell Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com