

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Acoustic Saxophone Market to Reach USD 344.8M by 2032 at 5.8% CAGR

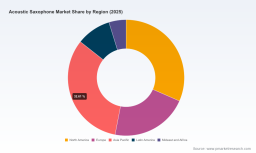
Acoustic Saxophone Market 2026: Strategic Imperatives for Industry Leaders
Executive snapshot
As PW Consulting’s lead industry analyst, this introduction frames the strategic value of our Acoustic Saxophone Market study for corporate decision-making in 2026. The market has shown resilient expansion through the recent cycle — rising from USD 163.15 Million in 2020 to USD 215.0 Million in our base year (2025) — and is projected to continue on an upward trajectory, reaching approximately USD 344.8 Million by 2032. Our forecast period (2026–2032) models a compound annual growth rate (CAGR) of 5.8% (USD, revenue unit: Million). These macro dynamics create a window of opportunity for product innovation, channel optimization, and strategic consolidation, but they also mask acute operational risks that require active mitigation.
Acoustic Saxophone Market
Why this study matters for decisions in 2026
-
Timing: 2026 is a pivot year. Demand signals (new product uptake, sustained consumer interest in performance-grade instruments, and growing amateur participation) intersect with supply-side shocks and regulatory shifts. Executives who align portfolio decisions with the quantitative scenarios in this report will be better positioned to capture premium segments and protect margins.
Acoustic Saxophone Market -
Clarity on scale and slope: The market’s scale in 2025 and the trajectory to 2032 provide the necessary context to evaluate R&D programs, capacity investments, and channel expansion initiatives. Treat the reported CAGR as a directional planning baseline; our study overlays it with scenario-specific demand elasticity and product lifecycle assumptions to support capex and go-to-market timing choices.
Acoustic Saxophone Market -
Competitive posture: Market concentration is meaningful — the top three players account for a majority share (CR3 ~55%), and the top five control roughly four-fifths of the market (CR5 ~80%). These metrics underscore a marketplace where scale economies, brand heritage, and distribution depth materially affect pricing power and entry barriers.
Market dynamics shaping strategic options
The acoustic saxophone market in 2026 is being reshaped by four linked forces: cost inflation in raw materials, production footprint reconfiguration, product innovation driving premium demand, and evolving go-to-market models.
-
Input-cost pressure and supply disruption: Brass raw-material costs jumped materially (industry data shows a 27% increase in 2023), a shock that reverberated through manufacturing margins and logistics. That spike contributed to delivery delays — in some regions, delays impacted over 7% of planned shipments — and forced manufacturers to reassess inventory buffers, hedging strategies and supplier diversification.
-
Manufacturing geography and regulatory impact: Confirmed facility closures and relocations are changing competitive calculus. Recent regulatory filings show at least one major U.S. manufacturer moving operations offshore, while others preserve European artisanal capacity for premium lines. These structural moves create trade-offs between labor cost, lead time, and "made-in" brand equity that firms must quantify when deciding localization vs. centralization.
-
Product-led differentiation: 2026 product activity demonstrates the market's bifurcation. Leading manufacturers launched new professional and ergonomic lines early in the year; in short order, some introductions achieved material unit velocity (e.g., an advanced alto model surpassed notable unit sales within months, and a newly designed ergonomic student/intermediate line exceeded ten-thousand-unit thresholds by year-end). This validates premiumization strategies, but it also signals that product quality, playability, and resonance innovation remain primary purchase drivers.
-
Channel and aftermarket evolution: Retail and education channels are evolving. Bundled offers for learning & training, extended warranties, and bespoke customization services are increasing lifetime value. Digital direct-to-consumer channels and enhanced service models are rapidly becoming differentiators, particularly for mid- and high-end customers seeking customization and fast service.
Competitive landscape — what the leading firms reveal
The market is anchored by a mix of multinational incumbents and specialized craftsmen. Profiles of core competitors illustrate three competing strategic logics:
-
Scale and breadth (global OEMs): Established manufacturers with broad portfolios leverage distribution reach and multi-brand strategies to serve student-to-professional segments. Their priorities in 2026 are cost mitigation, channel optimization, and incremental product upgrades to protect volume.
-
Specialist premium manufacturers: Artisan and boutique makers emphasize tonal heritage, ergonomics, and finish options. They preserve margin through craftsmanship and limited runs, benefiting from demand for bespoke and stage-ready instruments.
-
Value-driven mass-market producers: Firms focusing on durability and price performance target education and amateur segments, investing in robust designs and ergonomic improvements to reduce churn and increase unit velocity in institutional channels.
These archetypes are embodied by well-known companies across the industry: multinational instrument houses that combine institutional OEM scale with student and professional lines; boutique craftspeople who drive high-margin customization; and competitive Taiwanese and Japanese manufacturers who balance cost, quality and distribution. The market concentration noted earlier amplifies the advantage of incumbency but also surfaces attractive acquisition targets among smaller players whose manufacturing techniques, IP or niche brand equity complement larger portfolios.
What the report delivers (practical contents)
Our full PW Consulting study equips commercial, product and corporate strategy teams with tools and templates to act in 2026. Highlights include:
-
Market sizing & forecasts: Modeled to 2032 with scenario overlays (base, upside, downside) and sensitivity to raw-material and labor-price shocks.
-
Demand-driver analysis: Consumer segmentation, purchase triggers across professional, education and amateur cohorts, and unit economics for each cohort.
-
Channel & pricing playbook: Margin maps by channel, distribution recommendations, recommended retail pricing bands for staged product rollouts, and cross-sell/up-sell strategies for accessories and services.
-
Manufacturing & sourcing stress tests: Cost-pass-through models, supplier risk matrices, and relocation-impact simulations that quantify trade-offs between labor cost savings and brand/lead-time penalties.
-
Competitive heat maps: Strategic benchmarking against the leading manufacturers (including strengths in scale, product craftsmanship, innovation cadence, and channel penetration) and an M&A target shortlist defined by strategic fit and integration risk.
-
Operational playbooks: Tactical guidance for inventory hedging, material procurement strategies, localized production pilots, and aftermarket service programs to protect revenue during supply shocks.
-
Risk register & regulatory implications: Focused sections on labor and trade policy shifts, including implications of recent facility relocations and evidence of maintained artisanal production sites in Europe for premium lines.
Strategic recommendations for 2026
-
Hedge and diversify brass supply: Implement multi-sourcing contracts, explore alloy substitutes where acoustically acceptable, and contractually secure lead times for critical components to avoid delivery slippage across priority markets.
-
Dual-track manufacturing strategy: Preserve artisanal lines for brand-sensitive professional offerings while selectively outsourcing high-volume student models. Quantify the premium consumers attach to provenance and use it to defend margins on premium SKUs.
-
Accelerate product-led premiumization: Invest in ergonomic and acoustic R&D that can be monetized through limited-run premium finishes and customization options, informed by rapid-launch learnings from early-2026 introductions.
-
Rebalance channel mix toward direct engagement: Build or expand DTC channels and aftermarket service capabilities to increase lifetime value and improve customer learning pathways (student → intermediate → professional).
-
Pursue targeted inorganic moves: Use the current consolidation dynamics to acquire specialist makers or component technologies that augment IP, shorten time-to-market for premium features, or close distribution gaps.
Conclusion — the strategic payoff
Our analysis shows that the acoustic saxophone market’s growth to 2032 is substantial enough to justify measured investment, but the pathway to margin expansion is conditional on how companies manage supply risk, product differentiation and channel economics. With a concentrated competitive structure and confirmed cost shocks, 2026 is a decisive year for firms to reposition: those that combine disciplined sourcing, selective localization, and product-led premiumization will expand share and margin; those that delay will face margin compression or distribution erosion.
The full PW Consulting Acoustic Saxophone Market report contains the detailed segment-level breakouts, channel maps, company-by-company benchmarking and executable playbooks required to convert these insights into concrete 2026 action plans. For practitioners seeking the underlying data and strategic templates, the complete intelligence is available on our report page.
For detailed analysis of this topic, please visit the official page: Acoustic Saxophone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com