

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Indirect Auto Finance Market Poised to Reach USD 474.0 Billion by 2032

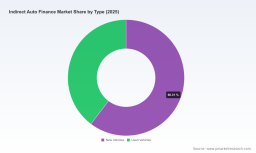
Indirect Auto Finance Market — 2026 Strategic Outlook
PW Consulting’s new Indirect Auto Finance Market report provides a focused, decision-grade view for executives preparing 2026 strategies. Built on rigorous historical analysis and forward-looking scenario modeling, the study distills the macro trajectory, competitive dynamics, regulatory inflection points, and practical playbooks that lenders, OEM captives, dealers, and fintech partners will need to navigate accelerating complexity in dealer-originated consumer vehicle finance.
Public Safety Dispatch Consoles Market
Executive snapshot
The indirect auto finance ecosystem has entered a renewed growth phase after a period of volatility. Our model shows the market expanding from approximately USD 168.45 Billion in 2020 to roughly USD 298.5 Billion in 2025, with a base-year profile calibrated to 2025 financials. Looking forward, the market is projected to compound at an annualized rate of 6.85% across the 2026–2032 forecast window, reaching an estimated USD 474.0 Billion by 2032 under the central scenario. These headline metrics frame the strategic choices facing market participants in 2026: scale, capital sourcing, credit appetite, and digital distribution will determine winners and laggards.
Avocado Butter Market
Why this report matters for 2026 decision cycles
-
Timing: Boards and C-suite teams setting budgets and product roadmaps for 2026 must align capital plans with an industry that is both growing and re-pricing risk. Our report translates macro growth into actionable pathways for origination, securitization, and capital deployment.
Luxury Home Audio Market -
Regulatory shift-readiness: With material regulatory activity affecting how nonbank originators are defined and supervised, institutions must be ready to redesign compliance and reporting functions. The report offers scenario-driven impact assessments to prioritize one- and two-year remediation steps.
-
Dealer-channel economics: Since the vast majority of auto loans continue to be originated via dealer channels, optimizing dealer-lender bilateral economics—without sacrificing credit performance—will be a core lever. The report supplies a modular toolkit for reconfiguring dealer incentives, repricing mechanisms, and inventory funding strategies.
-
Competitive positioning: A rising share of dealer-originated volume is shifting toward banks and non-captive lenders. The report maps competitive vectors for captives, banks, and independents and provides playbooks to defend or accelerate market share.
What’s inside: practical, implementable content
This is not a brochure—our research is purpose-built to put plans into motion. Key deliverables include:
-
Validated market sizing and near-term forecasts (2026–2032) with sensitivity cases for demand shocks, rate movements, and affordability stress.
-
Scenario playbooks: three calibrated scenarios (central, downside, upside) with quantified impacts on originations, loss rates, and funding needs to inform capital planning and stress testing.
-
Operational playbooks for dealer-originated flows: step-by-step approaches for improving conversion, reducing charge-offs, and shortening time-to-fund while maintaining compliance.
-
Regulatory impact matrix and remediation roadmap: prioritized actions to respond to changing definitions of “larger participants,” disclosure expectations, and fair lending interpretations.
-
Product and pricing playbooks: modular templates for rate-card design, risk-based pricing governance, and dealer compensation structures aligned with portfolio objectives.
-
Capital and funding strategies: decision frameworks for whole-loan sales, securitization tranches, warehouse lines, and bilateral funding to optimize cost of capital under different originations mixes.
-
Technology & data roadmaps: recommended investments in decisioning engines, dealer portals, and performance analytics to compress loss cycles and uplift throughput.
-
Competitive intelligence appendices: curated profiles and strategic positioning assessments of principal active players in the indirect channel.
Competitive landscape — who matters and why
The indirect auto finance space is meaningfully concentrated, but still offers room for disruption. The top three providers account for a substantial share of market volume, and the top five consolidate over half of all activity—an important contextual fact when setting share targets or evaluating M&A. Market concentration creates advantages in scale for distribution, capital access, and dealer reach, while also leaving white space for specialized providers and digital challengers to capture niche or underserved segments.
We profile the strategic orientations of core market participants to help clients benchmark positioning:
-
Ally Financial — a leading non-captive lender that leverages broad dealer networks and depth in retail installment and floorplan financing. Their scale in dealer relationships and treasury functions provides a template for integrated dealer financing strategies.
-
Capital One Auto Finance — bank-affiliated, emphasizing competitive rates and digital approval experiences. Their model underscores how digital conditional-approval frameworks shorten the buyer journey and increase cross-sell.
-
Toyota Financial Services, GM Financial, Ford Motor Credit, American Honda Finance — captive finance arms that use brand-aligned product bundles, lease options, and loyalty-focused underwriting to preserve OEM sales economics. Captives remain pivotal for OEM go-to-market control and price elasticity management.
-
Chase Auto Finance and Wells Fargo Auto — large-bank lender profiles that combine dealer distribution with balance-sheet scale and sophisticated funding programs.
-
Westlake Financial Services — an independent specialist that demonstrates how underwriting specialization and dealer-focused servicing can profitably address higher-risk segments underserved by prime lenders.
Recent market intelligence points to structural movement: independent analyses published in early 2026 indicate banks and non-captive lenders are gaining share in dealer-originated volume, and dealer-related finance debt has shown double-digit year-over-year growth in certain channels. For strategy teams, this underlines two imperatives—first, sharpen the distributor value proposition; second, revisit capital and risk-allocation frameworks to monetize growing dealer pipelines.
Regulation and macro dynamics that will shape 2026 outcomes
The policy and macro backdrop is rapidly evolving and must be integral to any 2026 plan. Highlights from our Dynamics analysis include:
-
Supervisory redefinition risk: Regulatory attention on thresholds for “larger nonbank auto finance participants” creates potential new compliance and reporting obligations for firms crossing originations thresholds. This is already influencing originator behavior when sizing dealer relationships and balance-sheet deployments.
-
Fair-lending interpretation changes: A notable policy development clarified the scope of disparate impact claims under ECOA in late 2025, altering litigation and supervision risk profiles for indirect channels where dealer markup and discretion are present.
-
Demand sensitivity: Market intelligence suggests a modest near-term moderation in originations due to affordability pressures—some forecasts point to a small downtick in 2026 origination volumes. Our scenarios quantify the impact on revenue, loss ratios, and capital needs so leaders can stress-test budgets.
-
Dealer origination dominance: Independent research continues to validate that the majority of auto loans are dealer-originated and subsequently placed with lenders, reinforcing the strategic importance of dealer experience management and reseller economics.
Strategic imperatives for market participants in 2026
Based on our integrated market, competitive, and regulatory analysis, PW Consulting recommends four priority moves for executives setting 2026 agendas:
-
Recalibrate origination footprint: Actively manage dealer relationships and channel incentives to optimize mix and preserve access to high-conversion partners. Consider selective expansion into underserved dealer cohorts where pricing power can be sustained.
-
De-risk through capital architecture: Diversify funding sources and prepare contingency securitization pathways to insulate originations from short-term liquidity stress. Capital planning should be scenario-driven and integrated with product/design decisions.
-
Hardwire regulatory readiness: Run targeted gap analyses against likely supervisory thresholds and fair-lending controls; prioritize remediations that reduce operational friction without materially sacrificing revenue.
-
Accelerate digital dealer integration: Invest in decisioning engines, real-time funding, and dealer UX to compress cycle times, reduce fallout, and limit dealer discretion in markup—thereby improving credit outcomes and reducing supervisory attention.
How this report is structured to support execution
Every chapter of the report is aligned to execution. Market-sizing and forecasting modules feed into the capital and stress-test appendices; competitive landscaping includes actionable diagnostics and countermeasures; regulatory assessments are prioritized by likelihood and business impact, with concrete implementation timelines. The result is a concise, prioritized roadmap for 90-, 180-, and 365-day actions that managers can fold into operating plans.
Next steps
For teams preparing 2026 budgets, product launches, or dealer-partner strategies, this report functions as both an early-warning system and an operations manual. PW Consulting’s analysts are available to run customized slices of the model—tailoring scenarios to specific origination mixes, funding structures, and regulatory exposures—so firms can convert strategic clarity into measurable actions.
To access the full set of forecasts, scenario outputs, and implementation playbooks, request the complete Indirect Auto Finance Market report on our website. The executive summary in this release previews the strategic logic and highlights the high-level forecasts; the full report contains the granular decision-support models and step-by-step playbooks necessary to operationalize a winning 2026 strategy.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com