

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: EV Charger Market Hits $25.55B in 2025, Poised for 18.12% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Electric Vehicle Charger Market: Strategic Intelligence for 2026 Decision-Makers
The global transition toward electrified transportation has moved beyond early adoption curves and entered a phase of structural scaling. For executives, investors, and strategic planners, 2026 represents a critical inflection point where infrastructure deployment, regulatory compliance, and competitive positioning converge. Our latest Electric Vehicle Charger (EVC) Market research delivers a disciplined, data-grounded assessment of this evolving landscape, designed to inform capital allocation, product roadmaps, and market entry strategies throughout the forecast horizon.
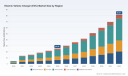
The market has demonstrated remarkable momentum over the past half-decade. Revenue expanded from approximately 4.82 billion USD in 2020 to 25.55 billion USD in 2025, reflecting a compound trajectory that underscores both consumer adoption and enterprise fleet transition. Looking ahead, the forecast period extending to 2032 projects sustained expansion, with the market anticipated to reach 81.57 billion USD by the terminal year. This growth is anchored by a forecast CAGR of 18.12 percent, a figure that signals durable demand rather than speculative hype. Navigating this environment requires more than top-line visibility; it demands a granular understanding of technology shifts, regional deployment patterns, competitive maneuvers, and the regulatory frameworks that will shape operational feasibility.
Market Architecture and Forecast Trajectory
The EVC market is no longer a monolithic category. It has differentiated into distinct technology tiers, application environments, and geographic corridors, each with its own adoption drivers, margin structures, and deployment constraints. Our research maps these layers systematically, allowing stakeholders to evaluate where value is created, where bottlenecks persist, and how capital should be weighted across the stack.
Technology Segmentation and Power Architecture
Charging infrastructure has bifurcated into three principal power categories, each serving different use cases and customer expectations. Level 1 chargers continue to serve low-intensity residential and light commercial needs, while Level 2 deployments form the backbone of workplace, multi-family, and retail environments. Level 3 DC fast charging represents the highest-growth and highest-complexity segment, targeting public corridors, fleet depots, and heavy-duty applications where downtime minimization is paramount. The revenue mix across these categories reflects a market that is simultaneously maturing in baseline residential and commercial installations while accelerating toward high-power public and fleet-facing solutions.
Application Environments and Deployment Logic
Demand is distributed across residential, commercial, and public application environments, but the strategic implications differ sharply by segment. Residential installations are shaped by consumer incentives, home energy integration, and installation logistics. Commercial deployments are increasingly driven by fleet electrification, workplace charging programs, and property-value considerations for retail and hospitality venues. Public infrastructure remains the most policy-sensitive segment, dependent on corridor planning, utility coordination, grid capacity, and municipal permitting regimes. Understanding how these application environments interact with technology tiers is essential for companies deciding whether to prioritize volume-oriented residential products, commercial fleet solutions, or high-power public hub architectures.
Geographic Distribution and Regional Priorities
Revenue activity spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, but the strategic weight of each region varies according to policy intensity, vehicle sales mix, utility readiness, and supply chain positioning. Some markets are advancing through coordinated public investment and corridor planning, while others are pulling forward through private fleet commitments and residential adoption. The research breaks down regional dynamics without oversimplifying them, enabling stakeholders to assess where near-term revenue is most accessible and where long-term positioning requires patience, local partnerships, or regulatory engagement.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a concentrated but dynamically shifting field. The market exhibits a CR3 of 28.5 percent and a CR5 of 35.2 percent, indicating that while leading players command meaningful share, the remaining landscape is open to specialized entrants, regional specialists, and technology-first innovators. This structure rewards companies that can combine hardware performance, software integration, service reliability, and deployment speed.
XCharge: High-Power DC and Grid-Integrated Systems
XCharge, headquartered in Kyle, Texas, has built its identity around high-power DC fast charging solutions, including 400 kW C7 chargers and GridLink battery-integrated systems designed for grid support and public fleet applications. The company's recent expansion underscores a commitment to scaling production capacity for advanced high-power hardware. In April 2026, XCharge North America opened a new 3,000 sqm assembly plant in Valencia, Spain, focused on C7 400 kW chargers and GridLink solutions. This move signals a strategic emphasis on manufacturing flexibility, regional deployment capability, and the integration of storage-coupled charging architecture that can mitigate grid constraints at high-demand sites.
Kempower: Modular DC Fast Charging and Ecosystem Partnerships
Kempower, based in Lahti, Finland, manufactures modular DC fast chargers, including the Station Charger platform capable of up to 400 kW and Power Module systems tailored for public hubs, fleets, and heavy-duty vehicles. The company's modular philosophy enables scalable deployment and operational flexibility, which is particularly valuable for operators managing variable demand profiles across sites. In January 2026, Kempower announced a global partnership with DC fast charger OEM Tritium to simplify EV charger payment enablement. This collaboration highlights a broader industry shift toward reducing friction in user experience and transaction processing, areas that increasingly differentiate operators in public and fleet segments.
Enphase Energy: Bidirectional Charging and Energy Integration
Enphase Energy, headquartered in California, produces AC and DC bidirectional EV chargers through its IQ Bidirectional platform, enabling vehicle-to-home and vehicle-to-grid integration with compatible solar systems. As energy management becomes inseparable from charging infrastructure, bidirectional capability positions Enphase at the intersection of EV adoption and distributed energy resources. In February 2026, Enphase Energy announced that it would begin volume manufacturing of the IQ Bidirectional EV Charger platform in Q4 2026 following product demonstrations. This timeline reflects a deliberate transition from demonstration to scaled production, aligning with growing interest in home energy resilience, solar coupling, and grid services enabled by parked electric vehicles.
Regulatory Dynamics and Operational Imperatives
Regulatory frameworks are no longer peripheral considerations; they are becoming central to site selection, product design, service commitments, and financial modeling. Several recent developments illustrate how policy is reshaping operational expectations across the EVC value chain.
In April 2026, the California Energy Commission adopted Electric Vehicle Charging Data and Reliability Standards, effective April 2026. These standards require semi-annual reporting of charger inventory and uptime for entities operating EV chargers, with exclusions for single-family homes and multi-family homes with four or fewer units. This creates a formal accountability layer for commercial and public operators, elevating uptime and transparency as measurable performance metrics rather than aspirational goals.
Related reliability expectations were reinforced in October 2025, when the California Energy Commission established that entities operating EV chargers installed on or after January 1, 2024 must maintain a minimum annual average uptime rate of 97 percent for the first six years after installation. For operators and OEMs, this standard changes the economics of maintenance, remote monitoring, and component durability. It also raises the stakes for companies that can demonstrably deliver higher reliability through modular architecture, predictive service, and faster fault resolution.
Ev Charging Card Market
On the supply chain and manufacturing side, the proposed modification of Buy America requirements for EV charger projects obligated on or after October 1, 2025 mandates that all manufactured products must be manufactured in the United States. Published as a Federal Register Notice of Proposed Modification in February 2026, this development has direct implications for sourcing strategy, domestic production capacity, and the cost structure of projects seeking federal support. Companies with flexible manufacturing footprints or domestic assembly capabilities may gain a distinct advantage in qualifying for funded deployments.
Incentives continue to shape end-user economics as well. The Alternative Fuel Vehicle Refueling Property Credit allows up to 1,000 USD tax credit per charging port for eligible equipment installed at principal residences, according to IRS guidance issued in March 2026. This credit supports residential adoption and can influence the value proposition of home charging products, particularly when bundled with energy management features or installation services.
Electric Vehicle Charger (EVC) Market
Report Scope and Decision-Ready Content
Our Electric Vehicle Charger Market research is structured to translate complex market signals into actionable intelligence. Rather than offering a static snapshot, the report is designed as a working reference for teams that need to evaluate opportunities, manage risk, and prioritize initiatives across the 2026 to 2032 horizon.
- Historical and forecast revenue analysis grounded in a 2025 base year, with backward visibility from 2020 to 2025 and forward projections through 2032, enabling trend validation and scenario planning.
- Technology-level assessment across Level 1, Level 2, and Level 3 charger categories, with attention to power ratings, deployment contexts, and the operational trade-offs that influence product strategy.
- Application-level analysis covering residential, commercial, and public segments, helping stakeholders align product features, pricing, and go-to-market models with the needs of each environment.
- Regional evaluation across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, supporting market prioritization, partnership screening, and localized expansion planning.
- Competitive profiling of leading participants, including XCharge, Kempower, and Enphase Energy, with coverage of product architectures, recent operational developments, and strategic moves that signal where the market is heading.
- Regulatory and policy tracking that connects standards, incentives, and procurement requirements to practical implications for deployment feasibility, compliance burden, and cost structure.
- Concentration and share dynamics that contextualize the competitive field, helping companies gauge where differentiation is most needed and where scale or niche positioning may be more effective.
The research is built for cross-functional use. Strategy teams can use it to frame market entry and expansion decisions. Product and engineering leaders can use it to triangulate technology investment against demand signals. Sales and business development teams can use it to identify high-potential segments and align messaging with the operational realities of each application environment. Finance and investor relations teams can use it to ground revenue expectations in a transparent trajectory rather than anecdotal momentum.
Strategic Implications for 2026 Planning
The EVC market in 2026 is defined by three interlocking realities. First, demand is broad enough to support multiple business models, but not uniform enough to reward undifferentiated playbooks. Residential, commercial, and public segments each require distinct installation logic, customer engagement, and service commitments. Second, technology choice is increasingly a strategic variable rather than a specification detail. The balance between Level 1, Level 2, and Level 3 deployments shapes everything from site selection and grid interaction to user experience and maintenance economics. Third, regulatory and incentive environments are maturing in ways that reward reliability, transparency, and compliant manufacturing footprints.
Companies that treat uptime as a core product attribute, not a service afterthought, will be better positioned for markets where reliability standards are becoming explicit. Organizations that can align hardware, software, and payment or energy-integration capabilities will have an easier path to reducing friction for end users and operators alike. Firms with manufacturing and supply chain flexibility will be more resilient to procurement rules and regional content requirements that are beginning to influence project qualification. And stakeholders that understand the interplay between charging infrastructure and distributed energy resources will be better prepared for a market in which vehicles, homes, solar systems, and grids increasingly operate as a connected system rather than separate silos.
The trajectory from 25.55 billion USD in 2025 toward 81.57 billion USD by 2032 is not merely a growth statistic. It is a signal that the market is scaling into a strategically complex environment where execution quality, regulatory literacy, and segment-specific positioning determine who captures durable advantage. This research is designed to help decision-makers move beyond surface-level optimism and into the operational and competitive details that actually shape outcomes.
Why This Research Matters Now
Market momentum alone does not create strategy. The value of this report lies in its ability to convert a fast-moving landscape into a structured basis for choice. By combining historical context, forecast visibility, technology and application segmentation, regional dynamics, competitive profiling, and regulatory tracking, the research gives stakeholders a shared framework for discussing where to invest, what to build, and how to compete.
For organizations planning 2026 initiatives, the report provides the kind of decision intelligence that reduces uncertainty without oversimplifying it. It highlights where demand is most concentrated, where reliability and compliance are becoming decisive, and where leading companies are placing their bets through product launches, manufacturing expansion, and partnership activity. It also preserves enough analytical depth to support internal debate, while remaining focused on the practical questions that executives and project teams face day to day.
The Electric Vehicle Charger market is entering a phase in which the winners will be those who can integrate technology, operations, policy, and customer experience into a coherent strategy. Our research is built to support that effort, offering a clear view of the market's current architecture and the forward dynamics that will shape the next several years.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Charger (EVC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sound Level Meters Market Hits $1.3B in 2025, Projects 5.85% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the 2026 Decision-Maker: Unlocking Value in the Sound Level Meters Market
As global industrialization accelerates and environmental compliance frameworks tighten, the acoustic instrumentation sector stands at a critical inflection point. For executives navigating capital allocation, product development, and regulatory readiness in 2026, understanding the trajectory of the Sound Level Meters Market is no longer optional—it is a strategic imperative. PW Consulting's latest comprehensive study provides a rigorous, forward-looking examination of this evolving landscape, equipping leadership teams with the analytical clarity required to turn market complexity into competitive advantage.
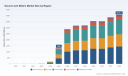
The sector has undergone a pronounced structural transformation over the past half-decade. Where the market landscape once revolved around modest valuation bands, recent historical cycles have demonstrated an aggressive expansion phase, culminating in a substantial revaluation of the addressable opportunity. Building on this momentum, our baseline projections map a sustained growth trajectory through the end of the decade, with an anticipated compound annual growth rate of 5.85 percent across the forecast horizon. In absolute terms, the market is on track to more than double its near-term valuation before plateauing into a mature, high-efficiency operating environment by the early 2030s. For strategists, this curve is not merely a numerical forecast; it is a timing mechanism for capacity planning, supply chain positioning, and partnership strategy.
Decoding the Forecast: Why Macro Scale and CAGR Governance Matter Now
Base-year anchors and forward-looking growth bands are the scaffolding upon which 2026 operating budgets are built. By anchoring analysis in a recent baseline year and extending visibility through 2032, this study enables stakeholders to model demand elasticity, price realization, and inventory turnover with far greater precision. The sheer velocity of recent market expansion has compressed traditional planning cycles. Organizations that continue to rely on linear extrapolation risk either overextending into saturated segments or underinvesting in high-velocity niches. Our forecast architecture corrects for this by mapping inflection points, saturation thresholds, and sustained growth corridors that differentiate cyclical noise from structural opportunity.
For manufacturing leaders, the implication is clear: capacity investment decisions made in early 2026 will face evaluation against a market that matures rapidly. For technology integrators and service providers, the window to embed next-generation acoustic measurement capabilities into broader industrial ecosystems is narrowing. A disciplined assessment of growth velocity, rather than headline size alone, determines which players capture margin expansion and which are relegated to commoditized competition. Every percentage point of CAGR translates into tangible shifts in procurement timing, R&D prioritization, and channel strategy, and this report translates those macro curves into decision-ready frameworks.
Digital Noise Meter Decibel Meter Market
Regulatory Architecture as a Strategic Catalyst
Noise monitoring and occupational safety compliance are governed by an interlocking web of technical standards and enforcement mandates. The IEC 61672-1 framework continues to anchor measurement accuracy expectations, with defined stability parameters that extend well into the next decade and require ongoing calibration and verification for workplace and environmental monitoring. On the occupational front, recognized safety authorities mandate that compliance-grade instruments align with or exceed established Type specifications, ensuring that workplace noise exposure assessments remain defensible under regulatory scrutiny.
Sound Level Meters Market
These requirements are not static. The reaffirmed alignment between major measurement standards and international specifications signals an industry moving toward greater harmonization rather than fragmentation. Simultaneously, the integration of validated measurement applications into occupational hearing-loss prevention programs has expanded the definition of what constitutes a compliant monitoring solution. Organizations that view regulatory evolution as a compliance checklist miss the strategic dimension: standardization lowers entry barriers for adjacent applications, accelerates procurement cycles for large enterprises, and rewards manufacturers that build verifiable accuracy and traceability into their product architecture from the outset. Compliance is increasingly becoming a competitive moat rather than a cost center.
Segmentation Dynamics: Precision vs. Ordinary, Vertical Demand, and Geographic Gravity
One of the most actionable layers of this market lies in its segmentation architecture. The instrument landscape is fundamentally divided between precision-grade professional platforms and ordinary-grade measurement tools, each serving distinct performance requirements, price realities, and end-user expectations. Precision instruments command premium positioning, reflecting the specialized engineering, calibration infrastructure, and labor-intensive build and verification processes required to deliver high-fidelity acoustic measurements. This price stratification is not accidental; it reflects the technical rigor demanded by certified testing environments and regulated compliance workflows, where instrument reliability is non-negotiable.
On the demand side, deployment patterns reveal where measurement intensity is concentrated. Industrial facilities and enterprise operations represent a dominant consumption pillar, driven by continuous environmental monitoring, machinery diagnostics, and workplace safety programs. Environmental protection applications form a robust secondary cluster, reflecting government mandates, municipal monitoring initiatives, and community noise management projects. Transportation ecosystems, research and development laboratories, and a broader set of specialized use cases complete the demand mosaic, each with distinct procurement rhythms, technical specifications, and integration requirements.
Geographic distribution further enriches the segmentation picture. Leadership in market share is distributed across multiple regions, reflecting the interplay of advanced industrial infrastructure, tightening municipal regulations, and expanding manufacturing footprints. Rather than betting on a single regional narrative, the market rewards firms that calibrate their regional strategy to local compliance intensity, channel maturity, and industrial density. The strategic takeaway is that geographic presence is most valuable when synchronized with vertical specialization and application-specific feature sets. By understanding which regions and which verticals are converging, companies can prioritize channel partnerships, localized service networks, and application-specific product configurations that maximize return on market entry.
Competitive Landscape: Specialists, Integrators, and the Battle for Differentiation
The competitive field is composed of established specialists, diversified measurement conglomerates, and agile entrants pursuing specific application niches. At the premium end, several organizations anchor their portfolios around professional-grade platforms designed for rigorous environmental and occupational monitoring. These offerings emphasize measurement fidelity, multi-channel analysis, and long-term durability, catering to users whose measurement outcomes carry regulatory and operational consequences. Complementary players extend the ecosystem through app-integrated Class instruments, wireless workplace assessment modules, and cloud-connected compliance platforms that bridge field measurement with enterprise data workflows.
Occupational safety-focused manufacturers have carved out a strong position by aligning instrument design with workplace exposure assessment, dosimetry integration, and field-ready ergonomics. Others differentiate through software-driven value: real-time data logging, remote reporting, and connectivity features that transform standalone instruments into nodes within broader environmental and safety management systems. In parallel, a cohort of industrial and environmental measurement providers targets broad-spectrum deployment, emphasizing versatility, ease of use, and cost-efficient operation across factories, municipal programs, and field research settings.
Recent product activity underscores how competition is evolving beyond hardware specifications alone. Wireless measurement modules, dedicated occupational health assessment tools, and analyzers with advanced signal-processing options have expanded the functional perimeter of the category. These developments reflect a broader industry shift: buyers are no longer purchasing an isolated instrument; they are selecting a measurement solution that must integrate with compliance workflows, reporting infrastructure, and operational decision loops. In this environment, differentiation is increasingly defined by ecosystem compatibility, validation documentation, and post-sale service reliability as much as by core measurement performance.
What the Study Delivers: From Strategic Mapping to Execution-Ready Intelligence
This market study is structured to support decision-making at multiple organizational levels. Rather than offering a static snapshot, it functions as an operational intelligence toolkit designed for cross-functional use. Executive leadership can leverage the overarching growth architecture to align capital deployment, M&A screening, and long-range planning with empirically grounded demand trajectories. Product and engineering teams will find detailed segmentation analysis useful for calibrating feature roadmaps, identifying performance gaps, and prioritizing precision versus accessibility trade-offs in next-generation designs.
Commercial and go-to-market teams benefit from rigorous competitive profiling that maps company positioning, product differentiation, and recent launch activity across the landscape. By examining how incumbents and challengers are expanding their functional portfolios—whether through wireless connectivity, occupational health specialization, advanced signal analysis, or cloud-enabled compliance features—the study illuminates where white space remains and where consolidation pressures are likely to intensify. Procurement and supply chain stakeholders can use the regional and application breakdowns to refine sourcing strategies, anticipate demand clustering, and align inventory planning with high-velocity deployment zones.
The research also embeds regulatory and standards-driven dynamics directly into its analytical framework. Because compliance requirements shape both instrument design and purchasing behavior, the study evaluates how evolving measurement specifications, calibration expectations, and occupational safety mandates influence competitive positioning and market access. This ensures that strategic conclusions are grounded not only in volume and revenue projections, but also in the enforceable realities that determine which solutions win in regulated procurement environments.
Translating 2026 Intelligence into Actionable Strategy
For organizations operating in or adjacent to the acoustic measurement sector, 2026 is a year of positioning. The market is large enough to reward scale, yet segmented enough to reward precision targeting. Growth rates signal opportunity; regulatory continuity signals stability; competitive intensity signals the need for sharper differentiation. The firms that will outperform are those that treat market intelligence as a dynamic input to product design, channel strategy, compliance readiness, and regional expansion, rather than as a retrospective record of where demand has been.
PW Consulting's full study goes beyond the directional themes outlined here. It provides the granular segmentation data, competitive benchmarking, regional breakdowns, application-level demand profiles, and forward-looking scenario analysis required to convert high-level market awareness into executed strategy. For leadership teams preparing investment committee presentations, product launch roadmaps, or market-entry assessments, the complete report delivers the depth and specificity needed to reduce uncertainty and accelerate decision cycles.
The Sound Level Meters Market is not simply expanding; it is reorganizing around precision, compliance, connectivity, and application specificity. The organizations that decode this reorganization first will define the next phase of competitive advantage. Access the full PW Consulting market study to secure the comprehensive intelligence your team needs to lead, not follow, in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Sound Level Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pallet Conveyor Market to Hit $2.36B by 2032, Driven by 5.2% CAGR and Logistic Demand
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Pallet Conveyor Market: Navigating the 2026–2032 Growth Arc
The global supply chain is undergoing a structural realignment. As organizations confront persistent labor constraints, escalating material costs, and tightening safety regulations, automated material handling has shifted from a tactical efficiency measure to a core strategic imperative. Pallet conveyor systems sit at the intersection of these forces, enabling warehouses, distribution centers, and industrial facilities to move unit loads with greater predictability, throughput, and operational resilience. This market intelligence briefing introduces PW Consulting's latest comprehensive study on the Pallet Conveyor Market, designed specifically to equip executive decision-makers, procurement leaders, and capital investment committees with the analytical clarity required for 2026 strategy formulation and beyond.
The Macro Trajectory: Baseline Data and Forward Visibility
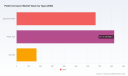
Market momentum is best understood through verified revenue baselines and a disciplined forecast horizon. Drawing on historical revenue data spanning 2020 through 2025, and extending a seven-year projection window to 2032, the analysis maps a market that has demonstrated consistent expansion after navigating near-term volatility. Evaluated in USD millions, the sector's revenue footprint has progressed from approximately 1,284.6 million in 2020 through a period of recalibration, before accelerating toward 1,588.1 million in 2024 and 1,655.2 million in 2025. The trajectory ahead points to continued scaling, with projected revenue reaching roughly 1,758.7 million in 2026 and advancing toward 2,360.2 million by 2032.
The compound annual growth rate anchoring this forecast stands at 5.2 percent, a figure that reflects measured but durable expansion rather than speculative overreach. For leadership teams evaluating multi-year facility roadmaps, this rate represents more than a top-line statistic. It signals a market environment in which capital deployment timing, vendor selection, and system architecture decisions will compound in importance over the forecast period. Sustained mid-single-digit growth rarely emerges from a single driver; instead, it consolidates demand across multiple operational pressures that we examine in the dynamics section below.
Why This Study Matters for 2026 Decision-Making
Annual strategic planning cycles increasingly require evidence that can withstand board-level scrutiny, procurement negotiations, and engineering validation. A market research deliverable in this category is not intended as a static reference document; it functions as an operational compass. The Pallet Conveyor Market study is structured to convert macro conditions into actionable intelligence across four decision-critical dimensions:
- Capital allocation timing. Understanding where revenue is accumulating, which system types are gaining share, and how regional deployment patterns are evolving helps leaders sequence capital requests, avoid premature or lag investments, and align capital budgets with realistic demand horizons.
- Vendor and integrator evaluation. A competitive landscape shaped by specialized manufacturers and globally operating solution providers requires due diligence beyond brochure comparisons. The study maps capability profiles, product philosophies, and recent activity so that engineering and procurement teams can frame RFPs with greater precision.
- Risk and compliance readiness. Safety standards, material price volatility, and labor-driven demand shifts are no longer peripheral concerns. They affect system design, integration cost, and lifecycle operating expense. The analysis embeds these realities so that risk is priced into business cases rather than discovered post-deployment.
- Scenario planning. Long-range forecasts are most valuable when they support branching contingencies. The forecast window through 2032 enables stress-testing of volume assumptions, technology adoption pathways, and regional expansion plans under multiple operating conditions.
These functions are especially relevant in 2026 because organizations are making commitments that will shape facility operations well into the next decade. Whether the decision involves greenfield automation, brownfield line upgrades, or multi-site standardization, the study is designed to reduce ambiguity without oversimplifying the operational complexity that conveyor integration entails.
Segmentation Architecture and Competitive Structure
A market of this scale is never homogeneous. Revenue concentration, system-type distribution, application demand, and regional deployment patterns collectively determine where opportunity and risk are concentrated. The study disaggregates these layers so that strategists can distinguish between headline growth and the underlying pockets of momentum.
Market concentration remains significant, with the three largest competitors accounting for roughly 54.6 percent of sector revenue and the five largest reaching approximately 67.2 percent. That level of concentration has direct implications for negotiation leverage, integration partnerships, and supply continuity. It also underscores the importance of understanding not only the dominant players but also the specialized manufacturers and integration-focused firms that influence pricing dynamics, customization capacity, and regional service coverage.
The segmentation framework addresses three axes that matter operationally:
- System type. Pallet conveyor architectures vary substantially in mechanical design, load handling philosophy, and integration behavior. The study separates major type categories to clarify where design preferences, maintenance profiles, and throughput requirements diverge. Drag chain roller systems, plastic-type constructions, and slat-type designs each present distinct trade-offs in durability, flexibility, cleanability, and precision control. Decision-makers evaluating technology roadmaps benefit from understanding which architectures align with specific operational constraints rather than treating the category as interchangeable.
- Application context. Demand is shaped by the operational environment in which conveyors are deployed. Retail and logistics operations, industrial manufacturing environments, and food and beverage processing each impose different hygiene, throughput, changeover, and traceability requirements. Mapping application-level demand patterns helps executives align capacity investments with end-use realities rather than relying on generic automation assumptions.
- Regional deployment. Geographic distribution of revenue reflects infrastructure maturity, logistics network density, labor market conditions, and regulatory environments. The study separates regional revenue patterns to help leaders identify where adoption is most established, where growth is accelerating, and where local sourcing, service, and compliance considerations should influence procurement strategy.
Importantly, this briefing is structured to communicate the strategic shape of these segments without diluting the analytical value of the full report. The complete study provides the depth required to pinpoint where specific product architectures, application verticals, and regional pathways are converging or diverging over the 2026–2032 window.
Palletizer Market
Competitive Landscape: Capability Profiles and Strategic Positioning
The competitive field in pallet conveyor systems is defined by a blend of specialized manufacturers, globally operating platforms, and custom integration providers. Each brings a distinct posture toward engineering, throughput control, modularity, and service scope. The study profiles the organizations shaping this environment so that buyers and investors can interpret competitive behavior with greater accuracy.
Among the companies examined are firms whose product philosophies and operational footprints illustrate the diversity of the market. Alba Manufacturing, based in Albany, Oregon, concentrates on heavy-duty, pre-engineered pallet handling conveyor systems oriented toward industrial applications. Hytrol Conveyor Co., headquartered in Jonesboro, Arkansas, provides complete pallet handling conveyor systems and solutions for material handling across varied weights and environmental conditions. Interroll, operating globally from Switzerland, offers a Modular Pallet Conveyor Platform alongside integrated pallet handling components for conveyors, sorters, and storage systems. Dorner Manufacturing, located in Hartland, Wisconsin, specializes in pallet system conveyors featuring dual-move and timing belt-driven configurations for more precise flow control. mk North America, based in Michigan, manufactures VersaFlex pallet conveyor systems designed for adaptable, quick-change pallet handling in assembly and production environments. Roach Conveyors, operating from Sullivan, Missouri, produces American-made engineered pallet, package, and modular conveyor systems for warehousing and manufacturing. Swisslog, also headquartered in Switzerland with global operations, develops ProMove pallet conveyor systems integrated with automated storage and retrieval systems for automated warehouse and distribution facilities. Ashland Conveyor, based in Akron, Ohio, supplies custom material handling and warehouse conveyor systems, including pallet handling solutions. Adaptecsolutions, operating in the United States, distributes and integrates custom pallet conveyor systems engineered to client specifications. Pack Air Inc., also based in the United States, manufactures custom heavy-duty pallet conveyor systems using chain-driven live-roller and drag-chain technology.
This breadth matters because pallet conveyor purchasing decisions rarely reduce to a single specification sheet. A facility prioritizing rapid line reconfiguration will evaluate vendors differently from one prioritizing heavy-load durability, hygiene compliance, or AS/RS integration. Likewise, organizations assessing supply risk or partnership stability benefit from understanding how each player positions itself across engineering capability, geographic reach, and system integration depth. The study's competitive analysis lends structure to these evaluations, enabling more disciplined vendor shortlisting and more credible negotiation positioning.
Market Dynamics: Cost Pressure, Regulation, and Demand Drivers
Pallet conveyor adoption does not expand in a vacuum. It responds to operational costs, compliance mandates, and structural changes in how goods move through logistics and manufacturing networks. Three interlocking dynamics shape the current environment and inform the study's forward-looking analysis.
Pallet Conveyor Market
Labor conditions remain a decisive demand catalyst. Continued labor shortages and rising labor costs in logistics and manufacturing operations are driving demand for pallet conveyor automation. As facilities confront throughput targets with constrained staffing, automation shifts from optional efficiency tooling to operational necessity. This pressure increases the strategic weight of conveyor investments, particularly where systems can reduce manual material handling, standardize flow, and improve repeatability across shifts.
Material cost volatility introduces a parallel layer of complexity. Steel-mill product prices increased by 12 percent year-over-year during 2024–2025, while fluctuations in aluminum and copper prompted fabricators to implement price-escalation clauses that raised conveyor costs by approximately 8–10 percent. For procurement teams and project financiers, these movements affect not only initial capital expense but also contract structuring, vendor negotiations, and total cost of ownership modeling. The study incorporates these pressures so that leadership can anticipate cost volatility rather than absorb it as an after-the-fact surprise.
Regulatory and safety requirements are simultaneously becoming more explicit. EN619:2022 sets comprehensive safety requirements for pallet transport conveyors, mandating protective gaps and compliance with EN ISO 13854:2019 for mechanical handling of unit loads. In parallel, OSHA references ANSI/ASME B20.1 as the industry consensus standard for conveyor safety, with integrators required to perform documented risk assessments under EN ISO 12100 and achieve Performance Level under EN ISO 13849. These standards shape engineering specifications, integration obligations, and documentation burdens. They also influence vendor selection, because compliance maturity increasingly differentiates suppliers in competitive evaluations. Recent product activity reflects this direction: Swisslog's ProMove pallet conveyor system achieved certification for EN619:2022 safety standards with advanced protective features. Meanwhile, Alba Manufacturing exhibited at MODEX 2026 with heavy-duty pallet handling conveyor solutions, signaling continued in-market visibility and product iteration among established participants.
Together, these dynamics create a market environment where strategic decisions must account for operational labor economics, material cost exposure, and compliance readiness in the same frame. The study integrates these forces so that executives can evaluate pallet conveyor investment as a coherent business case rather than as a sequence of disconnected considerations.
What the Full Study Delivers
This briefing outlines the strategic frame; the complete report supplies the analytical infrastructure required to act on it. The study is built for teams that need to translate market conditions into procurement plans, capacity commitments, vendor comparisons, and long-range facility strategies. Its scope includes:
- A detailed revenue baseline and forward forecast that situates current market size within a projected growth path, enabling multi-year planning with a defined CAGR anchor.
- Segment-level analysis across system types, application environments, and regional deployment patterns, designed to help readers identify where demand is concentrated and where architectural or operational differentiation matters most.
- Competitive profiling of key manufacturers and integration-oriented providers, with attention to product philosophy, operational footprint, and recent market activity.
- Evaluation of market dynamics including labor-driven automation demand, raw material price pressure, and evolving safety and compliance standards, integrated into the broader investment narrative.
- Structured context for scenario planning, so leadership teams can test assumptions regarding volume growth, technology adoption, regional expansion, and vendor strategy over the 2026–2032 window.
The report is intended for use by strategy leaders, operations executives, engineering and procurement teams, and investors seeking a grounded view of where pallet conveyor demand is headed and how competitive forces are shaping purchasing conditions. It is designed to support decisions that must hold up under technical review, financial scrutiny, and compliance validation.
Conclusion: Translating Market Intelligence into 2026 Execution
The Pallet Conveyor Market is expanding within a landscape defined by durable demand drivers and increasingly specific operational constraints. Sustained mid-single-digit growth, meaningful revenue concentration, and a competitive field spanning specialized manufacturers and globally integrated solution providers all point to a market where informed selection matters as much as timing. At the same time, labor economics, metal price volatility, and tightening safety standards are reshaping how systems are specified, priced, and integrated.
For organizations making 2026 commitments, the strategic question is no longer whether pallet conveyor automation has relevance, but how to evaluate it with enough precision to avoid over- or under-investing relative to actual operational needs. That requires more than headline market size. It requires segment clarity, vendor context, dynamic risk factors, and a forecast structure that supports decision-making across multiple possible futures.
The full PW Consulting Pallet Conveyor Market study is built to provide that depth. Readers seeking complete segmentation detail, concentration analysis, vendor positioning frameworks, and forecast-supported scenario inputs are encouraged to access the full report through the source page, where the complete intelligence package is available for strategic review and operational planning.
For detailed analysis of this topic, please visit the official page: Pallet Conveyor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Doors Market Hits $12,180 Million in 2025, Projects 4.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating Safety and Growth: Strategic Imperatives in the Global Fire Doors Market (2026–2032)
In an era where regulatory scrutiny and asset protection converge, the fire doors market has evolved from a passive compliance expenditure into a dynamic strategic asset class for facility owners, contractors, and investors. As organizations across commercial, residential, industrial, healthcare, and educational sectors reassess their life-safety infrastructure, understanding the nuanced trajectory of this segment is critical for capital allocation and risk management in 2026 and beyond.
PW Consulting’s latest comprehensive analysis of the Fire Doors Market provides decision-makers with the granular intelligence required to navigate this complex landscape. This article outlines the high-level market trajectory, the shifting dynamics driven by regulation and material innovation, and the competitive maneuvers shaping the industry. It serves as a strategic primer to the full report, which offers exhaustive segmentation, detailed company profiling, and forward-looking scenario analysis essential for formulating robust market entry, procurement, and investment strategies.
The Macro Trajectory: Sustained Growth Anchored by Safety Mandates
The global market for fire doors has demonstrated consistent resilience and expansion over the past five years. Valued at approximately USD 9.88 billion in 2020, the market has grown steadily to reach an estimated USD 12.18 billion by 2025. This historical progression reflects not only the recovery from broader economic fluctuations but also the compounding effect of stricter building codes, urbanization trends, and heightened awareness of fire safety in both new construction and retrofit projects.
Looking ahead, the forecast period from 2026 to 2032 signals continued upward momentum. The market is projected to surpass the USD 12.9 billion mark in 2026, with growth accelerating through the latter half of the decade. By 2032, the total market revenue is anticipated to approach USD 16.06 billion. This expansion is underpinned by a Compound Annual Growth Rate (CAGR) of 4.2% over the forecast horizon.
Important Note: These aggregate figures mask significant variability across materials, applications, and geographies. The full report dissects these variables to reveal which specific sub-segments are outperforming, where saturation risks lie, and how regional regulatory environments are skewing demand. Relying on top-line numbers alone can lead to misallocated capital; sector-specific intelligence is paramount.
Market Dynamics: Regulation, Technology, and Supply Chain Realignment
Regulatory Evolution as a Primary Demand Driver
The regulatory landscape is undergoing a transformative shift, fundamentally altering how fire door assemblies are specified, installed, and maintained. The 2025 edition of NFPA 80, Standard for Fire Doors and Other Opening Protectives, has introduced rigorous requirements that extend beyond initial installation. It mandates immediate inspection following installation and a minimum annual inspection cycle thereafter. Furthermore, the introduction of performance-based inspection, testing, and maintenance options under Annex J provides facility managers with flexibility but also demands higher levels of documentation and technical competency.
In parallel, regional certification mandates are tightening. In India, the Bureau of Indian Standards (BIS) Quality Control Order (QCO) and IS 3614:2021 certification have become mandatory for wooden and metal fire doors sold in the market starting in 2025. This shift is reshaping procurement strategies for stakeholders operating in South Asia, forcing a re-evaluation of supply chains and approved vendor lists.
Additionally, upcoming revisions to UL 10C, effective 2026, will enhance security and resistance requirements for locks and latches on fire-rated door assemblies. This convergence of fire safety and security standards is creating new integration challenges and opportunities for manufacturers who can deliver holistic solutions.
The Shift Toward Full-System Certification
The industry is moving decisively away from component-level assumptions toward full-assembly certification. Fire door assemblies must now be tested as complete systems, including the door leaf, frame, hardware, seals, and glazing, under ISO/IEC 17025 accredited full-assembly testing protocols. This trend raises the barrier to entry for smaller players and favors integrated solution providers. It also compels procurement teams to scrutinize not just the door leaf, but the entire ecosystem of hardware and installation protocols to ensure compliance and liability protection.
Material and Application Nuances
While metal continues to dominate the material mix due to its durability, fire resistance ratings, and suitability for commercial applications, the market is witnessing nuanced shifts. Timber and wood remain significant, particularly in residential and design-focused commercial projects, while glass fire doors are carving out specialized roles in healthcare and luxury commercial spaces where visibility and aesthetics are paramount.
Applications distribution reveals that commercial buildings represent the largest demand pool, driven by high-density occupancy and stringent code enforcement. Residential buildings follow as a substantial contributor, fueled by urbanization and multi-family housing developments. Industrial facilities, healthcare facilities, and educational facilities constitute vital specialized segments, each with unique performance requirements regarding hygiene, acoustic control, hazardous material handling, and durability under heavy use.
Important Note: The report provides a detailed breakdown of material and application splits, quantifying the exact revenue contributions and growth rates for each category. It also highlights which applications are experiencing the fastest adoption of specific materials and the strategic implications of these trends for suppliers. Do not rely on generalized assumptions about market mix; the detailed segmentation analysis exposes hidden opportunities and competitive vulnerabilities.
Security Door Market
Competitive Landscape: Consolidation and Differentiation
The fire doors market is characterized by a fragmented but strategically active competitive environment. While market concentration metrics indicate that the top three players hold a modest share and the top five maintain a slightly higher aggregate presence, the landscape is defined by intense competition between global giants, regional specialists, and manufacturers leveraging geographic advantages.
Key Players and Strategic Maneuvers
Leading multinational corporations continue to solidify their positions through acquisitions and product innovation. ASSA ABLOY, headquartered in Sweden, provides fire-rated doors, frames, and integrated door systems with UL-listed fire protection offerings tailored for commercial and institutional applications. In April 2025, ASSA ABLOY acquired Door System, a Danish manufacturer of fire-rated doors serving pharmaceutical, food, and retail sectors, signaling a strategic push into specialized hygiene and high-traffic environments.
Dormakaba, based in Switzerland, manufactures fire-rated doors, frames, and low-energy door assistants certified to UL and international standards. At BAU 2025, Dormakaba introduced EasyAssist Pro, a low-energy door assistant for fire-rated doors, addressing the growing demand for accessibility and energy efficiency in building operations.
JELD-WEN, headquartered in the USA, offers fire-rated door systems including wood and metal doors listed for fire resistance under UL 10C and NFPA 252, maintaining a strong footprint in North America. Steelcraft, also a US-based manufacturer, specializes in fire-rated steel doors and frames rated up to 3 hours, compliant with UL 10C and NFPA 252 for commercial use, catering to high-performance requirements.
Republic Doors & Frames, another US player, produces fire-rated steel doors and frames with positive-pressure and zero-pressure ratings under UL 10C and NFPA 252, emphasizing versatility in pressurized environments. Allegion, with operations extending from Ireland to the US, supplies fire-rated doors, frames, and hardware assemblies certified to UL standards including UL 10C and NFPA 252. In February 2025, Allegion completed the acquisition of Lemaar, an Australian door hardware company specializing in entry systems for fire-rated doors, expanding its integrated hardware capabilities in the Asia-Pacific region.
SAFTI First stands out as a manufacturer of fire-rated glass and door systems with full-assembly certifications for UL-listed fire protection, offering unique value propositions in applications where glazing and fire resistance must coexist. Chace Industries produces fire-rated steel doors and frames for institutional and commercial markets under UL and NFPA standards, reinforcing the competitive density in North America.
European manufacturers are also active. Metaflex Doors, based in the Netherlands, supplies fire-rated doors and frames with European and international certifications including UL listings. GEZE, from Germany, provides fire-rated door systems and accessories with full-assembly testing for UL and NFPA compliance. The Lindner Group, a German manufacturer, produces fire-rated doors with German and international UL-listed fire resistance certifications. NINZ S.p.A., based in Italy, produces fire-rated doors and frames certified under European and UL standards. Agta record and Gilgen Door Systems, both Swiss manufacturers, contribute fire-rated doors and frames and systems respectively, certified to UL and European standards, leveraging the Swiss reputation for precision engineering.
In the United States, Ceco Door specializes in engineered steel fire-rated doors and frames for commercial and institutional projects, while AMBICO offers fire-rated and acoustic door systems with UL listings for hazardous and secure environments.
Emerging and Regional Contenders
Global reach is expanding through manufacturers in Asia and India. Sanwa Holdings, based in Japan, develops fire-rated doors with Japanese manufacturing precision and UL international certifications, positioning itself for export markets. Yuankai Door and Buyang Group, both from China, produce fire-rated doors and frames with UL and international listings for global markets. Buyang Group, as a large-scale producer, competes on volume and cost efficiency in the steel fire-rated door segment.
Godrej Security Solutions, based in India, offers fire-rated doors and security solutions with ISI and UL listings in India and international markets, aligning with the domestic regulatory push and export ambitions.
Important Note: The report contains exhaustive profiles of all these key companies, including strategic analysis, revenue implications of recent developments, competitive positioning maps, and detailed assessments of their product portfolios and geographic strengths. Understanding the specific moves of each competitor is essential for benchmarking, partnership evaluation, and threat assessment. The full analysis reveals which companies are gaining share, where capacity expansions are occurring, and how M&A activity is reshaping supply alliances.
Recent Developments: M&A and Standard Updates Reshaping the Field
The competitive dynamics are further influenced by recent strategic events. In December 2025, Investcorp completed the acquisition of Guardian Fire Services, a leading US provider of fire and life safety services including fire doors. This move underscores the growing interest in integrated service models that combine product supply with inspection, maintenance, and compliance management, particularly in light of the new annual inspection mandates under NFPA 80.
Meanwhile, the NFPA released the 2025 edition of NFPA 80 in March 2025, introducing updated inspection frequency and performance-based options. This regulatory update is expected to create immediate demand for inspection services and compliant hardware upgrades, influencing procurement cycles and vendor selection criteria across the industry.
Fire Doors Market
Important Note: The report evaluates the impact of these recent developments, including the financial and strategic ramifications of acquisitions, the market reception of new products like Dormakaba EasyAssist Pro, and the specific compliance challenges posed by the 2026 UL 10C revision. It also tracks upcoming trends and potential future catalysts. Without this forward-looking context, organizations risk being caught off-guard by supply chain shifts or regulatory non-compliance.
Regional Insights: Divergent Growth Patterns
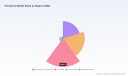
Geographically, the market exhibits distinct growth paces and regulatory drivers. North America remains a mature but steady market, driven by retrofit activity, healthcare expansion, and compliance with updated NFPA standards. Europe continues to emphasize high-performance materials and integrated systems, with strong regional players leveraging European certifications alongside UL listings for global projects.
Asia Pacific stands out as a region of significant scale and dynamic growth, fueled by rapid urbanization, infrastructure development, and the implementation of local mandatory certification regimes such as BIS in India. Latin America and the Middle East and Africa are emerging as important markets, though they face unique challenges related to supply chain localization, certification harmonization, and varying levels of regulatory enforcement.
Important Note: The full report provides a detailed regional analysis, quantifying market sizes and growth trajectories for each region without relying on broad generalizations. It identifies key country-level opportunities, regulatory bottlenecks, and the competitive intensity within each geography. This regional granularity is critical for companies planning market entry, distributors seeking to optimize territory coverage, and investors assessing regional risk profiles.
Strategic Recommendations for 2026 Decision Makers
As the market moves toward projected valuation milestones and navigates evolving regulatory requirements, organizations must adopt a proactive rather than reactive stance. Strategic actions for 2026 should include:
- Audit Compliance Against 2025 NFPA 80 Updates: Facility managers and contractors must ensure that inspection protocols align with the immediate post-installation and annual inspection mandates, as well as explore performance-based options under Annex J where applicable. Non-compliance carries escalating liability risks.
- Evaluate Full-Assembly Certification: Procurement teams should prioritize vendors who can demonstrate ISO/IEC 17025 accredited full-assembly testing for the complete door, frame, hardware, and glazing system. This reduces integration risk and ensures that the performance rating applies to the installed configuration.
- Monitor Material and Application Trends: While metal remains a workhorse, understanding the specific growth pockets in timber, glass, and composite materials, and their alignment with particular applications like healthcare or residential, allows for targeted product development and marketing.
- Assess Supply Chain Exposure to Regional Mandates: With India enforcing mandatory BIS QCO and IS 3614:2021 certification, and UL 10C revisions impacting hardware in 2026, organizations must review vendor certifications and ensure continuity of supply for compliant components.
- Watch Competitive M&A Activity: The acquisition of Door System by ASSA ABLOY and Guardian Fire Services by Investcorp, along with Allegion’s move on Lemaar, signals consolidation and a push toward integrated service and hardware solutions. Organizations should assess how these moves affect pricing, availability, and the competitive landscape in their target segments.
- Leverage Granular Intelligence for Capital Allocation: The aggregate market size and CAGR provide a directional signal, but profitable decisions depend on knowing exactly which material-application-region combinations are driving the highest margins and fastest growth. The full PW Consulting report delivers this level of detail.
Conclusion: The Strategic Value of the Fire Doors Market Research
The global fire doors market stands at an inflection point where regulatory rigor, technological integration, and competitive consolidation are reshaping the value chain. For stakeholders in 2026, success will depend on more than just observing broad market growth; it requires deep, segmented intelligence that connects macroeconomic trends to actionable operational insights.
This overview has highlighted the market’s robust trajectory, the transformative impact of NFPA 80 and full-assembly testing, and the strategic moves of key global and regional players. However, to fully capitalize on these insights, decision-makers need access to the complete analytical framework provided in PW Consulting’s dedicated Fire Doors Market report.
Important Note: The comprehensive report goes far beyond these summaries. It delivers precise market size estimates and CAGR breakdowns for every material, application, and region. It provides detailed competitive profiling, including strategic analysis, SWOT evaluations, and supply chain assessments for each key company. It includes a thorough analysis of recent developments, their financial implications, and future outlooks. It also offers strategic recommendations tailored to specific stakeholder roles, from manufacturers to investors and facility operators.
For organizations committed to making informed, risk-adjusted decisions in the coming year, the full market research report is an indispensable tool. It transforms high-level trends into a navigable roadmap, exposing the hidden data points that separate strategic leaders from the competition. Access the complete intelligence to secure your competitive edge in the evolving fire doors landscape.
For detailed analysis of this topic, please visit the official page: Fire Doors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nuclear Valve Market Hits $2,143.69M in 2025, Projected 6.1% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Nuclear Valves Market: A 2026 Decision-Maker's Guide
The nuclear energy sector stands at a critical inflection point. As global decarbonization mandates intensify and energy security concerns reshape national strategies, the reliability of nuclear infrastructure has never been more pivotal. At the heart of this infrastructure lies a specialized, high-stakes component market: nuclear valves. These engineered systems are not merely ancillary equipment; they are the guardians of containment, pressure regulation, and safety protocols within some of the world's most hazardous environments. For executives navigating capital allocation, supply chain resilience, and technology roadmaps, understanding the trajectory of the nuclear valves market is essential.
This article serves as a strategic preview of PW Consulting's latest comprehensive market intelligence product. It outlines the macro-economic currents driving the sector, highlights the competitive architecture defining the landscape, and explains why access to granular, forward-looking data is indispensable for outperforming in 2026. By synthesizing historical performance with projected growth vectors, we provide a foundation for decisions that will define operational success over the next half-decade.
The Macro Landscape: Growth, Scale, and Trajectory
The nuclear valves market has demonstrated consistent resilience and expansion over the past five years. Drawing from our analysis of historical data spanning 2020 through 2025, the market has evolved from a base valuation of 1.60 billion USD in 2020 to an estimated 2.14 billion USD in 2025. This represents a compound annual growth trajectory that underscores the sector's steady maturation and the sustained investment in nuclear capacity worldwide.
Nuclear Valves Market
Looking ahead, our forecast model projects the market to reach 2.23 billion USD in 2026, continuing a growth arc that extends through 2032. By the end of the forecast period, the market is anticipated to approach 3.25 billion USD. This expansion is underpinned by a forecast-period CAGR of 6.1 percent, a figure that signals robust demand driven by reactor restarts, new-build programs, and the modernization of aging facilities. The growth is not merely nominal; it reflects deepening complexity in valve specifications, stricter regulatory compliance requirements, and the integration of advanced materials and digital monitoring systems.
While the headline figures paint a picture of steady expansion, the underlying dynamics are nuanced. Value creation is increasingly concentrated within specific engineering niches, where differentiation stems from certifications, heritage in safety-critical applications, and the ability to support both legacy reactors and emerging technologies like small modular reactors (SMRs). The market's structure, characterized by a consolidated landscape where the top three players command significant share and the top five entities control a substantial majority of revenue, suggests that competitive advantages are deeply entrenched. This concentration implies that new entrants face high barriers, while incumbents leverage long-term utility relationships and certified manufacturing capabilities to maintain pricing power and customer stickiness.
Unpacking the Forecast: Beyond Aggregate Numbers
A superficial glance at the market trajectory might suggest a uniform growth environment. However, the strategic reality is far more segmented. The distribution of value across valve types reveals distinct engineering priorities. Gate valves and globe valves continue to dominate the revenue mix, reflecting their foundational roles in isolation, throttling, and high-integrity containment within nuclear circuits. Ball valves and butterfly valves occupy significant positions, particularly in applications demanding rapid actuation and lower flow resistance profiles. Check valves, diaphragm valves, and other specialized types round out a diversified portfolio that responds to the heterogeneous needs of nuclear facilities.
The application domain further stratifies the market. Nuclear power plants remain the primary revenue engine, absorbing the lion's share of demand as operators focus on reliability, life extension, and compliance with evolving safety codes. Yet, adjacent segments are gaining traction. Research reactors and nuclear waste management applications represent specialized, high-value niches where valve performance criteria diverge sharply from commercial power settings. Waste management, in particular, introduces unique challenges around radiation resistance, long-term sealing integrity, and material degradation, driving demand for purpose-built solutions that command premium positioning.
Geographically, the market's footprint is broad but uneven. Asia Pacific has emerged as a region of considerable scale, reflecting the aggressive nuclear expansion programs in several key economies. North America and Europe continue to represent mature, high-compliance environments where valve procurement is heavily influenced by regulatory frameworks, long-term service agreements, and the need for certified domestic or allied supply chains. Latin America and the Middle East and Africa, while smaller in absolute terms, are regions where infrastructure development and energy diversification initiatives are creating incremental opportunities for qualified suppliers. Understanding how these regional dynamics interact with local content requirements, sanctions regimes, and technology transfer restrictions is essential for firms planning cross-border strategies.
Competitive Architecture: The Incumbents and the New Dynamics
The competitive landscape of the nuclear valves market is defined by a cadre of firms that have invested decades in building technical credibility, regulatory certifications, and deep relationships with utility operators. These companies do not compete solely on price; they compete on audit-ready documentation, code compliance, heritage in specific reactor types, and the ability to deliver integrated valve-actuator packages with full lifecycle support.
Crane Nuclear, headquartered in Kennesaw, Georgia, exemplifies long-standing heritage in the sector. Since 1956, the firm has specialized in manufacturing nuclear-grade gate, globe, check, and quarter-turn valves bearing ASME N and NPT stamps for Class 1, 2, and 3 applications. Its historical footprint includes supplying valves for the first commercial nuclear power plant at Shippingport, and its ongoing diagnostics and services offerings reinforce its position as a trusted partner for commercial nuclear power plants. This legacy translates into a competitive moat built on decades of operational data, regulatory familiarity, and customer trust.
Neway Valve, based in Suzhou, Jiangsu, China, represents the growing capability of Asian manufacturers to meet rigorous international standards. The company produces nuclear gate, ball, globe, check, and butterfly valves qualified to NNSA Grade 1, 2, and 3 design and manufacturing licenses, alongside full ASME N and NPT certificates. Its portfolio is tailored for EPR, AP1000, and Hualong-1 reactors, positioning it as a supplier capable of supporting both established and next-generation reactor designs with full-range nuclear compliance. This dual certification footprint allows Neway to serve markets that demand both domestic regulatory approval and internationally recognized code compliance.
Trillium Flow Technologies, located in Huddersfield, United Kingdom, brings a focused engineering approach to nuclear valves and actuators. The company designs and manufactures engineered nuclear valves and actuators with ASME Section III N and NPT stamps, including safety relief and specialty valves for new-build and operating reactors worldwide. Its active ASME Section III N and NPT stamps at two production sites underscore a commitment to redundancy and supply chain resilience, qualities that are increasingly valued by operators seeking to mitigate single-source vulnerabilities.
Velan Inc., headquartered in Montreal, Quebec, Canada, has carved out a distinctive role in the nuclear space. The company produces nuclear Class 1, 2, and 3 gate, globe, check, and ball valves under ASME N and NPT certificates, and has expanded its relevance into the SMR domain, including projects such as the BWRX-300. Notably, Velan secured the first ASME N stamp for nuclear valves in 1971, and it remains the only manufacturer supplying nuclear valves to the first U.S. small modular reactor project. In October 2025, Velan secured a main services agreement for valves on North America's first small modular reactor project, marking a milestone in the commercialization of SMR valve supply chains.
Flowserve Corporation, based in Irving, Texas, USA, operates at the intersection of pumps, valves, and seals for nuclear applications. Its supply of nuclear-qualified equipment across Class 1-3 applications for global nuclear projects is supported by long-term utility relationships and ongoing SMR qualification programs. Flowserve's breadth of portfolio and established service networks make it a versatile partner for operators seeking integrated fluid control solutions.
Framatome, headquartered in Paris, France, leverages its broader reactor systems expertise to deliver safety-related nuclear valves and actuators. Through subsidiaries including Valserve, Framatome designs and manufactures components for PWRs, BWRs, and advanced reactors under ASME III, RCC-M, and other codes. In April 2025, Framatome completed the acquisition of Trillium Flow Technologies France, rebranding it as Sebim to strengthen its nuclear valves product line. This move signals a strategic consolidation within the European supply base, aiming to bundle valve and actuator capabilities under a unified engineering umbrella. Concurrently, in April 2025, Bruce Power signed a 10-year alliance with Trillium Flow Technologies for nuclear valve supply and related services, illustrating how long-term partnerships are becoming a defining feature of the market's procurement architecture.
Regulatory and Technical Dynamics Shaping Procurement
The nuclear valves market operates within a tightly regulated environment where certification is not a formality but a prerequisite for market access. ASME N and NPT stamps, along with national regulatory approvals such as NNSA grades, function as gatekeepers that separate qualified suppliers from the broader industrial valve market. Companies like Crane Nuclear, which has maintained ASME N and NPT stamps since its inception, and Neway Valve, which holds NNSA Grade 1, 2, and 3 licenses plus full ASME certifications, demonstrate how regulatory standing is intertwined with commercial viability. Trillium Flow Technologies' dual-site ASME Section III N and NPT stamp coverage further highlights how manufacturers are building geographic and operational redundancy to satisfy utility procurement requirements and risk management protocols.
These regulatory dynamics have direct implications for supply chain planning. Utilities and EPC contractors increasingly prioritize vendors that can demonstrate traceability, material certification, and code compliance at every stage of the valve lifecycle. The presence of ASME stamps, the ability to support Class 1, 2, and 3 applications, and the capacity to provide diagnostics and services are becoming differentiators that influence bid evaluation criteria. In this context, market participants that invest in certification maintenance, quality system upgrades, and digital documentation are better positioned to capture high-value contracts and sustain margins.
Why Granular Intelligence Matters for 2026 Decision-Making
While the macro trends and competitive profiles outlined here provide a strategic compass, they are insufficient on their own for operational planning. The nuances that drive procurement decisions, pricing negotiations, and technology adoption are embedded in the granular detail of the market. For example, understanding how the revenue split across valve types correlates with specific reactor programs, or how regional demand patterns align with local content mandates, requires access to segmented data that reveals the interplay between engineering specifications, regulatory environments, and commercial execution.
Valves Market
Similarly, the competitive dynamics are not static. Acquisitions, alliance formations, and certification expansions can shift market share, alter supply chain dependencies, and redefine the value proposition of incumbents overnight. The recent acquisition of Trillium Flow Technologies France by Framatome and the 10-year alliance between Bruce Power and Trillium Flow Technologies are indicative of a market where strategic bundling and long-term service commitments are reshaping competitive boundaries. Decision-makers need to know not just who the players are, but how their capabilities, geographic footprints, and partnership networks are evolving in real time.
This is precisely why PW Consulting's Nuclear Valves Market report is structured to deliver actionable intelligence beyond top-line forecasts. The report provides a deep dive into the segmentation landscape, competitive positioning, regulatory frameworks, and demand drivers that collectively inform capital allocation, vendor selection, and risk mitigation strategies. By mapping the revenue distribution across valve types, application domains, and regions, the report equips stakeholders with the context needed to identify growth pockets, anticipate supply constraints, and align product development with the most promising market vectors.
For executives planning 2026 initiatives, the report offers a structured framework to evaluate where to invest, whom to partner with, and how to navigate the certification and compliance pathways that gate market entry. Whether the objective is to expand into new reactor programs, secure long-term service agreements, or assess the impact of SMR commercialization on valve demand, the granular data and analytical rigor contained in the full report provide a reliable foundation for evidence-based decision-making.
Navigating Forward: From Insight to Action
The nuclear valves market is on a sustained growth trajectory, but growth alone does not guarantee strategic success. The firms that thrive will be those that translate market awareness into disciplined execution: investing in certified manufacturing capabilities, forging durable utility partnerships, adapting to the technical demands of advanced reactors and SMRs, and maintaining a vigilant eye on regulatory evolution. As the market approaches the 2026 horizon, the difference between reactive participation and proactive leadership will be determined by the quality of intelligence and the speed with which insights are operationalized.
PW Consulting's comprehensive research is designed to be that intelligence engine. By delivering a detailed, data-rich, and strategically oriented view of the nuclear valves market, the report enables stakeholders to cut through noise, focus on high-impact variables, and make decisions that compound value over the forecast period. The full analysis, including segmentation breakdowns, competitive assessments, and forward-looking scenarios, is available in the complete report. For those ready to move from strategic overview to precision planning, the next step is to access the full intelligence package and begin aligning 2026 agendas with the realities of a market in transformation.
For detailed analysis of this topic, please visit the official page: Nuclear Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cryocoolers Market Hits $215M in 2025, Projected 6.98% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the 2026 Decision-Maker: Inside the Global Cryocoolers Market
As industrial ecosystems pivot toward extreme-temperature applications, the cryocooler sector has transitioned from a niche enabling technology to a strategic growth vector. Over the past five years, the market has demonstrated sustained expansion, with historical revenue trajectories showing a clear acceleration from approximately 163.15 million USD in 2020 to 201.13 million USD in 2024. This momentum carried the base year valuation to 215.0 million USD in 2025, and the forward trajectory points toward a forecasted valuation of 222.53 million USD in 2026. More importantly, the sector is positioned to compound at a steady pace through 2032, with revenue projections reaching 344.8 million USD by the end of the forecast horizon. For executive teams navigating capital allocation, supply chain resilience, and technology roadmapping in 2026, these macro indicators are only the starting point. The real strategic value lies in understanding how structural shifts across defense, healthcare, aerospace, and advanced research are rewiring demand patterns, competitive positioning, and regulatory boundaries.
Why 2026 Demands a Deeper Market Lens
The year 2026 represents a critical inflection point for organizations operating in or adjacent to cryogenic cooling. Demand is no longer driven by a single vertical; instead, it is being shaped by converging technology roadmaps, procurement cycles, and compliance frameworks that vary significantly by region and application. Executive decisions made today—whether evaluating supplier partnerships, assessing capacity expansion, or prioritizing R&D investments—will lock in competitive advantages or expose vulnerabilities across the next several budget cycles. A high-level revenue chart cannot answer whether a given technology type is gaining share in specialized instrumentation, whether regional procurement dynamics are shifting procurement leadership, or how recent regulatory updates are altering go-to-market timelines. That level of granularity requires a structured, data-backed assessment that connects historical performance to forward-looking demand signals.
Market Architecture and Structural Dynamics
The cryocoolers market is defined by a fragmented yet increasingly strategic competitive landscape. Concentration metrics indicate that the top three players account for roughly 24.6 percent of total revenue, while the top five reach approximately 26.2 percent. This distribution signals a market where scale matters, but specialization, application-level integration, and technology differentiation remain decisive. Organizations are not merely competing on cooling capacity; they are competing on vibration profiles, reliability in mission-critical environments, form-factor compactness, and the ability to embed cooling solutions into larger systems such as infrared sensor suites, medical imaging platforms, space payloads, and quantum research infrastructure.
Regulatory and Compliance Signals Redefining Market Access
Recent regulatory activity has introduced new layers of complexity for cross-border trade and technology deployment. In January 2026, Canada updated its Export Control List to include Category 2-20 cryogenic and superconductive equipment rated below 4K. This adjustment affects how certain high-performance cooling systems are classified, shipped, and integrated into international programs. At the same time, the U.S. Bureau of Industry and Security issued an interim final rule in September 2024 controlling cryocooling systems with cooling power at or below 0.1 K for periods exceeding 48 hours. These measures are not peripheral footnotes; they influence qualification pathways, partner selection, and the cost of compliance for companies serving defense, scientific, and advanced industrial customers. Decision-makers need to understand where these controls create friction, where they open procurement windows, and how to structure supply strategies that remain agile under evolving export requirements.
Cryopump Market
Technology Roadmaps and Mission-Driven Demand
Beyond compliance, long-duration space exploration and next-generation energy storage are reshaping technology expectations. NASA’s CACHE program, for example, requires demonstration of high-capacity cryocoolers at Technology Readiness Level 6 for liquid hydrogen storage on future long-duration Mars missions. Such programmatic milestones create demand signals that ripple through supplier pipelines, material selection, and testing regimes. Meanwhile, the broader research community continues to push for compact, low-vibration cooling solutions capable of supporting superconducting detectors, quantum technologies, and precision instrumentation. The convergence of government-backed mission requirements and commercial research needs means that technology readiness, reliability, and customization capability are becoming central battlegrounds for market share.
Competitive Landscape and Recent Strategic Moves
The competitive environment reflects a mix of established industrial manufacturers, defense and aerospace integrators, and specialized technology providers. Several firms have recently signaled their strategic priorities through product launches, contract awards, and conference-level technology disclosures, underscoring how fast the market is evolving.
Innovation Signals from Leading Participants
Sumitomo Heavy Industries has expanded its portfolio with high-capacity single-stage cryocoolers built around Whisper technology, a design approach aimed at quieter operation and reduced moving parts. This launch highlights a broader industry emphasis on minimizing mechanical complexity while improving operational consistency for space, medical imaging, and defense applications. In parallel, Bluefors introduced a compact two-stage pulse-tube cryocooler designed for advanced scientific applications and superconducting nanowire single-photon detectors, reinforcing the growing importance of precision cooling in quantum-oriented research and detector systems.
On the demand side, L3Harris Technologies secured a substantial contract from the U.S. Army for the production of Enhanced Night Vision Goggle-Binoculars incorporating compact cryocoolers. This award illustrates how cooling technology has become embedded in frontline defense systems, where size, weight, power, and reliability constraints directly shape procurement decisions. These moves are not isolated events; they are indicators of where engineering investment and commercial opportunity are converging.
Event-Driven Intelligence and Industry Coordination
Industry coordination is also accelerating. The 2026 International Cryocooler Conference is scheduled to convene in June in Syracuse, New York, bringing together technical presentations and cross-organizational discussions on cooling technology advancements. Events like this matter because they function as both innovation showcases and market signaling mechanisms. They reveal which architectures are gaining engineering traction, which application domains are attracting new development attention, and how suppliers are positioning themselves relative to emerging performance benchmarks. For strategists, such gatherings are essential inputs for monitoring technology diffusion and competitor intent.
What the Analysis Delivers for 2026 Planning
A rigorous market assessment should go beyond top-line projections and provide decision-makers with an operational view of the ecosystem. The full study is structured to translate macro growth signals into actionable intelligence across multiple planning dimensions.
Coverage Designed for Executive and Technical Decision-Making
The analysis integrates historical performance from 2020 through 2025 with a forecast framework extending to 2032, enabling teams to evaluate both near-term momentum and longer-cycle demand formation. Rather than presenting figures in isolation, the report maps revenue evolution against the technological and application forces that are shaping procurement behavior. This allows readers to assess where growth is likely to be durable, where it may be cyclical, and where competitive repositioning is already underway.
Deep-Dive Segmentation Without Losing Strategic Context
Segment-level insight is essential because cryocooler demand does not behave uniformly across technology types or end-use domains. The study dissects the market by cooling architecture and by application, providing a structured lens on where specific designs are gaining relevance and where end-use sectors are intensifying their cooling requirements. Equally important, the regional view helps organizations understand where demand concentration is forming and how geographic procurement patterns may influence sourcing, partnership, and expansion strategies. The full report preserves that segmentation detail while maintaining a coherent strategic narrative, so that readers can connect numeric structure to business implications instead of treating the data as disconnected tables.
Competitive Profiling and Ecosystem Mapping
The study also profiles the companies that are shaping the market’s direction. It examines organizations with established cryocooler portfolios as well as specialists focused on compact, low-vibration, or mission-specific solutions. The objective is to provide more than a roster of names: it is to clarify how different players are positioning themselves across space, defense, healthcare, industrial gas, research instrumentation, and advanced scientific applications. By mapping company focus areas, technology orientations, and recent commercial activity, the analysis helps buyers, investors, and competitors identify where consolidation pressures may emerge, where niche leadership is being built, and where integration capabilities are becoming a differentiator.
Cryocoolers Market
Why Strategic Procurement and Investment Decisions Depend on Granular Intelligence
In a market where concentration is moderate and application requirements vary sharply, the cost of incomplete information is high. A supplier selection decision made without a clear view of technology-type relevance can lead to integration challenges downstream. A market entry or expansion plan built without a realistic read on regional demand patterns can misallocate resources. A compliance strategy developed without attention to evolving export controls can slow program timelines and complicate partnership structures. These risks are amplified in 2026 because cooling technology is increasingly embedded in systems where performance, size, and regulatory status are inseparable from commercial success.
Turning Market Signals into Actionable Plans
The strongest use of this research is not simply to confirm that the market is expanding, but to determine where expansion is most strategically meaningful. For procurement leaders, the analysis supports supplier evaluation by clarifying which technology families align with specific operational constraints and which participants are actively advancing those designs. For investors and corporate development teams, it provides a structured basis for assessing where value creation is likely to concentrate and which segments are showing the strongest forward demand logic. For R&D and engineering leadership, it helps frame technology priorities in the context of market pull, program milestones, and competitive readiness.
Conclusion: The Strategic Case for Full-Market Clarity
The cryocoolers market is moving from steady growth to a more complex phase defined by application-specific performance demands, regulatory refinement, and targeted technological innovation. Historical data shows a market that has already expanded materially, and the forecast period suggests continued upward momentum toward the end of the decade. Yet the strategic questions facing organizations in 2026 are not answered by aggregate numbers alone. They require a detailed understanding of segmentation dynamics, competitive positioning, compliance impact, and the product-level moves that signal where the market is heading next.
This study is designed to provide that level of clarity. It connects the macro trajectory to the operational realities that decision-makers face when evaluating suppliers, planning capacity, aligning R&D priorities, or preparing for regulatory change. To access the complete segmentation breakdown, company profiles, regional and application-level intelligence, and the full forecast framework, visit the source page for the full Cryocoolers Market research. The detailed dataset and strategic commentary are available there for teams that need to move from market awareness to market action.
For detailed analysis of this topic, please visit the official page: Cryocoolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chemical Injection Metering Pumps & Valves Market Poised to Reach USD 4,700 Million by 2025
By pmarketresearch, 2026-08-18
Chemical Injection Metering Pumps & Valves Market: Strategic Imperatives for 2026
As upstream activity recalibrates after successive cycles of oil price volatility, and water- and process-intensive industries accelerate digital and sustainability investments, chemical injection metering pumps and valves remain a mission‑critical element of operational integrity. PW Consulting’s latest market study—covering 2020–2025 historical performance and offering a 2026–2032 forecast—translates these dynamics into an actionable decision framework for executive teams planning capital allocation, supplier strategy, and technology adoption in 2026.
Air & Water Rinsing Machines Market
Market trajectory at a glance
Our analysis shows the global market expanding from the low billions in 2020 to an estimated USD 4.7 billion in 2025, with a projected upward trend to roughly USD 6.12 billion by 2032. The forecast period (2026–2032) is characterized by a compound annual growth rate (CAGR) of 3.85%. This mid-single-digit growth masks important inflection points: pockets of accelerated demand tied to deepwater and offshore chemical injection requirements, and episodic investment driven by water‑treatment and industrial process modernization programs.
Precious Metal Accounts Market
Importantly, the market is concentrated: the top three suppliers capture a meaningful share, and the top five command more than half of market revenues. That concentration has strategic implications for procurement leverage, qualification timelines, and M&A playbooks in 2026 and beyond.
Worldwide Coin-operated Commercial Laundry Market
Why 2026 is a pivotal year for decisions
- CapEx timing vs. operating risk: Many operators will face the classic CAPEX-versus-OPEX decision—invest today in higher‑specification, digitally enabled metering systems that reduce leak risk and maintenance burden, or continue with lower‑cost units and accept higher operational surveillance costs. Our scenarios quantify break‑even horizons for each approach under plausible oil price and service‑cost trajectories.
- Supplier selection under consolidation: With CR3 and CR5 indicating a moderately concentrated landscape, 2026 procurement strategies must weigh supplier stability, aftermarket coverage, and integration of engineered packages versus component‑level sourcing to preserve negotiating flexibility.
- Standards and compliance: API 675 remains the definitive specification for reciprocating positive‑displacement metering pumps in petroleum and petrochemical services. Tender and specification teams that align procurement language with API 675—and understand where bespoke engineering is justified—reduce specification risk and life‑cycle costs.
- Raw material volatility: Fluctuations in stainless steel and specialty alloys will affect margins and lead times. Hedging, multi‑sourcing, or strategic inventory moves are nontrivial decisions for 2026 procurement calendars.
What the PW Consulting report delivers—practical, decision‑grade content
This study is designed to be operationally useful, not just descriptive. Key deliverables include:
- Top‑level market sizing and seven‑year forecast with scenario bands that reflect differentiated demand drivers (offshore deepwater activity, water treatment modernization, chemical processing expansions).
- Vendor benchmarking that goes beyond product specs to assess API compliance, field reliability, aftermarket footprint, digital connectivity, and skid integration capability.
- Procurement playbooks with tender language templates, qualification checklists, and a risk‑weighted supplier short‑list methodology that procurement and engineering teams can use immediately.
- Technology and product roadmaps highlighting where diaphragm, piston, peristaltic and hybrid solutions are most appropriate—paired with OPEX modeling and lifecycle cost calculators.
- Supply‑chain stress tests and mitigation options to manage raw‑material and lead‑time volatility, including alternative materials, modular designs, and local assembly strategies.
- M&A and partnership screeners that identify acquisition targets and strategic alliance opportunities for component manufacturers, skid integrators, and valve specialists.
Competitive landscape—who matters and why
The vendor environment blends legacy pump specialists, engineered‑package integrators, and niche valve innovators. Our competitive analysis synthesizes company‑level strengths relevant to 2026 decisions:
- LEWA GmbH — Renowned for hermetically sealed diaphragm pumps and API‑compliant chemical injection packages. Strong in high‑pressure, critical applications where leak containment and reliability are non‑negotiable.
- IDEX Corporation (Pulsafeeder, Milton Roy, LMI) — A diversified portfolio across hydraulic diaphragm, solenoid‑driven, and mechanical metering technologies. Valuable where organizations prioritize breadth of solution and global aftermarket coverage.
- SPX Flow (Bran+Luebbe) — Excels in custom chemical injection systems for offshore applications, including double‑diaphragm designs that target high accuracy under cyclic loads.
- ProMinent GmbH — Notable for rapid product innovation and digital connectivity. Its recent beta/X launch signals the industry’s move toward lower‑footprint, connected diaphragm pumps with expanded control features.
- SkoFlo Industries — A specialist in pressure‑independent chemical injection metering valves for surface and subsea use—an increasingly important capability as field architectures consolidate pumps and distribute dosing points.
- Sidewinder, CheckPoint, Bruin Pumps — These suppliers are differentiated by ruggedized designs, solar and pneumatic offerings, and operational focus on oilfield chemicals such as methanol and corrosion inhibitors.
- Neptune (PSG) and Iwaki America — Strong positions in water treatment and industrial dosing, where precision at micro‑to‑mid flows and serviceability are priority purchase drivers.
Recent product introductions—from hydraulic API‑675 hydraulic diaphragm models to next‑generation solenoid and electronic drives—underscore supplier efforts to combine accuracy, reliability and connectivity. Our report maps these introductions to likely adoption pathways and total cost implications for field operators.
Regulation, materials, and deployment dynamics
Three external forces will shape vendor and buyer behavior in 2026:
- Standards enforcement: API 675 continues to set the bar for critical hydrocarbon applications. Tender committees that conflate “API‑style” features with true API 675 compliance expose projects to specification and warranty risk.
- Materials and cost volatility: Stainless steel and specialty alloy price swings require procurement to embed price adjustment mechanisms or design flexibilities into long‑lead contracts.
- Field architectures: Increasing deployment of pressure‑independent valves and multi‑point injection strategies will influence the balance between centralized high‑pressure pumps and distributed pumping concepts—affecting OPEX profiles and control complexity.
Actionable recommendations for C‑suite and procurement leaders in 2026
- Prioritize total‑cost‑of‑ownership analysis when approving CapEx: quantify leak‑risk, maintenance intervals, and digital monitoring ROI rather than defaulting to lowest initial cost.
- Implement a two‑track supplier strategy: maintain relationships with tier‑one API‑compliant vendors for critical duty, while qualifying regional specialists and valve innovators for lower‑risk or distributed injection points.
- Embed material‑price escalation clauses and dual‑sourcing for long‑lead components to blunt the impacts of alloy price swings.
- Accelerate pilot programs for connected metering assets that feed predictive‑maintenance outputs into existing asset‑management systems; validate expected OPEX reductions before fleet‑wide rollouts.
- Use the market concentration profile to time negotiations and partnerships—early 2026 may present a window to secure aftermarket commitments and favorable lead times before anticipated capacity investments among leading vendors.
Why PW Consulting’s study is the tactical tool your team needs
Beyond headline numbers, the report provides the blueprints procurement and engineering teams can use immediately: editable tender text, supplier‑scoring matrices, lifecycle cost models, and scenario playbooks that map supplier choice to field outcomes. We intentionally withhold granular segment tables from this press release to preserve the utility of the primary deliverable: a compact, executable intelligence product that guides supplier selection, risk mitigation and investment timing for 2026.
Next steps
Executives and technical leaders preparing budgets and supplier strategies for 2026 should review the full report to access the detailed segmentation, supplier scorecards, and downloadable procurement tools. PW Consulting also offers tailored briefings and live workshops to translate report findings into a 90‑day action plan for procurement, reliability engineering, and business development teams.
To obtain the complete study and arrange a strategy session, please visit the PW Consulting report page for Chemical Injection Metering Pumps & Valves Market. The full report contains the proprietary segment detail, company scorecards, and scenario models referenced here—essential inputs for any organization seeking to convert 2026 decisions into measurable performance gains.
For detailed analysis of this topic, please visit the official page: Chemical Injection Metering Pumps & Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Decorative Lighting Market to Expand at 5.45% CAGR, Reaching USD 25,945.6 Million by 2032
By pmarketresearch, 2026-08-18
Commercial Decorative Lighting Market Outlook 2026: Strategic Imperatives for Corporate Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I am pleased to release a strategic briefing based on our forthcoming Commercial Decorative Lighting Market report (base year 2025). The market reached approximately USD 17.9 billion in 2025 and — under our central forecast — is set to grow at a compound annual growth rate (CAGR) of 5.45% over the coming seven years, approaching roughly USD 25.9 billion by 2032. This release serves as a high-value “preview trailer”: it demonstrates the analytical depth and actionable framing that underpin the full report while deliberately withholding the granular subsegment matrices reserved for subscribers and clients.
USB Baby Monitor Market
2026: An Operational Inflection Point, Not Just Another Forecast Year
For corporate decision-makers — whether manufacturers, specification-led distributors, large-scale real estate owners, or private equity investors — 2026 represents a moment to translate multi-year trends into executable plans. The market dynamics that accelerated through 2020–2025 (a steady expansion from the pandemic trough and through recovery-led capital expenditure cycles) are now intersecting with three converging forces that will determine winners and losers in the decorative lighting space:
Open Wound Transformers Market
- Supply-side cost pressure. Aluminum and copper price volatility in 2025 and elevated tariffs on steel and aluminum imports have materially raised manufacturing cost bases. Our assessment finds these raw material dynamics amplify margin pressure for midstream OEMs and intensify the need for hedging, design-for-cost, and localized sourcing strategies.
- Policy and energy efficiency headwinds/tailwinds. Tightening codes and sustainability procurement criteria favor energy-efficient luminaires and connected lighting systems but also impose compliance and re-certification costs on incumbents with legacy portfolios.
- Technology commoditization vs. differentiation. LED efficiency gains and standardized connectivity stacks are compressing product differentiation in the commodity tiers, accelerating competition on design, specification services, and integrated solutions (lighting-as-a-service, controls, and software-enabled maintenance).
What Our Report Delivers — Practical, Transaction-Ready Intelligence
Clients tell us they need three types of outputs from a market report: accurate sizing and credible scenarios; competitor and channel intelligence to inform tactical moves; and executable playbooks with quantified trade-offs. The PW Consulting Commercial Decorative Lighting report provides all three through a mix of quantitative models and practitioner-oriented tools, including:
Superimposed Direct Acting Pressure Reducing Valve Market
- Market sizing and scenario forecasts (2026–2032) built from a transparent, bottom-up SKU/shipments model reconciled with macro demand drivers and validation from primary interviews.
- Cost-to-produce models that isolate the impact of raw material inflation, tariff pass-through, and vertical integration assumptions on EBITDA margins for typical OEM archetypes.
- Go-to-market and channel playbooks that score distribution partners, specification reach, and installer networks; these include negotiation levers and SKU rationalization templates used in recent client engagements.
- Product and innovation roadmaps highlighting where premiumization (materials, finish, optics) and embedded services (controls, warranty analytics, energy management) can create defensible NRR (net recurring revenue) streams.
- M&A and partnership screening tools with valuation sensitivity tests based on revenue synergies, cost synergies, and integration risk factors—tailored for mid-market consolidators and strategic corporate buyers.
- Procurement and tender optimization frameworks for real estate portfolios and hospitality chains, including lifecycle cost benchmarks and retrofit-first vs. new-build decision matrices.
Competitive Landscape: Who to Watch (and Why)
The market exhibits a measurable degree of concentration: the top three companies account for a meaningful share of the market, and the five largest players collectively control just over half of overall revenue. This structure creates a two-speed competitive environment — scale and specification reach matter, but so do design-led differentiation and channel intimacy.
- Acuity Brands Inc. (HQ: Atlanta) boasts a broad commercial portfolio that spans indoor and outdoor decorative luminaires. Their scale and channel relationships in North America make them a go-to partner for large commercial projects. Expect continued focus on systems integration and portfolio rationalization to defend margins under material-cost inflation.
- Signify (Philips Lighting) (HQ: Eindhoven) remains the global technology leader, particularly strong in connected lighting systems and energy-efficient professional solutions. Their capability to deploy end-to-end solutions (hardware, software, services) positions them to capture specification-driven segments where lifecycle savings are paramount.
- WAC Lighting (HQ: Port Washington) competes on design and specification, with a product set that resonates in hospitality and premium retail. Smaller, design-focused players like WAC can command price premiums but must scale service offerings to compete in large tenders.
- Hubbell Incorporated (HQ: Shelton) offers an industrial-to-commercial bridge with a resilient installed-base business. Their advantage is portfolio breadth across environments and a strong reputation in infrastructure-grade applications.
- Amerlux LLC (HQ: Fairfield) targets higher-end architectural and decorative segments where finish, customization, and specification support drive purchase decisions. These segments are less price-elastic but require deeper service and design resources.
- Cooper Lighting Solutions (HQ: Peachtree City) emphasizes innovation, including early commercial adoption of techniques like additive manufacturing for niche luminaires. Their R&D orientation allows tactical wins in retrofit and specialty projects.
Recent industry activity underscores these dynamics: new product releases and trade showcases through 2025–2026 highlight a pivot toward contemporary aesthetics married with higher-performing LED engines, while smaller suppliers continue to innovate in niche decorative categories. These developments feed both consolidation motives and buyer demand for differentiated offers.
Strategic Playbook for 2026 Decision-Makers
Based on our scenario work and interviews with C-suite and procurement leaders, the following priorities should inform 2026 capital and operational plans:
- Hedge and redesign for materials risk. Apply value-engineering to fixtures, standardize modular platforms, and secure multi-year supply agreements for critical inputs where possible.
- Move up the value stack. Monetize installation and lifecycle services—controls, commissioning, warranty analytics—rather than competing purely on hardware margins.
- Win specification: invest in design consultancy, photometric modeling tools, and fast-response sample services to be first in spec and last out on tender lists.
- Pursue targeted M&A and strategic partnerships. Buyers should prioritize targets that deliver route-to-market expansion, specification footprints, or proprietary finishing/optical IP rather than only revenue scale.
- Operationalize sustainability claims. Certification, circularity programs, and transparent LCA calculations will increasingly differentiate bids in large commercial tenders.
Risks, Upside, and Execution Sensitivities
Our forecast path is subject to clear sensitivities. The principal downside risks include sustained raw-material inflation without corresponding price realization, abrupt regulatory changes that increase compliance costs, and disruption in global logistics. Upside scenarios arise from faster-than-expected adoption of connected lighting services, accelerated retrofit cycles among hospitality and retail portfolios, and successful premiumization by differentiated suppliers.
To operationalize these sensitivities, the full report includes scenario trees, probability-weighted NPV impacts on representative business models, and playbooks that map triggers to pre-defined tactical responses (e.g., when to lock forward prices, when to pull forward R&D, or when to accelerate channel consolidation).
Why PW Consulting’s Analysis Matters to Your 2026 Plans
Our methodology blends rigorous bottom-up market modelling with qualitative validation via dozens of primary interviews across procurement, design, distribution, and manufacturer leadership. The report couples that foundation with executable frameworks—supplier scorecards, ROI calculators, specification penetration metrics, and deal-screening tools—that clients deploy directly in commercial planning cycles.
This briefing intentionally omits the line-by-line subsegment revenue tables, regional pairings, and application breakdowns that procurement, M&A, and product strategy teams require for transactional decisions. Those detailed matrices, interactive dashboards, and supplier-specific scorecards are available in the full PW Consulting report and client portal, where you can also access our configurable financial models and scenario engines.
To request the full report, schedule a briefing with our advisory team, or license the dataset and interactive models, please visit our website. For executives preparing 2026 budgets and strategic roadmaps, the intelligence in this report will materially shorten decision cycles and materially increase confidence in capital allocation decisions.
For detailed analysis of this topic, please visit the official page: Commercial Decorative Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AGV Charging System Market to Grow from USD 612.75 Million in 2025 to USD 1,083.65 Million by 2032, Posting an 8.45% CAGR (2026–2032)
By pmarketresearch, 2026-08-18
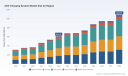
AGV Charging System Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s new market research brief on the AGV Charging System Market anchors strategic planning for enterprises facing a pivotal 2026. Built on a five‑year historical baseline (2020–2025) and a seven‑year forecast window (2026–2032), the study combines hard market sizing, supplier benchmarking, regulatory mapping, and executable commercial frameworks to convert charging‑architecture choices into measurable operational and financial outcomes.
Worldwide Equestrian Riding Apparel Market
Executive snapshot: market momentum and concentration
Our analysis records a rapid expansion of the AGV charging ecosystem over the past half‑decade — the market grew from roughly USD 312 million in 2020 to about USD 613 million in 2025. Under conservative and upside scenarios, we forecast ongoing growth through 2032 that pushes the market past the USD 1 billion threshold, underpinned by a compound annual growth rate of 8.45% across the forecast period. Market share concentration is meaningful but not overwhelming: the top three suppliers control a material share of the industry, while the top five command just over half the market, leaving room for focused challengers and niche innovators.
Worldwide Flavored Pet Medication Market
Why 2026 is a make‑or‑break year for AGV charging strategies
- Regulatory acceleration: Policy drivers—most notably decarbonization commitments in major markets and tighter industrial sustainability targets—are pushing warehouse and intralogistics operators to prioritize energy‑efficient, low‑emission intralogistics architectures. Compliance timelines for these policies make mid‑decade procurement and deployment decisions critical.
- Standards and safety: Conformance to emerging machine safety standards for autonomous guided vehicles is becoming a procurement gate. Integrated charging systems that are compliant with the latest ISO guidance reduce certification friction and accelerate time‑to‑value for automation projects.
- Battery & charging tech inflection: Continued adoption of lithium‑ion chemistry and improvements in cell and BMS designs are enabling faster charge profiles (typical operational targets around 1C, with surge strategies up to roughly 3C). These shifts change tradeoffs between battery capacity, downtime, and charging architecture.
- Operational economics: As throughput demands tighten and labor dynamics remain uncertain, the marginal value of reduced AGV downtime — whether via opportunity charging, fast conductive contacts, or mature inductive systems — becomes a decisive factor in ROI models for 2026 planning cycles.
What PW Consulting’s report delivers to support 2026 decisions
- Robust market sizing and scenario modelling (historical 2020–2025; forecast 2026–2032) with sensitivity runs tailored to energy price, CAPEX/OPEX, and adoption curves.
- Vendor benchmarking matrix: technology performance, integration complexity, field reliability, service footprint, and commercial models (CAPEX vs. recurring service contracts).
- Modular Total Cost of Ownership (TCO) toolkit for AGV charging: site modeling templates, energy consumption profiles, maintenance schedules, and payback analysis tailored to warehouse and manufacturing workflows.
- Procurement and contract playbook: technical checklists, acceptance testing protocols, SLAs for uptime and maintenance, and negotiation levers to align vendor risk with operator outcomes.
- Deployment roadmaps: phased rollout plans, interoperability strategies for mixed‑fleet environments (AGVs and AMRs), and retrofit vs. greenfield decision frameworks.
- Supply chain & resilience heatmap highlighting supplier concentration risks, critical component exposure, and mitigation strategies for raw material and component volatility.
Competitive landscape — who matters and what they mean for your strategy
The competitive field contains a mix of specialist charging vendors, power electronics groups, and integrators that embed charging into broader material‑handling solutions. Understanding their positioning is essential when deciding whether to buy, partner, or develop in‑house capabilities.
Worldwide Myocardium Detection Kit Market
- Wiferion (Epiroc) — Germany: Leader in inductive wireless charging platforms that enable contactless opportunity charging without mechanical wear. Their offerings are particularly attractive where uptime and low maintenance are paramount. For 2026, consider their solutions when designing operations that favor continuous fleet availability and minimal manual intervention.
- VAHLE GmbH — Germany: Established provider of conductive charging contacts and shuttle chargers for intralogistics. VAHLE’s strengths lie in high‑current conductive solutions and custom integration services, making them a logical choice for high‑throughput facilities where fast recharge cycles are prioritized.
- Delta Electronics — Taiwan: Broad portfolio across conductive and wireless options and deep deployment scale in industrial environments. Delta’s commercial strength is the combination of product breadth and global manufacturing footprint—useful when procurement resilience and supplier reach are key selection criteria.
- Micropower Group — Sweden: Focused on high‑frequency chargers up to 100 kW, offering flexibility in onboard and stationary deployments. Consider them for high‑power use cases and where compatibility with diverse battery chemistries is required.
- EnerSys — United States: Integrator of battery and charging solutions with a reputation for reliable power delivery in industrial automation. Best evaluated in scenarios requiring deep battery‑vendor coordination and lifecycle management.
- Daihen & Daifuku — Japan: Their combined capabilities cover precise docking, conductive and inductive systems, and full automation integration — attractive for OEMs and integrators seeking vertically integrated solutions.
- B&PLUS, Guangdong Titans, Vicor Power — Regional specialists: Offer targeted innovations in non‑contact power transfer, autonomous docking, and power conversion modules. These firms are worth shortlisting when local service coverage, customization, or power‑electronics innovation are decisive factors.
Recent market signals illustrate active product and ecosystem development: an inductive system won industry recognition for in‑process charging technology in 2025; a major electronics group showcased extensive deployed vehicle counts at a prominent logistics trade fair in early 2026; and infrastructure suppliers introduced high‑voltage connector and microgrid innovations to support next‑generation fast charging. Together, these developments reflect both product maturity and accelerating commercialization efforts.
Technology trajectories and application implications
- Contact vs. wireless: Conductive contact solutions continue to offer cost‑effective, high‑efficiency charging for continuous, high‑duty applications. Wireless inductive charging is rapidly improving in efficiency and reliability and is increasingly selected for operations prioritizing maintenance reduction and safety. Opportunity charging approaches are gaining traction where operational profiles favor brief, frequent top‑ups rather than deep cycle replenishment.
- Charging power and battery strategy: The interplay of battery sizing and allowable charge rates (practical operational targets often center on 1C with transient strategies up to ~3C) is now a core determinant of fleet economics. Lower battery capacity plus more frequent charging can reduce upfront cost but demands robust charging infrastructure and scheduling controls.
- Integration and digital management: Charging systems are becoming nodes in the warehouse energy ecosystem — integrated with fleet management software, energy management systems, and microgrids to enable peak shaving, demand response, and predictive maintenance.
Decision frameworks for 2026 procurement and roadmap alignment
- Define operational anchors: Start with throughput, acceptable downtime, lifecycle replacement intervals, and energy procurement profile. Map these anchors to charging architectures—conductive, inductive, or hybrid—and quantify the impact on fleet sizing and scheduling.
- Use modular TCO models: Separate CAPEX for infrastructure from recurring costs (energy, service, replacements) and overlay reliability scenarios. Include sensitivity to energy price volatility and battery cycle life assumptions.
- Prioritize interoperability: For mixed fleets or phased rollouts, insist on open communication standards and documented integration APIs to avoid vendor lock‑in and expensive retrofits.
- Mitigate supplier risk: Assess regional service footprints, spare parts lead times, and critical component exposures. Where necessary, design dual‑sourcing or local spares strategies into contracts.
- Plan for standards compliance: Early alignment with safety and interoperability standards reduces time‑to‑deployment and avoids costly rework as ISO and regional requirements evolve.
Conclusion: strategic value of the report for 2026
For executives and operations leaders preparing capital and technology roadmaps in 2026, PW Consulting’s AGV Charging System Market report is built to convert uncertainty into executable decisions. The combination of verified market sizing, supplier benchmarking, TCO tools, and deployment playbooks accelerates procurement cycles and reduces integration risk. We intentionally present high‑confidence macro metrics here to orient strategy — the full report contains the granular segmentation, vendor scorecards, scenario outputs, and downloadable modeling templates that will enable precise investment decisions and contract negotiations.
To access the complete dataset, vendor scorecards, and the deployment toolkit that underpins the analysis summarized here, please download the full PW Consulting report and supporting models. The detailed annexes are designed for procurement teams, technology planners, and C‑suite leaders who must translate 2026 choices into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: AGV Charging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Air Intake Resonator Market to Reach USD 1,291.2 Million by 2032, Growing at a 6.85% CAGR
By pmarketresearch, 2026-08-18
Air Intake Resonator Market: A Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases an executive industry briefing that distills the strategic implications of our full Air Intake Resonator Market study. As OEMs, tier suppliers, aftermarket specialists and private equity investors set budgets and roadmaps for 2026, this briefing highlights the forces reshaping the resonator value chain, the investment levers that matter, and the practical next steps to convert macro trends into defensible, near-term competitive advantage.
Worldwide Enterprise Database Management Suite Market
Executive snapshot
The global air intake resonator market has evolved from a niche noise-control component into a system-level design consideration embedded in air management strategies across powertrains. Our analysis shows a sustained expansion trajectory: the market moved from a mid-single‑hundreds USD million base in 2020 to a stronger position by 2025, and is projected to grow at a compound annual growth rate (CAGR) of 6.85% over the 2026–2032 forecast period. By 2032 the market is on course to be materially larger than in 2025, reflecting an intersection of regulatory pressure, rising demand for NVH-optimised combustion systems, and aftermarket performance trends.
Worldwide Colored Glass Bead Market
Why 2026 is a strategic inflection point
- Regulatory pressure (for example, tightening combustion emissions standards) makes air intake performance a lever for both compliance and optimization. Investments made in 2026 will influence vehicle architectures and supplier relationships for the remainder of the decade.
- Raw material and thermal-design tradeoffs are converging with manufacturing-tech advancements. These dynamics change cost curves and determine which resonator technologies are scalable for different vehicle architectures.
- Competitive consolidation and vertical integration are accelerating. Our concentration metrics indicate that a handful of established players exert meaningful influence, but room remains for specialization, especially where thermal resilience and integrated system design matter.
Market trajectory and what it means for budgets
The market’s historical progression underscores recovery and expansion phases that have been reshaping supplier economics. Between 2020 and 2025 the sector expanded notably, and our forecast through 2032 shows continued growth driven by OEM platform refresh cycles, aftermarket demand for performance and acoustic tuning, and regulatory-driven reinvestment in intake systems. For 2026 planners, two budgetary implications follow:
Forestry Seeds Market
- Capex and R&D allocation should prioritize integrated air management — not isolated resonator parts. Investments in design tools, prototype validation for NVH and flow, and materials testing deliver outsized returns compared with incremental part-only upgrades.
- Sourcing strategies must account for material- and manufacturing-driven cost volatility. Suppliers that can offer validated material substitutions or hybrid component architectures mitigate procurement risk while preserving performance thresholds.
Materials and design: the trade-offs that matter
Material selection is a practical battleground where design objectives (noise attenuation, thermal endurance, weight, and cost) compete. Two material realities deserve special attention in 2026 planning:
- Polypropylene (PP) remains attractive where cost and lightweighting dominate. Its lower material cost—on the order of double-digit percentage savings versus higher-performance polymers—supports volume applications where intake temperatures remain moderate. However, PP’s thermal ceiling constrains its use in turbocharged or high-underhood temperature environments.
- Glass-fiber-reinforced polyamides (PA6/PA66) retain preference for premium, turbocharged and high-thermal-load applications because of their superior thermal resistance and dimensional stability. While costlier, they lower risk in high-temperature service and permit more compact geometries and integrated assemblies.
The practical implication: companies that can validate material performance with costed manufacturing routes — and demonstrate NVH and durability equivalence in system-level tests — will win specification slots as OEMs rationalize architectures under emissions and acoustic constraints.
Competitive landscape: established leaders and emergent opportunities
The market exhibits a mixed structure: sizeable global players with system-integration expertise coexist with specialized aftermarket and component suppliers. Our industry mapping highlights incumbent strengths and adjacent opportunities:
- MANN+HUMMEL (Ludwigsburg, Germany) — a filtration and systems leader offering integrated air cleaner housings and resonators; strong OEM relationships and systems know-how are core advantages.
- Röchling Automotive (Mannheim, Germany) — specializes in high-frequency resonators and integrated duct systems; their capability in acoustics engineering supports premium and performance applications.
- Toyoda Gosei (Inazawa, Japan) — provides hose and duct solutions with noise-absorbing features tailored to engine efficiency and intake noise reduction.
- Magna International (Aurora, Canada) — leverages broad vehicle systems engineering to offer resonators as part of larger powertrain and thermal management solutions.
- K&N Engineering (Riverside, USA) — an aftermarket performance player introducing NextGen intake systems that influence aftermarket demand and provide insights into consumer-driven acoustic and airflow preferences.
Recent product activity in the aftermarket (for example, cold-air intake launches and performance-focused systems) signals a continuing two-track market: OEM-driven, regulation-sensitive systems on one side, and performance-led aftermarket innovations on the other. Market concentration indicators show that the top players capture a disproportionate share of value, but specialized suppliers with acoustics, materials, or integration IP can still carve defensible niches.
Practical content in the PW Consulting report
Our full study is intentionally operational: beyond forecasts it supplies decision-ready assets that executives will use in 2026 planning cycles.
- Modular strategic playbooks for OEMs and tier suppliers — including product roadmaps, specification prioritization matrices, and supplier selection criteria.
- Cost-to-serve and materials-cost modelling templates with sensitivity analysis for PP versus PA architectures and reinforced material formulations.
- Manufacturing economics assessment — tooling CAPEX profiles, cycle-time benchmarks, and scale-entry thresholds for injection-moulded and hybrid assemblies.
- Regulatory scenario analyses — Euro 7 and comparable regimes modelled for how intake-system performance affects combustion optimization and emissions compliance, under multiple vehicle mileage and duty-cycle assumptions.
- Competitive intelligence dossiers — executive profiles, recent moves, technology patents and partnership heatmaps for the leading suppliers and targeted challengers.
- M&A and partnership playbook — a prioritized shortlist of targets and capability gaps, with valuation multipliers and integration risk checklists tailored to resonator and intake-system assets.
- Action templates — 90/180/365 day tactical plans for procurement, validation, and go-to-market for aftermarket channels.
How decision-makers should use this intelligence in 2026
Whether you are an OEM engineering director, a tier supplier head of strategy, or an investor assessing platform plays, the report supports three clear 2026 use cases:
- Portfolio prioritization: allocate R&D and platform capital to intake-system architectures where material and acoustic advantages yield the highest impact on emissions, fuel/energy efficiency, and brand-differentiated NVH.
- Sourcing and supplier governance: apply our materials and cost models to renegotiate supply agreements, evaluate material-substitution pilots, and set procurement guardrails around thermal-performance confidence levels.
- M&A and partnership targeting: use the deal playbook to identify bolt-on capabilities (acoustic modelling, multi-material assembly, aftermarket distribution) and accelerate time-to-market through alliances or strategic acquisitions.
Risk factors and mitigation levers
Executives must weigh three principal risks and the mitigating actions we recommend:
- Raw material volatility and substitution risk — mitigate with dual-sourcing strategies and qualification of hybrid-material designs backed by accelerated thermal/aging validation.
- Regulatory uncertainty — hedge with modular designs that allow incremental performance upgrades without full-platform redesigns; prioritize systems that offer measurable combustion benefits.
- Competitive displacement from vertically integrated suppliers — respond by deepening system-integration capabilities or locking strategic long-term supplier agreements tied to performance KPIs.
Conclusion and recommended next steps
Our analysis shows that air intake resonators are no longer peripheral components: they are leverage points for emissions strategy, acoustic differentiation, and cost optimization. The market’s trajectory through 2032—underpinned by a 6.85% CAGR over the forecast window—creates both pressure and opportunity. For 2026, the decisive actions are clear: reallocate R&D toward system-level validation, redesign procurement to capture material-driven cost and performance upside, and use targeted partnerships or M&A to acquire missing acoustics or materials expertise.
PW Consulting’s full Air Intake Resonator Market report provides the datasets, proprietary models and tactical templates to implement these recommendations. To access the complete forecasts, segment-level analytics, supplier matrices and actionable playbooks, visit the PW Consulting report landing page and download the executive package. The full report preserves the detailed regional and application splits, scenario tables, and validated supplier profiles that you will need to finalize 2026 budgets and strategic priorities.
For detailed analysis of this topic, please visit the official page: Air Intake Resonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com