

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
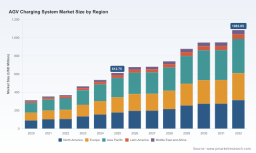
PW Consulting: AGV Charging System Market to Grow from USD 612.75 Million in 2025 to USD 1,083.65 Million by 2032, Posting an 8.45% CAGR (2026–2032)

AGV Charging System Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s new market research brief on the AGV Charging System Market anchors strategic planning for enterprises facing a pivotal 2026. Built on a five‑year historical baseline (2020–2025) and a seven‑year forecast window (2026–2032), the study combines hard market sizing, supplier benchmarking, regulatory mapping, and executable commercial frameworks to convert charging‑architecture choices into measurable operational and financial outcomes.
Worldwide Equestrian Riding Apparel Market
Executive snapshot: market momentum and concentration
Our analysis records a rapid expansion of the AGV charging ecosystem over the past half‑decade — the market grew from roughly USD 312 million in 2020 to about USD 613 million in 2025. Under conservative and upside scenarios, we forecast ongoing growth through 2032 that pushes the market past the USD 1 billion threshold, underpinned by a compound annual growth rate of 8.45% across the forecast period. Market share concentration is meaningful but not overwhelming: the top three suppliers control a material share of the industry, while the top five command just over half the market, leaving room for focused challengers and niche innovators.
Worldwide Flavored Pet Medication Market
Why 2026 is a make‑or‑break year for AGV charging strategies
- Regulatory acceleration: Policy drivers—most notably decarbonization commitments in major markets and tighter industrial sustainability targets—are pushing warehouse and intralogistics operators to prioritize energy‑efficient, low‑emission intralogistics architectures. Compliance timelines for these policies make mid‑decade procurement and deployment decisions critical.
- Standards and safety: Conformance to emerging machine safety standards for autonomous guided vehicles is becoming a procurement gate. Integrated charging systems that are compliant with the latest ISO guidance reduce certification friction and accelerate time‑to‑value for automation projects.
- Battery & charging tech inflection: Continued adoption of lithium‑ion chemistry and improvements in cell and BMS designs are enabling faster charge profiles (typical operational targets around 1C, with surge strategies up to roughly 3C). These shifts change tradeoffs between battery capacity, downtime, and charging architecture.
- Operational economics: As throughput demands tighten and labor dynamics remain uncertain, the marginal value of reduced AGV downtime — whether via opportunity charging, fast conductive contacts, or mature inductive systems — becomes a decisive factor in ROI models for 2026 planning cycles.
What PW Consulting’s report delivers to support 2026 decisions
- Robust market sizing and scenario modelling (historical 2020–2025; forecast 2026–2032) with sensitivity runs tailored to energy price, CAPEX/OPEX, and adoption curves.
- Vendor benchmarking matrix: technology performance, integration complexity, field reliability, service footprint, and commercial models (CAPEX vs. recurring service contracts).
- Modular Total Cost of Ownership (TCO) toolkit for AGV charging: site modeling templates, energy consumption profiles, maintenance schedules, and payback analysis tailored to warehouse and manufacturing workflows.
- Procurement and contract playbook: technical checklists, acceptance testing protocols, SLAs for uptime and maintenance, and negotiation levers to align vendor risk with operator outcomes.
- Deployment roadmaps: phased rollout plans, interoperability strategies for mixed‑fleet environments (AGVs and AMRs), and retrofit vs. greenfield decision frameworks.
- Supply chain & resilience heatmap highlighting supplier concentration risks, critical component exposure, and mitigation strategies for raw material and component volatility.
Competitive landscape — who matters and what they mean for your strategy
The competitive field contains a mix of specialist charging vendors, power electronics groups, and integrators that embed charging into broader material‑handling solutions. Understanding their positioning is essential when deciding whether to buy, partner, or develop in‑house capabilities.
Worldwide Myocardium Detection Kit Market
- Wiferion (Epiroc) — Germany: Leader in inductive wireless charging platforms that enable contactless opportunity charging without mechanical wear. Their offerings are particularly attractive where uptime and low maintenance are paramount. For 2026, consider their solutions when designing operations that favor continuous fleet availability and minimal manual intervention.
- VAHLE GmbH — Germany: Established provider of conductive charging contacts and shuttle chargers for intralogistics. VAHLE’s strengths lie in high‑current conductive solutions and custom integration services, making them a logical choice for high‑throughput facilities where fast recharge cycles are prioritized.
- Delta Electronics — Taiwan: Broad portfolio across conductive and wireless options and deep deployment scale in industrial environments. Delta’s commercial strength is the combination of product breadth and global manufacturing footprint—useful when procurement resilience and supplier reach are key selection criteria.
- Micropower Group — Sweden: Focused on high‑frequency chargers up to 100 kW, offering flexibility in onboard and stationary deployments. Consider them for high‑power use cases and where compatibility with diverse battery chemistries is required.
- EnerSys — United States: Integrator of battery and charging solutions with a reputation for reliable power delivery in industrial automation. Best evaluated in scenarios requiring deep battery‑vendor coordination and lifecycle management.
- Daihen & Daifuku — Japan: Their combined capabilities cover precise docking, conductive and inductive systems, and full automation integration — attractive for OEMs and integrators seeking vertically integrated solutions.
- B&PLUS, Guangdong Titans, Vicor Power — Regional specialists: Offer targeted innovations in non‑contact power transfer, autonomous docking, and power conversion modules. These firms are worth shortlisting when local service coverage, customization, or power‑electronics innovation are decisive factors.
Recent market signals illustrate active product and ecosystem development: an inductive system won industry recognition for in‑process charging technology in 2025; a major electronics group showcased extensive deployed vehicle counts at a prominent logistics trade fair in early 2026; and infrastructure suppliers introduced high‑voltage connector and microgrid innovations to support next‑generation fast charging. Together, these developments reflect both product maturity and accelerating commercialization efforts.
Technology trajectories and application implications
- Contact vs. wireless: Conductive contact solutions continue to offer cost‑effective, high‑efficiency charging for continuous, high‑duty applications. Wireless inductive charging is rapidly improving in efficiency and reliability and is increasingly selected for operations prioritizing maintenance reduction and safety. Opportunity charging approaches are gaining traction where operational profiles favor brief, frequent top‑ups rather than deep cycle replenishment.
- Charging power and battery strategy: The interplay of battery sizing and allowable charge rates (practical operational targets often center on 1C with transient strategies up to ~3C) is now a core determinant of fleet economics. Lower battery capacity plus more frequent charging can reduce upfront cost but demands robust charging infrastructure and scheduling controls.
- Integration and digital management: Charging systems are becoming nodes in the warehouse energy ecosystem — integrated with fleet management software, energy management systems, and microgrids to enable peak shaving, demand response, and predictive maintenance.
Decision frameworks for 2026 procurement and roadmap alignment
- Define operational anchors: Start with throughput, acceptable downtime, lifecycle replacement intervals, and energy procurement profile. Map these anchors to charging architectures—conductive, inductive, or hybrid—and quantify the impact on fleet sizing and scheduling.
- Use modular TCO models: Separate CAPEX for infrastructure from recurring costs (energy, service, replacements) and overlay reliability scenarios. Include sensitivity to energy price volatility and battery cycle life assumptions.
- Prioritize interoperability: For mixed fleets or phased rollouts, insist on open communication standards and documented integration APIs to avoid vendor lock‑in and expensive retrofits.
- Mitigate supplier risk: Assess regional service footprints, spare parts lead times, and critical component exposures. Where necessary, design dual‑sourcing or local spares strategies into contracts.
- Plan for standards compliance: Early alignment with safety and interoperability standards reduces time‑to‑deployment and avoids costly rework as ISO and regional requirements evolve.
Conclusion: strategic value of the report for 2026
For executives and operations leaders preparing capital and technology roadmaps in 2026, PW Consulting’s AGV Charging System Market report is built to convert uncertainty into executable decisions. The combination of verified market sizing, supplier benchmarking, TCO tools, and deployment playbooks accelerates procurement cycles and reduces integration risk. We intentionally present high‑confidence macro metrics here to orient strategy — the full report contains the granular segmentation, vendor scorecards, scenario outputs, and downloadable modeling templates that will enable precise investment decisions and contract negotiations.
To access the complete dataset, vendor scorecards, and the deployment toolkit that underpins the analysis summarized here, please download the full PW Consulting report and supporting models. The detailed annexes are designed for procurement teams, technology planners, and C‑suite leaders who must translate 2026 choices into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: AGV Charging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com