

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Nuclear Valve Market Hits $2,143.69M in 2025, Projected 6.1% CAGR Through 2032

Strategic Imperatives in the Nuclear Valves Market: A 2026 Decision-Maker's Guide
The nuclear energy sector stands at a critical inflection point. As global decarbonization mandates intensify and energy security concerns reshape national strategies, the reliability of nuclear infrastructure has never been more pivotal. At the heart of this infrastructure lies a specialized, high-stakes component market: nuclear valves. These engineered systems are not merely ancillary equipment; they are the guardians of containment, pressure regulation, and safety protocols within some of the world's most hazardous environments. For executives navigating capital allocation, supply chain resilience, and technology roadmaps, understanding the trajectory of the nuclear valves market is essential.
This article serves as a strategic preview of PW Consulting's latest comprehensive market intelligence product. It outlines the macro-economic currents driving the sector, highlights the competitive architecture defining the landscape, and explains why access to granular, forward-looking data is indispensable for outperforming in 2026. By synthesizing historical performance with projected growth vectors, we provide a foundation for decisions that will define operational success over the next half-decade.
The Macro Landscape: Growth, Scale, and Trajectory
The nuclear valves market has demonstrated consistent resilience and expansion over the past five years. Drawing from our analysis of historical data spanning 2020 through 2025, the market has evolved from a base valuation of 1.60 billion USD in 2020 to an estimated 2.14 billion USD in 2025. This represents a compound annual growth trajectory that underscores the sector's steady maturation and the sustained investment in nuclear capacity worldwide.
Nuclear Valves Market
Looking ahead, our forecast model projects the market to reach 2.23 billion USD in 2026, continuing a growth arc that extends through 2032. By the end of the forecast period, the market is anticipated to approach 3.25 billion USD. This expansion is underpinned by a forecast-period CAGR of 6.1 percent, a figure that signals robust demand driven by reactor restarts, new-build programs, and the modernization of aging facilities. The growth is not merely nominal; it reflects deepening complexity in valve specifications, stricter regulatory compliance requirements, and the integration of advanced materials and digital monitoring systems.
While the headline figures paint a picture of steady expansion, the underlying dynamics are nuanced. Value creation is increasingly concentrated within specific engineering niches, where differentiation stems from certifications, heritage in safety-critical applications, and the ability to support both legacy reactors and emerging technologies like small modular reactors (SMRs). The market's structure, characterized by a consolidated landscape where the top three players command significant share and the top five entities control a substantial majority of revenue, suggests that competitive advantages are deeply entrenched. This concentration implies that new entrants face high barriers, while incumbents leverage long-term utility relationships and certified manufacturing capabilities to maintain pricing power and customer stickiness.
Unpacking the Forecast: Beyond Aggregate Numbers
A superficial glance at the market trajectory might suggest a uniform growth environment. However, the strategic reality is far more segmented. The distribution of value across valve types reveals distinct engineering priorities. Gate valves and globe valves continue to dominate the revenue mix, reflecting their foundational roles in isolation, throttling, and high-integrity containment within nuclear circuits. Ball valves and butterfly valves occupy significant positions, particularly in applications demanding rapid actuation and lower flow resistance profiles. Check valves, diaphragm valves, and other specialized types round out a diversified portfolio that responds to the heterogeneous needs of nuclear facilities.
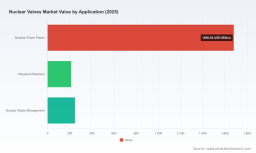
The application domain further stratifies the market. Nuclear power plants remain the primary revenue engine, absorbing the lion's share of demand as operators focus on reliability, life extension, and compliance with evolving safety codes. Yet, adjacent segments are gaining traction. Research reactors and nuclear waste management applications represent specialized, high-value niches where valve performance criteria diverge sharply from commercial power settings. Waste management, in particular, introduces unique challenges around radiation resistance, long-term sealing integrity, and material degradation, driving demand for purpose-built solutions that command premium positioning.
Geographically, the market's footprint is broad but uneven. Asia Pacific has emerged as a region of considerable scale, reflecting the aggressive nuclear expansion programs in several key economies. North America and Europe continue to represent mature, high-compliance environments where valve procurement is heavily influenced by regulatory frameworks, long-term service agreements, and the need for certified domestic or allied supply chains. Latin America and the Middle East and Africa, while smaller in absolute terms, are regions where infrastructure development and energy diversification initiatives are creating incremental opportunities for qualified suppliers. Understanding how these regional dynamics interact with local content requirements, sanctions regimes, and technology transfer restrictions is essential for firms planning cross-border strategies.
Competitive Architecture: The Incumbents and the New Dynamics
The competitive landscape of the nuclear valves market is defined by a cadre of firms that have invested decades in building technical credibility, regulatory certifications, and deep relationships with utility operators. These companies do not compete solely on price; they compete on audit-ready documentation, code compliance, heritage in specific reactor types, and the ability to deliver integrated valve-actuator packages with full lifecycle support.
Crane Nuclear, headquartered in Kennesaw, Georgia, exemplifies long-standing heritage in the sector. Since 1956, the firm has specialized in manufacturing nuclear-grade gate, globe, check, and quarter-turn valves bearing ASME N and NPT stamps for Class 1, 2, and 3 applications. Its historical footprint includes supplying valves for the first commercial nuclear power plant at Shippingport, and its ongoing diagnostics and services offerings reinforce its position as a trusted partner for commercial nuclear power plants. This legacy translates into a competitive moat built on decades of operational data, regulatory familiarity, and customer trust.
Neway Valve, based in Suzhou, Jiangsu, China, represents the growing capability of Asian manufacturers to meet rigorous international standards. The company produces nuclear gate, ball, globe, check, and butterfly valves qualified to NNSA Grade 1, 2, and 3 design and manufacturing licenses, alongside full ASME N and NPT certificates. Its portfolio is tailored for EPR, AP1000, and Hualong-1 reactors, positioning it as a supplier capable of supporting both established and next-generation reactor designs with full-range nuclear compliance. This dual certification footprint allows Neway to serve markets that demand both domestic regulatory approval and internationally recognized code compliance.
Trillium Flow Technologies, located in Huddersfield, United Kingdom, brings a focused engineering approach to nuclear valves and actuators. The company designs and manufactures engineered nuclear valves and actuators with ASME Section III N and NPT stamps, including safety relief and specialty valves for new-build and operating reactors worldwide. Its active ASME Section III N and NPT stamps at two production sites underscore a commitment to redundancy and supply chain resilience, qualities that are increasingly valued by operators seeking to mitigate single-source vulnerabilities.
Velan Inc., headquartered in Montreal, Quebec, Canada, has carved out a distinctive role in the nuclear space. The company produces nuclear Class 1, 2, and 3 gate, globe, check, and ball valves under ASME N and NPT certificates, and has expanded its relevance into the SMR domain, including projects such as the BWRX-300. Notably, Velan secured the first ASME N stamp for nuclear valves in 1971, and it remains the only manufacturer supplying nuclear valves to the first U.S. small modular reactor project. In October 2025, Velan secured a main services agreement for valves on North America's first small modular reactor project, marking a milestone in the commercialization of SMR valve supply chains.
Flowserve Corporation, based in Irving, Texas, USA, operates at the intersection of pumps, valves, and seals for nuclear applications. Its supply of nuclear-qualified equipment across Class 1-3 applications for global nuclear projects is supported by long-term utility relationships and ongoing SMR qualification programs. Flowserve's breadth of portfolio and established service networks make it a versatile partner for operators seeking integrated fluid control solutions.
Framatome, headquartered in Paris, France, leverages its broader reactor systems expertise to deliver safety-related nuclear valves and actuators. Through subsidiaries including Valserve, Framatome designs and manufactures components for PWRs, BWRs, and advanced reactors under ASME III, RCC-M, and other codes. In April 2025, Framatome completed the acquisition of Trillium Flow Technologies France, rebranding it as Sebim to strengthen its nuclear valves product line. This move signals a strategic consolidation within the European supply base, aiming to bundle valve and actuator capabilities under a unified engineering umbrella. Concurrently, in April 2025, Bruce Power signed a 10-year alliance with Trillium Flow Technologies for nuclear valve supply and related services, illustrating how long-term partnerships are becoming a defining feature of the market's procurement architecture.
Regulatory and Technical Dynamics Shaping Procurement
The nuclear valves market operates within a tightly regulated environment where certification is not a formality but a prerequisite for market access. ASME N and NPT stamps, along with national regulatory approvals such as NNSA grades, function as gatekeepers that separate qualified suppliers from the broader industrial valve market. Companies like Crane Nuclear, which has maintained ASME N and NPT stamps since its inception, and Neway Valve, which holds NNSA Grade 1, 2, and 3 licenses plus full ASME certifications, demonstrate how regulatory standing is intertwined with commercial viability. Trillium Flow Technologies' dual-site ASME Section III N and NPT stamp coverage further highlights how manufacturers are building geographic and operational redundancy to satisfy utility procurement requirements and risk management protocols.
These regulatory dynamics have direct implications for supply chain planning. Utilities and EPC contractors increasingly prioritize vendors that can demonstrate traceability, material certification, and code compliance at every stage of the valve lifecycle. The presence of ASME stamps, the ability to support Class 1, 2, and 3 applications, and the capacity to provide diagnostics and services are becoming differentiators that influence bid evaluation criteria. In this context, market participants that invest in certification maintenance, quality system upgrades, and digital documentation are better positioned to capture high-value contracts and sustain margins.
Why Granular Intelligence Matters for 2026 Decision-Making
While the macro trends and competitive profiles outlined here provide a strategic compass, they are insufficient on their own for operational planning. The nuances that drive procurement decisions, pricing negotiations, and technology adoption are embedded in the granular detail of the market. For example, understanding how the revenue split across valve types correlates with specific reactor programs, or how regional demand patterns align with local content mandates, requires access to segmented data that reveals the interplay between engineering specifications, regulatory environments, and commercial execution.
Valves Market
Similarly, the competitive dynamics are not static. Acquisitions, alliance formations, and certification expansions can shift market share, alter supply chain dependencies, and redefine the value proposition of incumbents overnight. The recent acquisition of Trillium Flow Technologies France by Framatome and the 10-year alliance between Bruce Power and Trillium Flow Technologies are indicative of a market where strategic bundling and long-term service commitments are reshaping competitive boundaries. Decision-makers need to know not just who the players are, but how their capabilities, geographic footprints, and partnership networks are evolving in real time.
This is precisely why PW Consulting's Nuclear Valves Market report is structured to deliver actionable intelligence beyond top-line forecasts. The report provides a deep dive into the segmentation landscape, competitive positioning, regulatory frameworks, and demand drivers that collectively inform capital allocation, vendor selection, and risk mitigation strategies. By mapping the revenue distribution across valve types, application domains, and regions, the report equips stakeholders with the context needed to identify growth pockets, anticipate supply constraints, and align product development with the most promising market vectors.
For executives planning 2026 initiatives, the report offers a structured framework to evaluate where to invest, whom to partner with, and how to navigate the certification and compliance pathways that gate market entry. Whether the objective is to expand into new reactor programs, secure long-term service agreements, or assess the impact of SMR commercialization on valve demand, the granular data and analytical rigor contained in the full report provide a reliable foundation for evidence-based decision-making.
Navigating Forward: From Insight to Action
The nuclear valves market is on a sustained growth trajectory, but growth alone does not guarantee strategic success. The firms that thrive will be those that translate market awareness into disciplined execution: investing in certified manufacturing capabilities, forging durable utility partnerships, adapting to the technical demands of advanced reactors and SMRs, and maintaining a vigilant eye on regulatory evolution. As the market approaches the 2026 horizon, the difference between reactive participation and proactive leadership will be determined by the quality of intelligence and the speed with which insights are operationalized.
PW Consulting's comprehensive research is designed to be that intelligence engine. By delivering a detailed, data-rich, and strategically oriented view of the nuclear valves market, the report enables stakeholders to cut through noise, focus on high-impact variables, and make decisions that compound value over the forecast period. The full analysis, including segmentation breakdowns, competitive assessments, and forward-looking scenarios, is available in the complete report. For those ready to move from strategic overview to precision planning, the next step is to access the full intelligence package and begin aligning 2026 agendas with the realities of a market in transformation.
For detailed analysis of this topic, please visit the official page: Nuclear Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com