

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pallet Conveyor Market to Hit $2.36B by 2032, Driven by 5.2% CAGR and Logistic Demand

Strategic Intelligence for the Pallet Conveyor Market: Navigating the 2026–2032 Growth Arc
The global supply chain is undergoing a structural realignment. As organizations confront persistent labor constraints, escalating material costs, and tightening safety regulations, automated material handling has shifted from a tactical efficiency measure to a core strategic imperative. Pallet conveyor systems sit at the intersection of these forces, enabling warehouses, distribution centers, and industrial facilities to move unit loads with greater predictability, throughput, and operational resilience. This market intelligence briefing introduces PW Consulting's latest comprehensive study on the Pallet Conveyor Market, designed specifically to equip executive decision-makers, procurement leaders, and capital investment committees with the analytical clarity required for 2026 strategy formulation and beyond.
The Macro Trajectory: Baseline Data and Forward Visibility
Market momentum is best understood through verified revenue baselines and a disciplined forecast horizon. Drawing on historical revenue data spanning 2020 through 2025, and extending a seven-year projection window to 2032, the analysis maps a market that has demonstrated consistent expansion after navigating near-term volatility. Evaluated in USD millions, the sector's revenue footprint has progressed from approximately 1,284.6 million in 2020 through a period of recalibration, before accelerating toward 1,588.1 million in 2024 and 1,655.2 million in 2025. The trajectory ahead points to continued scaling, with projected revenue reaching roughly 1,758.7 million in 2026 and advancing toward 2,360.2 million by 2032.
The compound annual growth rate anchoring this forecast stands at 5.2 percent, a figure that reflects measured but durable expansion rather than speculative overreach. For leadership teams evaluating multi-year facility roadmaps, this rate represents more than a top-line statistic. It signals a market environment in which capital deployment timing, vendor selection, and system architecture decisions will compound in importance over the forecast period. Sustained mid-single-digit growth rarely emerges from a single driver; instead, it consolidates demand across multiple operational pressures that we examine in the dynamics section below.
Why This Study Matters for 2026 Decision-Making
Annual strategic planning cycles increasingly require evidence that can withstand board-level scrutiny, procurement negotiations, and engineering validation. A market research deliverable in this category is not intended as a static reference document; it functions as an operational compass. The Pallet Conveyor Market study is structured to convert macro conditions into actionable intelligence across four decision-critical dimensions:
- Capital allocation timing. Understanding where revenue is accumulating, which system types are gaining share, and how regional deployment patterns are evolving helps leaders sequence capital requests, avoid premature or lag investments, and align capital budgets with realistic demand horizons.
- Vendor and integrator evaluation. A competitive landscape shaped by specialized manufacturers and globally operating solution providers requires due diligence beyond brochure comparisons. The study maps capability profiles, product philosophies, and recent activity so that engineering and procurement teams can frame RFPs with greater precision.
- Risk and compliance readiness. Safety standards, material price volatility, and labor-driven demand shifts are no longer peripheral concerns. They affect system design, integration cost, and lifecycle operating expense. The analysis embeds these realities so that risk is priced into business cases rather than discovered post-deployment.
- Scenario planning. Long-range forecasts are most valuable when they support branching contingencies. The forecast window through 2032 enables stress-testing of volume assumptions, technology adoption pathways, and regional expansion plans under multiple operating conditions.
These functions are especially relevant in 2026 because organizations are making commitments that will shape facility operations well into the next decade. Whether the decision involves greenfield automation, brownfield line upgrades, or multi-site standardization, the study is designed to reduce ambiguity without oversimplifying the operational complexity that conveyor integration entails.
Segmentation Architecture and Competitive Structure
A market of this scale is never homogeneous. Revenue concentration, system-type distribution, application demand, and regional deployment patterns collectively determine where opportunity and risk are concentrated. The study disaggregates these layers so that strategists can distinguish between headline growth and the underlying pockets of momentum.
Market concentration remains significant, with the three largest competitors accounting for roughly 54.6 percent of sector revenue and the five largest reaching approximately 67.2 percent. That level of concentration has direct implications for negotiation leverage, integration partnerships, and supply continuity. It also underscores the importance of understanding not only the dominant players but also the specialized manufacturers and integration-focused firms that influence pricing dynamics, customization capacity, and regional service coverage.
The segmentation framework addresses three axes that matter operationally:
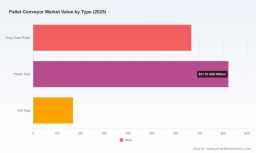
- System type. Pallet conveyor architectures vary substantially in mechanical design, load handling philosophy, and integration behavior. The study separates major type categories to clarify where design preferences, maintenance profiles, and throughput requirements diverge. Drag chain roller systems, plastic-type constructions, and slat-type designs each present distinct trade-offs in durability, flexibility, cleanability, and precision control. Decision-makers evaluating technology roadmaps benefit from understanding which architectures align with specific operational constraints rather than treating the category as interchangeable.
- Application context. Demand is shaped by the operational environment in which conveyors are deployed. Retail and logistics operations, industrial manufacturing environments, and food and beverage processing each impose different hygiene, throughput, changeover, and traceability requirements. Mapping application-level demand patterns helps executives align capacity investments with end-use realities rather than relying on generic automation assumptions.
- Regional deployment. Geographic distribution of revenue reflects infrastructure maturity, logistics network density, labor market conditions, and regulatory environments. The study separates regional revenue patterns to help leaders identify where adoption is most established, where growth is accelerating, and where local sourcing, service, and compliance considerations should influence procurement strategy.
Importantly, this briefing is structured to communicate the strategic shape of these segments without diluting the analytical value of the full report. The complete study provides the depth required to pinpoint where specific product architectures, application verticals, and regional pathways are converging or diverging over the 2026–2032 window.
Palletizer Market
Competitive Landscape: Capability Profiles and Strategic Positioning
The competitive field in pallet conveyor systems is defined by a blend of specialized manufacturers, globally operating platforms, and custom integration providers. Each brings a distinct posture toward engineering, throughput control, modularity, and service scope. The study profiles the organizations shaping this environment so that buyers and investors can interpret competitive behavior with greater accuracy.
Among the companies examined are firms whose product philosophies and operational footprints illustrate the diversity of the market. Alba Manufacturing, based in Albany, Oregon, concentrates on heavy-duty, pre-engineered pallet handling conveyor systems oriented toward industrial applications. Hytrol Conveyor Co., headquartered in Jonesboro, Arkansas, provides complete pallet handling conveyor systems and solutions for material handling across varied weights and environmental conditions. Interroll, operating globally from Switzerland, offers a Modular Pallet Conveyor Platform alongside integrated pallet handling components for conveyors, sorters, and storage systems. Dorner Manufacturing, located in Hartland, Wisconsin, specializes in pallet system conveyors featuring dual-move and timing belt-driven configurations for more precise flow control. mk North America, based in Michigan, manufactures VersaFlex pallet conveyor systems designed for adaptable, quick-change pallet handling in assembly and production environments. Roach Conveyors, operating from Sullivan, Missouri, produces American-made engineered pallet, package, and modular conveyor systems for warehousing and manufacturing. Swisslog, also headquartered in Switzerland with global operations, develops ProMove pallet conveyor systems integrated with automated storage and retrieval systems for automated warehouse and distribution facilities. Ashland Conveyor, based in Akron, Ohio, supplies custom material handling and warehouse conveyor systems, including pallet handling solutions. Adaptecsolutions, operating in the United States, distributes and integrates custom pallet conveyor systems engineered to client specifications. Pack Air Inc., also based in the United States, manufactures custom heavy-duty pallet conveyor systems using chain-driven live-roller and drag-chain technology.
This breadth matters because pallet conveyor purchasing decisions rarely reduce to a single specification sheet. A facility prioritizing rapid line reconfiguration will evaluate vendors differently from one prioritizing heavy-load durability, hygiene compliance, or AS/RS integration. Likewise, organizations assessing supply risk or partnership stability benefit from understanding how each player positions itself across engineering capability, geographic reach, and system integration depth. The study's competitive analysis lends structure to these evaluations, enabling more disciplined vendor shortlisting and more credible negotiation positioning.
Market Dynamics: Cost Pressure, Regulation, and Demand Drivers
Pallet conveyor adoption does not expand in a vacuum. It responds to operational costs, compliance mandates, and structural changes in how goods move through logistics and manufacturing networks. Three interlocking dynamics shape the current environment and inform the study's forward-looking analysis.
Pallet Conveyor Market
Labor conditions remain a decisive demand catalyst. Continued labor shortages and rising labor costs in logistics and manufacturing operations are driving demand for pallet conveyor automation. As facilities confront throughput targets with constrained staffing, automation shifts from optional efficiency tooling to operational necessity. This pressure increases the strategic weight of conveyor investments, particularly where systems can reduce manual material handling, standardize flow, and improve repeatability across shifts.
Material cost volatility introduces a parallel layer of complexity. Steel-mill product prices increased by 12 percent year-over-year during 2024–2025, while fluctuations in aluminum and copper prompted fabricators to implement price-escalation clauses that raised conveyor costs by approximately 8–10 percent. For procurement teams and project financiers, these movements affect not only initial capital expense but also contract structuring, vendor negotiations, and total cost of ownership modeling. The study incorporates these pressures so that leadership can anticipate cost volatility rather than absorb it as an after-the-fact surprise.
Regulatory and safety requirements are simultaneously becoming more explicit. EN619:2022 sets comprehensive safety requirements for pallet transport conveyors, mandating protective gaps and compliance with EN ISO 13854:2019 for mechanical handling of unit loads. In parallel, OSHA references ANSI/ASME B20.1 as the industry consensus standard for conveyor safety, with integrators required to perform documented risk assessments under EN ISO 12100 and achieve Performance Level under EN ISO 13849. These standards shape engineering specifications, integration obligations, and documentation burdens. They also influence vendor selection, because compliance maturity increasingly differentiates suppliers in competitive evaluations. Recent product activity reflects this direction: Swisslog's ProMove pallet conveyor system achieved certification for EN619:2022 safety standards with advanced protective features. Meanwhile, Alba Manufacturing exhibited at MODEX 2026 with heavy-duty pallet handling conveyor solutions, signaling continued in-market visibility and product iteration among established participants.
Together, these dynamics create a market environment where strategic decisions must account for operational labor economics, material cost exposure, and compliance readiness in the same frame. The study integrates these forces so that executives can evaluate pallet conveyor investment as a coherent business case rather than as a sequence of disconnected considerations.
What the Full Study Delivers
This briefing outlines the strategic frame; the complete report supplies the analytical infrastructure required to act on it. The study is built for teams that need to translate market conditions into procurement plans, capacity commitments, vendor comparisons, and long-range facility strategies. Its scope includes:
- A detailed revenue baseline and forward forecast that situates current market size within a projected growth path, enabling multi-year planning with a defined CAGR anchor.
- Segment-level analysis across system types, application environments, and regional deployment patterns, designed to help readers identify where demand is concentrated and where architectural or operational differentiation matters most.
- Competitive profiling of key manufacturers and integration-oriented providers, with attention to product philosophy, operational footprint, and recent market activity.
- Evaluation of market dynamics including labor-driven automation demand, raw material price pressure, and evolving safety and compliance standards, integrated into the broader investment narrative.
- Structured context for scenario planning, so leadership teams can test assumptions regarding volume growth, technology adoption, regional expansion, and vendor strategy over the 2026–2032 window.
The report is intended for use by strategy leaders, operations executives, engineering and procurement teams, and investors seeking a grounded view of where pallet conveyor demand is headed and how competitive forces are shaping purchasing conditions. It is designed to support decisions that must hold up under technical review, financial scrutiny, and compliance validation.
Conclusion: Translating Market Intelligence into 2026 Execution
The Pallet Conveyor Market is expanding within a landscape defined by durable demand drivers and increasingly specific operational constraints. Sustained mid-single-digit growth, meaningful revenue concentration, and a competitive field spanning specialized manufacturers and globally integrated solution providers all point to a market where informed selection matters as much as timing. At the same time, labor economics, metal price volatility, and tightening safety standards are reshaping how systems are specified, priced, and integrated.
For organizations making 2026 commitments, the strategic question is no longer whether pallet conveyor automation has relevance, but how to evaluate it with enough precision to avoid over- or under-investing relative to actual operational needs. That requires more than headline market size. It requires segment clarity, vendor context, dynamic risk factors, and a forecast structure that supports decision-making across multiple possible futures.
The full PW Consulting Pallet Conveyor Market study is built to provide that depth. Readers seeking complete segmentation detail, concentration analysis, vendor positioning frameworks, and forecast-supported scenario inputs are encouraged to access the full report through the source page, where the complete intelligence package is available for strategic review and operational planning.
For detailed analysis of this topic, please visit the official page: Pallet Conveyor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com