

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chemical Injection Metering Pumps & Valves Market Poised to Reach USD 4,700 Million by 2025

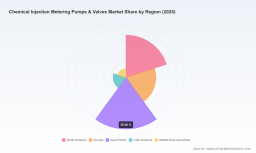
Chemical Injection Metering Pumps & Valves Market: Strategic Imperatives for 2026
As upstream activity recalibrates after successive cycles of oil price volatility, and water- and process-intensive industries accelerate digital and sustainability investments, chemical injection metering pumps and valves remain a mission‑critical element of operational integrity. PW Consulting’s latest market study—covering 2020–2025 historical performance and offering a 2026–2032 forecast—translates these dynamics into an actionable decision framework for executive teams planning capital allocation, supplier strategy, and technology adoption in 2026.
Air & Water Rinsing Machines Market
Market trajectory at a glance
Our analysis shows the global market expanding from the low billions in 2020 to an estimated USD 4.7 billion in 2025, with a projected upward trend to roughly USD 6.12 billion by 2032. The forecast period (2026–2032) is characterized by a compound annual growth rate (CAGR) of 3.85%. This mid-single-digit growth masks important inflection points: pockets of accelerated demand tied to deepwater and offshore chemical injection requirements, and episodic investment driven by water‑treatment and industrial process modernization programs.
Precious Metal Accounts Market
Importantly, the market is concentrated: the top three suppliers capture a meaningful share, and the top five command more than half of market revenues. That concentration has strategic implications for procurement leverage, qualification timelines, and M&A playbooks in 2026 and beyond.
Worldwide Coin-operated Commercial Laundry Market
Why 2026 is a pivotal year for decisions
- CapEx timing vs. operating risk: Many operators will face the classic CAPEX-versus-OPEX decision—invest today in higher‑specification, digitally enabled metering systems that reduce leak risk and maintenance burden, or continue with lower‑cost units and accept higher operational surveillance costs. Our scenarios quantify break‑even horizons for each approach under plausible oil price and service‑cost trajectories.
- Supplier selection under consolidation: With CR3 and CR5 indicating a moderately concentrated landscape, 2026 procurement strategies must weigh supplier stability, aftermarket coverage, and integration of engineered packages versus component‑level sourcing to preserve negotiating flexibility.
- Standards and compliance: API 675 remains the definitive specification for reciprocating positive‑displacement metering pumps in petroleum and petrochemical services. Tender and specification teams that align procurement language with API 675—and understand where bespoke engineering is justified—reduce specification risk and life‑cycle costs.
- Raw material volatility: Fluctuations in stainless steel and specialty alloys will affect margins and lead times. Hedging, multi‑sourcing, or strategic inventory moves are nontrivial decisions for 2026 procurement calendars.
What the PW Consulting report delivers—practical, decision‑grade content
This study is designed to be operationally useful, not just descriptive. Key deliverables include:
- Top‑level market sizing and seven‑year forecast with scenario bands that reflect differentiated demand drivers (offshore deepwater activity, water treatment modernization, chemical processing expansions).
- Vendor benchmarking that goes beyond product specs to assess API compliance, field reliability, aftermarket footprint, digital connectivity, and skid integration capability.
- Procurement playbooks with tender language templates, qualification checklists, and a risk‑weighted supplier short‑list methodology that procurement and engineering teams can use immediately.
- Technology and product roadmaps highlighting where diaphragm, piston, peristaltic and hybrid solutions are most appropriate—paired with OPEX modeling and lifecycle cost calculators.
- Supply‑chain stress tests and mitigation options to manage raw‑material and lead‑time volatility, including alternative materials, modular designs, and local assembly strategies.
- M&A and partnership screeners that identify acquisition targets and strategic alliance opportunities for component manufacturers, skid integrators, and valve specialists.
Competitive landscape—who matters and why
The vendor environment blends legacy pump specialists, engineered‑package integrators, and niche valve innovators. Our competitive analysis synthesizes company‑level strengths relevant to 2026 decisions:
- LEWA GmbH — Renowned for hermetically sealed diaphragm pumps and API‑compliant chemical injection packages. Strong in high‑pressure, critical applications where leak containment and reliability are non‑negotiable.
- IDEX Corporation (Pulsafeeder, Milton Roy, LMI) — A diversified portfolio across hydraulic diaphragm, solenoid‑driven, and mechanical metering technologies. Valuable where organizations prioritize breadth of solution and global aftermarket coverage.
- SPX Flow (Bran+Luebbe) — Excels in custom chemical injection systems for offshore applications, including double‑diaphragm designs that target high accuracy under cyclic loads.
- ProMinent GmbH — Notable for rapid product innovation and digital connectivity. Its recent beta/X launch signals the industry’s move toward lower‑footprint, connected diaphragm pumps with expanded control features.
- SkoFlo Industries — A specialist in pressure‑independent chemical injection metering valves for surface and subsea use—an increasingly important capability as field architectures consolidate pumps and distribute dosing points.
- Sidewinder, CheckPoint, Bruin Pumps — These suppliers are differentiated by ruggedized designs, solar and pneumatic offerings, and operational focus on oilfield chemicals such as methanol and corrosion inhibitors.
- Neptune (PSG) and Iwaki America — Strong positions in water treatment and industrial dosing, where precision at micro‑to‑mid flows and serviceability are priority purchase drivers.
Recent product introductions—from hydraulic API‑675 hydraulic diaphragm models to next‑generation solenoid and electronic drives—underscore supplier efforts to combine accuracy, reliability and connectivity. Our report maps these introductions to likely adoption pathways and total cost implications for field operators.
Regulation, materials, and deployment dynamics
Three external forces will shape vendor and buyer behavior in 2026:
- Standards enforcement: API 675 continues to set the bar for critical hydrocarbon applications. Tender committees that conflate “API‑style” features with true API 675 compliance expose projects to specification and warranty risk.
- Materials and cost volatility: Stainless steel and specialty alloy price swings require procurement to embed price adjustment mechanisms or design flexibilities into long‑lead contracts.
- Field architectures: Increasing deployment of pressure‑independent valves and multi‑point injection strategies will influence the balance between centralized high‑pressure pumps and distributed pumping concepts—affecting OPEX profiles and control complexity.
Actionable recommendations for C‑suite and procurement leaders in 2026
- Prioritize total‑cost‑of‑ownership analysis when approving CapEx: quantify leak‑risk, maintenance intervals, and digital monitoring ROI rather than defaulting to lowest initial cost.
- Implement a two‑track supplier strategy: maintain relationships with tier‑one API‑compliant vendors for critical duty, while qualifying regional specialists and valve innovators for lower‑risk or distributed injection points.
- Embed material‑price escalation clauses and dual‑sourcing for long‑lead components to blunt the impacts of alloy price swings.
- Accelerate pilot programs for connected metering assets that feed predictive‑maintenance outputs into existing asset‑management systems; validate expected OPEX reductions before fleet‑wide rollouts.
- Use the market concentration profile to time negotiations and partnerships—early 2026 may present a window to secure aftermarket commitments and favorable lead times before anticipated capacity investments among leading vendors.
Why PW Consulting’s study is the tactical tool your team needs
Beyond headline numbers, the report provides the blueprints procurement and engineering teams can use immediately: editable tender text, supplier‑scoring matrices, lifecycle cost models, and scenario playbooks that map supplier choice to field outcomes. We intentionally withhold granular segment tables from this press release to preserve the utility of the primary deliverable: a compact, executable intelligence product that guides supplier selection, risk mitigation and investment timing for 2026.
Next steps
Executives and technical leaders preparing budgets and supplier strategies for 2026 should review the full report to access the detailed segmentation, supplier scorecards, and downloadable procurement tools. PW Consulting also offers tailored briefings and live workshops to translate report findings into a 90‑day action plan for procurement, reliability engineering, and business development teams.
To obtain the complete study and arrange a strategy session, please visit the PW Consulting report page for Chemical Injection Metering Pumps & Valves Market. The full report contains the proprietary segment detail, company scorecards, and scenario models referenced here—essential inputs for any organization seeking to convert 2026 decisions into measurable performance gains.
For detailed analysis of this topic, please visit the official page: Chemical Injection Metering Pumps & Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com