

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cryocoolers Market Hits $215M in 2025, Projected 6.98% CAGR Through 2032

Strategic Intelligence for the 2026 Decision-Maker: Inside the Global Cryocoolers Market
As industrial ecosystems pivot toward extreme-temperature applications, the cryocooler sector has transitioned from a niche enabling technology to a strategic growth vector. Over the past five years, the market has demonstrated sustained expansion, with historical revenue trajectories showing a clear acceleration from approximately 163.15 million USD in 2020 to 201.13 million USD in 2024. This momentum carried the base year valuation to 215.0 million USD in 2025, and the forward trajectory points toward a forecasted valuation of 222.53 million USD in 2026. More importantly, the sector is positioned to compound at a steady pace through 2032, with revenue projections reaching 344.8 million USD by the end of the forecast horizon. For executive teams navigating capital allocation, supply chain resilience, and technology roadmapping in 2026, these macro indicators are only the starting point. The real strategic value lies in understanding how structural shifts across defense, healthcare, aerospace, and advanced research are rewiring demand patterns, competitive positioning, and regulatory boundaries.
Why 2026 Demands a Deeper Market Lens
The year 2026 represents a critical inflection point for organizations operating in or adjacent to cryogenic cooling. Demand is no longer driven by a single vertical; instead, it is being shaped by converging technology roadmaps, procurement cycles, and compliance frameworks that vary significantly by region and application. Executive decisions made today—whether evaluating supplier partnerships, assessing capacity expansion, or prioritizing R&D investments—will lock in competitive advantages or expose vulnerabilities across the next several budget cycles. A high-level revenue chart cannot answer whether a given technology type is gaining share in specialized instrumentation, whether regional procurement dynamics are shifting procurement leadership, or how recent regulatory updates are altering go-to-market timelines. That level of granularity requires a structured, data-backed assessment that connects historical performance to forward-looking demand signals.
Market Architecture and Structural Dynamics
The cryocoolers market is defined by a fragmented yet increasingly strategic competitive landscape. Concentration metrics indicate that the top three players account for roughly 24.6 percent of total revenue, while the top five reach approximately 26.2 percent. This distribution signals a market where scale matters, but specialization, application-level integration, and technology differentiation remain decisive. Organizations are not merely competing on cooling capacity; they are competing on vibration profiles, reliability in mission-critical environments, form-factor compactness, and the ability to embed cooling solutions into larger systems such as infrared sensor suites, medical imaging platforms, space payloads, and quantum research infrastructure.
Regulatory and Compliance Signals Redefining Market Access
Recent regulatory activity has introduced new layers of complexity for cross-border trade and technology deployment. In January 2026, Canada updated its Export Control List to include Category 2-20 cryogenic and superconductive equipment rated below 4K. This adjustment affects how certain high-performance cooling systems are classified, shipped, and integrated into international programs. At the same time, the U.S. Bureau of Industry and Security issued an interim final rule in September 2024 controlling cryocooling systems with cooling power at or below 0.1 K for periods exceeding 48 hours. These measures are not peripheral footnotes; they influence qualification pathways, partner selection, and the cost of compliance for companies serving defense, scientific, and advanced industrial customers. Decision-makers need to understand where these controls create friction, where they open procurement windows, and how to structure supply strategies that remain agile under evolving export requirements.
Cryopump Market
Technology Roadmaps and Mission-Driven Demand
Beyond compliance, long-duration space exploration and next-generation energy storage are reshaping technology expectations. NASA’s CACHE program, for example, requires demonstration of high-capacity cryocoolers at Technology Readiness Level 6 for liquid hydrogen storage on future long-duration Mars missions. Such programmatic milestones create demand signals that ripple through supplier pipelines, material selection, and testing regimes. Meanwhile, the broader research community continues to push for compact, low-vibration cooling solutions capable of supporting superconducting detectors, quantum technologies, and precision instrumentation. The convergence of government-backed mission requirements and commercial research needs means that technology readiness, reliability, and customization capability are becoming central battlegrounds for market share.
Competitive Landscape and Recent Strategic Moves
The competitive environment reflects a mix of established industrial manufacturers, defense and aerospace integrators, and specialized technology providers. Several firms have recently signaled their strategic priorities through product launches, contract awards, and conference-level technology disclosures, underscoring how fast the market is evolving.
Innovation Signals from Leading Participants
Sumitomo Heavy Industries has expanded its portfolio with high-capacity single-stage cryocoolers built around Whisper technology, a design approach aimed at quieter operation and reduced moving parts. This launch highlights a broader industry emphasis on minimizing mechanical complexity while improving operational consistency for space, medical imaging, and defense applications. In parallel, Bluefors introduced a compact two-stage pulse-tube cryocooler designed for advanced scientific applications and superconducting nanowire single-photon detectors, reinforcing the growing importance of precision cooling in quantum-oriented research and detector systems.
On the demand side, L3Harris Technologies secured a substantial contract from the U.S. Army for the production of Enhanced Night Vision Goggle-Binoculars incorporating compact cryocoolers. This award illustrates how cooling technology has become embedded in frontline defense systems, where size, weight, power, and reliability constraints directly shape procurement decisions. These moves are not isolated events; they are indicators of where engineering investment and commercial opportunity are converging.
Event-Driven Intelligence and Industry Coordination
Industry coordination is also accelerating. The 2026 International Cryocooler Conference is scheduled to convene in June in Syracuse, New York, bringing together technical presentations and cross-organizational discussions on cooling technology advancements. Events like this matter because they function as both innovation showcases and market signaling mechanisms. They reveal which architectures are gaining engineering traction, which application domains are attracting new development attention, and how suppliers are positioning themselves relative to emerging performance benchmarks. For strategists, such gatherings are essential inputs for monitoring technology diffusion and competitor intent.
What the Analysis Delivers for 2026 Planning
A rigorous market assessment should go beyond top-line projections and provide decision-makers with an operational view of the ecosystem. The full study is structured to translate macro growth signals into actionable intelligence across multiple planning dimensions.
Coverage Designed for Executive and Technical Decision-Making
The analysis integrates historical performance from 2020 through 2025 with a forecast framework extending to 2032, enabling teams to evaluate both near-term momentum and longer-cycle demand formation. Rather than presenting figures in isolation, the report maps revenue evolution against the technological and application forces that are shaping procurement behavior. This allows readers to assess where growth is likely to be durable, where it may be cyclical, and where competitive repositioning is already underway.
Deep-Dive Segmentation Without Losing Strategic Context
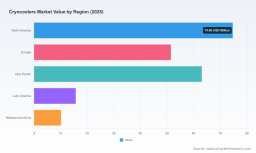
Segment-level insight is essential because cryocooler demand does not behave uniformly across technology types or end-use domains. The study dissects the market by cooling architecture and by application, providing a structured lens on where specific designs are gaining relevance and where end-use sectors are intensifying their cooling requirements. Equally important, the regional view helps organizations understand where demand concentration is forming and how geographic procurement patterns may influence sourcing, partnership, and expansion strategies. The full report preserves that segmentation detail while maintaining a coherent strategic narrative, so that readers can connect numeric structure to business implications instead of treating the data as disconnected tables.
Competitive Profiling and Ecosystem Mapping
The study also profiles the companies that are shaping the market’s direction. It examines organizations with established cryocooler portfolios as well as specialists focused on compact, low-vibration, or mission-specific solutions. The objective is to provide more than a roster of names: it is to clarify how different players are positioning themselves across space, defense, healthcare, industrial gas, research instrumentation, and advanced scientific applications. By mapping company focus areas, technology orientations, and recent commercial activity, the analysis helps buyers, investors, and competitors identify where consolidation pressures may emerge, where niche leadership is being built, and where integration capabilities are becoming a differentiator.
Cryocoolers Market
Why Strategic Procurement and Investment Decisions Depend on Granular Intelligence
In a market where concentration is moderate and application requirements vary sharply, the cost of incomplete information is high. A supplier selection decision made without a clear view of technology-type relevance can lead to integration challenges downstream. A market entry or expansion plan built without a realistic read on regional demand patterns can misallocate resources. A compliance strategy developed without attention to evolving export controls can slow program timelines and complicate partnership structures. These risks are amplified in 2026 because cooling technology is increasingly embedded in systems where performance, size, and regulatory status are inseparable from commercial success.
Turning Market Signals into Actionable Plans
The strongest use of this research is not simply to confirm that the market is expanding, but to determine where expansion is most strategically meaningful. For procurement leaders, the analysis supports supplier evaluation by clarifying which technology families align with specific operational constraints and which participants are actively advancing those designs. For investors and corporate development teams, it provides a structured basis for assessing where value creation is likely to concentrate and which segments are showing the strongest forward demand logic. For R&D and engineering leadership, it helps frame technology priorities in the context of market pull, program milestones, and competitive readiness.
Conclusion: The Strategic Case for Full-Market Clarity
The cryocoolers market is moving from steady growth to a more complex phase defined by application-specific performance demands, regulatory refinement, and targeted technological innovation. Historical data shows a market that has already expanded materially, and the forecast period suggests continued upward momentum toward the end of the decade. Yet the strategic questions facing organizations in 2026 are not answered by aggregate numbers alone. They require a detailed understanding of segmentation dynamics, competitive positioning, compliance impact, and the product-level moves that signal where the market is heading next.
This study is designed to provide that level of clarity. It connects the macro trajectory to the operational realities that decision-makers face when evaluating suppliers, planning capacity, aligning R&D priorities, or preparing for regulatory change. To access the complete segmentation breakdown, company profiles, regional and application-level intelligence, and the full forecast framework, visit the source page for the full Cryocoolers Market research. The detailed dataset and strategic commentary are available there for teams that need to move from market awareness to market action.
For detailed analysis of this topic, please visit the official page: Cryocoolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com