

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sound Level Meters Market Hits $1.3B in 2025, Projects 5.85% CAGR Through 2032

Strategic Intelligence for the 2026 Decision-Maker: Unlocking Value in the Sound Level Meters Market
As global industrialization accelerates and environmental compliance frameworks tighten, the acoustic instrumentation sector stands at a critical inflection point. For executives navigating capital allocation, product development, and regulatory readiness in 2026, understanding the trajectory of the Sound Level Meters Market is no longer optional—it is a strategic imperative. PW Consulting's latest comprehensive study provides a rigorous, forward-looking examination of this evolving landscape, equipping leadership teams with the analytical clarity required to turn market complexity into competitive advantage.
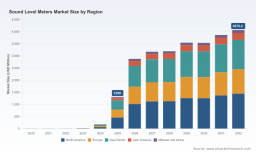
The sector has undergone a pronounced structural transformation over the past half-decade. Where the market landscape once revolved around modest valuation bands, recent historical cycles have demonstrated an aggressive expansion phase, culminating in a substantial revaluation of the addressable opportunity. Building on this momentum, our baseline projections map a sustained growth trajectory through the end of the decade, with an anticipated compound annual growth rate of 5.85 percent across the forecast horizon. In absolute terms, the market is on track to more than double its near-term valuation before plateauing into a mature, high-efficiency operating environment by the early 2030s. For strategists, this curve is not merely a numerical forecast; it is a timing mechanism for capacity planning, supply chain positioning, and partnership strategy.
Decoding the Forecast: Why Macro Scale and CAGR Governance Matter Now
Base-year anchors and forward-looking growth bands are the scaffolding upon which 2026 operating budgets are built. By anchoring analysis in a recent baseline year and extending visibility through 2032, this study enables stakeholders to model demand elasticity, price realization, and inventory turnover with far greater precision. The sheer velocity of recent market expansion has compressed traditional planning cycles. Organizations that continue to rely on linear extrapolation risk either overextending into saturated segments or underinvesting in high-velocity niches. Our forecast architecture corrects for this by mapping inflection points, saturation thresholds, and sustained growth corridors that differentiate cyclical noise from structural opportunity.
For manufacturing leaders, the implication is clear: capacity investment decisions made in early 2026 will face evaluation against a market that matures rapidly. For technology integrators and service providers, the window to embed next-generation acoustic measurement capabilities into broader industrial ecosystems is narrowing. A disciplined assessment of growth velocity, rather than headline size alone, determines which players capture margin expansion and which are relegated to commoditized competition. Every percentage point of CAGR translates into tangible shifts in procurement timing, R&D prioritization, and channel strategy, and this report translates those macro curves into decision-ready frameworks.
Digital Noise Meter Decibel Meter Market
Regulatory Architecture as a Strategic Catalyst
Noise monitoring and occupational safety compliance are governed by an interlocking web of technical standards and enforcement mandates. The IEC 61672-1 framework continues to anchor measurement accuracy expectations, with defined stability parameters that extend well into the next decade and require ongoing calibration and verification for workplace and environmental monitoring. On the occupational front, recognized safety authorities mandate that compliance-grade instruments align with or exceed established Type specifications, ensuring that workplace noise exposure assessments remain defensible under regulatory scrutiny.
Sound Level Meters Market
These requirements are not static. The reaffirmed alignment between major measurement standards and international specifications signals an industry moving toward greater harmonization rather than fragmentation. Simultaneously, the integration of validated measurement applications into occupational hearing-loss prevention programs has expanded the definition of what constitutes a compliant monitoring solution. Organizations that view regulatory evolution as a compliance checklist miss the strategic dimension: standardization lowers entry barriers for adjacent applications, accelerates procurement cycles for large enterprises, and rewards manufacturers that build verifiable accuracy and traceability into their product architecture from the outset. Compliance is increasingly becoming a competitive moat rather than a cost center.
Segmentation Dynamics: Precision vs. Ordinary, Vertical Demand, and Geographic Gravity
One of the most actionable layers of this market lies in its segmentation architecture. The instrument landscape is fundamentally divided between precision-grade professional platforms and ordinary-grade measurement tools, each serving distinct performance requirements, price realities, and end-user expectations. Precision instruments command premium positioning, reflecting the specialized engineering, calibration infrastructure, and labor-intensive build and verification processes required to deliver high-fidelity acoustic measurements. This price stratification is not accidental; it reflects the technical rigor demanded by certified testing environments and regulated compliance workflows, where instrument reliability is non-negotiable.
On the demand side, deployment patterns reveal where measurement intensity is concentrated. Industrial facilities and enterprise operations represent a dominant consumption pillar, driven by continuous environmental monitoring, machinery diagnostics, and workplace safety programs. Environmental protection applications form a robust secondary cluster, reflecting government mandates, municipal monitoring initiatives, and community noise management projects. Transportation ecosystems, research and development laboratories, and a broader set of specialized use cases complete the demand mosaic, each with distinct procurement rhythms, technical specifications, and integration requirements.
Geographic distribution further enriches the segmentation picture. Leadership in market share is distributed across multiple regions, reflecting the interplay of advanced industrial infrastructure, tightening municipal regulations, and expanding manufacturing footprints. Rather than betting on a single regional narrative, the market rewards firms that calibrate their regional strategy to local compliance intensity, channel maturity, and industrial density. The strategic takeaway is that geographic presence is most valuable when synchronized with vertical specialization and application-specific feature sets. By understanding which regions and which verticals are converging, companies can prioritize channel partnerships, localized service networks, and application-specific product configurations that maximize return on market entry.
Competitive Landscape: Specialists, Integrators, and the Battle for Differentiation
The competitive field is composed of established specialists, diversified measurement conglomerates, and agile entrants pursuing specific application niches. At the premium end, several organizations anchor their portfolios around professional-grade platforms designed for rigorous environmental and occupational monitoring. These offerings emphasize measurement fidelity, multi-channel analysis, and long-term durability, catering to users whose measurement outcomes carry regulatory and operational consequences. Complementary players extend the ecosystem through app-integrated Class instruments, wireless workplace assessment modules, and cloud-connected compliance platforms that bridge field measurement with enterprise data workflows.
Occupational safety-focused manufacturers have carved out a strong position by aligning instrument design with workplace exposure assessment, dosimetry integration, and field-ready ergonomics. Others differentiate through software-driven value: real-time data logging, remote reporting, and connectivity features that transform standalone instruments into nodes within broader environmental and safety management systems. In parallel, a cohort of industrial and environmental measurement providers targets broad-spectrum deployment, emphasizing versatility, ease of use, and cost-efficient operation across factories, municipal programs, and field research settings.
Recent product activity underscores how competition is evolving beyond hardware specifications alone. Wireless measurement modules, dedicated occupational health assessment tools, and analyzers with advanced signal-processing options have expanded the functional perimeter of the category. These developments reflect a broader industry shift: buyers are no longer purchasing an isolated instrument; they are selecting a measurement solution that must integrate with compliance workflows, reporting infrastructure, and operational decision loops. In this environment, differentiation is increasingly defined by ecosystem compatibility, validation documentation, and post-sale service reliability as much as by core measurement performance.
What the Study Delivers: From Strategic Mapping to Execution-Ready Intelligence
This market study is structured to support decision-making at multiple organizational levels. Rather than offering a static snapshot, it functions as an operational intelligence toolkit designed for cross-functional use. Executive leadership can leverage the overarching growth architecture to align capital deployment, M&A screening, and long-range planning with empirically grounded demand trajectories. Product and engineering teams will find detailed segmentation analysis useful for calibrating feature roadmaps, identifying performance gaps, and prioritizing precision versus accessibility trade-offs in next-generation designs.
Commercial and go-to-market teams benefit from rigorous competitive profiling that maps company positioning, product differentiation, and recent launch activity across the landscape. By examining how incumbents and challengers are expanding their functional portfolios—whether through wireless connectivity, occupational health specialization, advanced signal analysis, or cloud-enabled compliance features—the study illuminates where white space remains and where consolidation pressures are likely to intensify. Procurement and supply chain stakeholders can use the regional and application breakdowns to refine sourcing strategies, anticipate demand clustering, and align inventory planning with high-velocity deployment zones.
The research also embeds regulatory and standards-driven dynamics directly into its analytical framework. Because compliance requirements shape both instrument design and purchasing behavior, the study evaluates how evolving measurement specifications, calibration expectations, and occupational safety mandates influence competitive positioning and market access. This ensures that strategic conclusions are grounded not only in volume and revenue projections, but also in the enforceable realities that determine which solutions win in regulated procurement environments.
Translating 2026 Intelligence into Actionable Strategy
For organizations operating in or adjacent to the acoustic measurement sector, 2026 is a year of positioning. The market is large enough to reward scale, yet segmented enough to reward precision targeting. Growth rates signal opportunity; regulatory continuity signals stability; competitive intensity signals the need for sharper differentiation. The firms that will outperform are those that treat market intelligence as a dynamic input to product design, channel strategy, compliance readiness, and regional expansion, rather than as a retrospective record of where demand has been.
PW Consulting's full study goes beyond the directional themes outlined here. It provides the granular segmentation data, competitive benchmarking, regional breakdowns, application-level demand profiles, and forward-looking scenario analysis required to convert high-level market awareness into executed strategy. For leadership teams preparing investment committee presentations, product launch roadmaps, or market-entry assessments, the complete report delivers the depth and specificity needed to reduce uncertainty and accelerate decision cycles.
The Sound Level Meters Market is not simply expanding; it is reorganizing around precision, compliance, connectivity, and application specificity. The organizations that decode this reorganization first will define the next phase of competitive advantage. Access the full PW Consulting market study to secure the comprehensive intelligence your team needs to lead, not follow, in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Sound Level Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com