

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Isoparaffin Solvents Market to Reach $1.14B by 2032 with 3.5% CAGR
By pmarketresearch, 2026-09-15
Navigating the Isoparaffin Solvents Market: Strategic Intelligence for 2026 Decision-Makers
The global industrial landscape is undergoing a fundamental shift in how solvents are sourced, formulated, and regulated. As environmental compliance tightens and downstream manufacturers demand higher-purity, low-odor, and low-aromatic hydrocarbon solutions, isoparaffin solvents have emerged as a critical link in the value chain. For executives, procurement leaders, and investment strategists, understanding the trajectory of this market is no longer a niche analytical exercise—it is a core component of operational resilience and competitive positioning.
PW Consulting's latest Isoparaffin Solvents Market research report is designed precisely for this moment. Built on rigorous historical reconstruction and forward-looking scenario modeling, the study provides a structured, data-backed roadmap for 2026 planning. Rather than offering a static snapshot, this intelligence synthesizes multi-year demand signals, capacity adjustments, regulatory inflection points, and competitive maneuvers into an executable framework. Below, we outline the core architecture of this analysis and demonstrate why it belongs on your strategic dashboard this year.
Market Trajectory: A Multi-Year Arc of Measured Expansion
The isoparaffin solvents sector has demonstrated steady, compounding growth across the recent historical window, reflecting consistent demand from coatings, industrial cleaning, metalworking, and specialty formulation segments. From a foundational base of approximately 761 million USD in 2020, the market advanced to 766 million USD in 2021, climbed to 803 million USD in 2022, and continued its upward march to 851 million USD in 2023 and 858 million USD in 2024. By 2025, the overall market reached roughly 905 million USD, signaling a mature but still expanding revenue base.
Looking ahead, the forecast horizon through 2032 maps a projected ascent to approximately 1.14 billion USD, underpinned by a compound annual growth rate of 3.5% measured from the base year of 2025. The year-by-year progression—940 million USD in 2026, 983 million USD in 2027, 1.01 billion USD in 2028, 1.06 billion USD in 2029, a slight recalibration in 2030, and continued gains to 1.11 billion USD in 2031 and 1.14 billion USD in 2032—reveals a market that is neither hyper-volatile nor stagnant. Instead, it reflects disciplined expansion shaped by regional capacity investments, formulation substitution trends, and the gradual migration from aromatic-heavy solvent systems toward high-purity isoparaffinic alternatives.
For 2026 decision-makers, this trajectory matters because it establishes a realistic growth ceiling and floor. The 3.5% CAGR is not a headline-grabbing figure, but it carries significant strategic weight: it implies that market share gains, capacity optimization, and formulation agility will be the true differentiators rather than broad-based demand surges. Companies that treat the market as flat risk underinvesting in product readiness, while those that overindex on aggressive volume assumptions may misallocate capital. This report anchors those decisions in a structured, scenario-aware lens.
Segmentation Architecture: Where Value Is Created and Captured
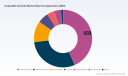
The analytical depth of this study begins with a granular segmentation framework that dissects demand across type, application, and region. Rather than treating isoparaffin solvents as a monolith, the report isolates how different carbon-range families—spanning lighter C8-C9 streams, mid-range C10-C12 grades, heavier C13-C14 formulations, and other specialized variants—map to distinct performance requirements and end-use economics. This type-level breakdown is essential for sourcing teams evaluating compatibility, evaporation profiles, and regulatory fit across coatings, cleaning, and personal care systems.
Application-level analysis further sharpens the picture. The research quantifies how paints and coatings continue to serve as a dominant demand anchor, while metalworking fluids, agrochemicals, cleaning formulations, pharmaceuticals, personal care, and other niche applications each present differentiated growth drivers and technical constraints. By separating these verticals, the report equips formulators and procurement leaders with the context needed to anticipate substitution cycles, purity thresholds, and odor control expectations that vary significantly by use case.
Regional distribution is similarly structured to reveal how demand concentrates across northern hemisphere industrial hubs, european compliance-driven markets, asia-pacific manufacturing intensity, and emerging activity in latin america and the mideast and africa. The report's regional architecture does not merely allocate percentages; it interrogates why certain geographies exhibit stronger pull factors, how logistics and feedstock proximity influence cost structures, and where regulatory calendars are likely to accelerate or dampen adoption timelines. This multi-dimensional segmentation is the backbone of the study's actionable recommendations, enabling readers to align product portfolios, inventory strategies, and partnership models with the pockets of highest marginal value.
Isoparaffin Solvents Market
Regulatory Dynamics and Feedstock Realities Reshaping the Landscape
No strategic assessment of the isoparaffin solvents market is complete without confronting the twin forces of compliance and input volatility. Over the 2023–2025 period, regulatory tightening has become a central market dynamic rather than a peripheral risk. South American jurisdictions, including Brazil and Argentina, have moved to tighten VOC emission standards, mandating reduced aromatic content across paints, coatings, and adhesives. In parallel, U.S. EPA VOC limits and the EU Solvent Emissions Directive continue to steer formulators toward high-purity isoparaffin grades as compliant alternatives to traditional aromatic solvents. These frameworks are not static; they are incrementally raising the performance bar for solvent suppliers and rewarding manufacturers who can demonstrate low-aromatic, low-odor, and low-impurity profiles at scale.
Shell Chemicals embodied this regulatory tailwind in 2025 by unveiling an expanded portfolio of high-purity, low-carbon isoparaffin solvents designed to meet tightening environmental compliance. Such portfolio expansions signal more than marketing posture; they reflect capital allocation toward grades that satisfy both performance and compliance criteria simultaneously. The broader implication for 2026 is clear: regulatory alignment is increasingly inseparable from commercial viability. Brands and converters that evaluate solvent suppliers solely on price per liter risk downstream reformulation costs, compliance exposure, and reputational friction.
Feedstock volatility, meanwhile, introduces a persistent margin tension. Isoparaffin solvents remain sensitive to hydrocarbon feedstock pricing and supply disruptions, which can compress production economics and alter competitive cost positioning. The report integrates these raw-material dynamics into its forecasting logic, allowing readers to stress-test pricing assumptions against plausible input-cost scenarios. By coupling regulatory timelines with feedstock sensitivity analysis, the study transforms what is often treated as an external shock into a manageable planning variable.
Competitive Landscape: Established Majors and Strategic Capacity Moves
The competitive field in isoparaffin solvents is defined by a concentrated but diversified set of global producers, each leveraging distinct feedstock positions, regional footprints, and brand portfolios. Shell plc remains a leading supplier through its ShellSol isoparaffins, high-purity synthetic hydrocarbon solvents characterized by narrow boiling ranges and low impurities, with applications spanning coatings, inks, dry cleaning, and industrial uses. Chevron Phillips Chemical Company continues to manufacture Soltrol isoparaffin solvents, including Soltrol 130, a low-odor grade compatible with parts cleaning, degreasing, paints, inks, and agrochemical formulations. Exxon Mobil Corporation produces the Isopar brand of high-purity isoparaffinic fluids for personal care, coatings, cleaning, and metalworking, emphasizing low aromatic content and odorless properties.
Beyond these major anchors, the market features a capable tier of regional and specialized producers. Braskem S.A. contributes isoparaffinic hydrocarbon solvents within its broader industrial and specialty portfolio. TotalEnergies SE supplies isoparaffin solvents across paints, coatings, and formulations. INEOS Group produces isoparaffins for industrial cleaning, coatings, and personal care applications. Idemitsu Kosan Co., Ltd. offers IP Clean and IP Solvent products for industrial and specialty uses. Calumet Specialty Products Partners, L.P. focuses on isoparaffinic solvents for hydrocarbon applications in industrial cleaning and coatings. Sasol Limited manufacturers isoparaffin-based solvents as part of its chemical portfolio, and SK Global Chemical produces ISOL isoparaffins for industrial solvents and formulations.
Market concentration metrics underscore the structural balance between incumbency and opportunity: a CR3 of approximately 28.3% and a CR5 of about 32.1% indicate a landscape where top-tier players hold meaningful share while ample room remains for differentiated positioning, specialty grades, and regional service excellence. This concentration profile matters for 2026 strategy because it suggests that competitive advantage will increasingly accrue to firms that combine technical reliability with agile compliance readiness, rather than those competing solely on volume.
Recent corporate developments reinforce this interpretation. In February 2025, Shell Chemicals inaugurated a new isoparaffin solvent production plant in Brazil, increasing local capacity by 30%. That same spring, Chevron Phillips Chemical Company increased its manufacturing capacity for isoparaffin solvents. By mid-2025, ExxonMobil Chemical updated the technical datasheet for Isopar M, highlighting low aromatic content, and Shell Chemicals released an updated product datasheet for ShellSol emphasizing low odor and suitability for surface coatings. These moves—capacity additions, datasheet refreshes, and regional expansions—are not isolated events; they are coordinated signals of where incumbents are placing bets on demand, compliance, and application performance. The report maps these developments against demand pockets and regulatory calendars, helping readers distinguish between routine capacity updates and strategically significant market repositioning.
What the Report Delivers: Operational Intelligence for 2026 Planning
This study is structured to convert macro insight into operational clarity. The report combines historical reconstruction with forward-looking forecasts, segmentation analysis, competitive profiling, and regulatory mapping into a unified decision-support framework. Specifically, readers gain access to:
- A multi-year market size and CAGR trajectory that anchors volume and revenue expectations across the forecast window, enabling scenario planning for production, inventory, and capital allocation.
- Segment-level analysis by type and application that clarifies where purity, odor, boiling range, and compatibility requirements drive premium positioning and where cost-competitive grades retain relevance.
- Regional demand distribution that highlights where compliance calendars, manufacturing intensity, and feedstock logistics converge to shape cost and availability dynamics.
- A competitive landscape assessment covering major and specialized producers, including capacity moves, product updates, and portfolio expansions that signal shifting supply-side priorities.
- Regulatory and raw-material context that integrates VOC standards, aromatic-content mandates, and feedstock volatility into planning assumptions rather than treating them as external noise.
- Actionable interpretative guidance for procurement, formulation, market entry, and partnership decisions, tailored to the realities of a moderately growing but compliance-sensitive market.
Importantly, the full report goes beyond the summary figures and qualitative themes previewed here. It provides the detailed split data, forecast tables, and segment-by-segment interpretations that procurement and strategy teams need to validate internal assumptions, benchmark supplier proposals, and prioritize investment across grades and geographies. The executive summary and preview narrative are designed to establish trust and demonstrate analytical rigor; the complete dataset and methodology are reserved for the full study, ensuring that subscribers receive the depth required for board-level and operational decision-making.
Solvent Naphtha Market
Why This Research Matters for 2026 Strategic Decisions
As organizations enter 2026 planning cycles, the isoparaffin solvents market presents a classic strategic paradox: growth is steady but unspectacular, compliance pressure is rising but predictable, and competitive differentiation is increasingly technical rather than transactional. In such environments, the cost of imprecise intelligence is high. Overbuying low-demand grades ties up working capital; underinvesting in compliant, low-aromatic portfolios exposes formulators to regulatory and customer-requirement risk; and misreading regional capacity shifts can leave supply chains exposed to localized constraints.
This report is built to reduce that uncertainty. By fusing historical performance, forecast logic, segmentation detail, competitive signaling, and regulatory context into a single coherent architecture, it gives decision-makers a shared reference point for conversations across procurement, R&D, sales, and finance. The 3.5% CAGR and the multi-year size progression provide a realistic growth baseline; the segmentation framework identifies where value concentrates; the competitive and regulatory mapping reveals where incumbents are investing and where compliance will reshape demand; and the operational guidance translates all of this into planning-relevant choices.
For leaders who need to move from awareness to action, the full study offers the granular evidence base required to set grade strategies, evaluate supplier roadmaps, anticipate reformulation triggers, and align capacity or sourcing decisions with the regions and applications most likely to reward precision. The preview presented here demonstrates the analytical standard and the strategic lens of the research; the complete report delivers the execution-ready intelligence that turns that lens into decisions.
For detailed analysis of this topic, please visit the official page: Isoparaffin Solvents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Engine-Driven Welders Market Hits $1,380M in 2025, Forecast 4.91% CAGR to 2032
By pmarketresearch, 2026-09-15
The Engine-Driven Welders Market: Strategic Intelligence for the 2026 Decision-Maker
The industrial equipment landscape is undergoing a quiet but decisive transformation. As infrastructure projects multiply across emerging economies and legacy assets in developed markets demand intensive rehabilitation, the demand for reliable, mobile power and welding solutions has never been more critical. For executives in manufacturing, procurement, and strategic planning, navigating this space requires more than surface-level consumption forecasts. It demands a rigorous understanding of engine technology adoption, regional demand shifts, regulatory pressures, and the competitive maneuvers shaping the next seven years of market evolution.
PW Consulting's latest research initiative delivers a comprehensive, forward-looking analysis of the Global Engine-Driven Welders Market. Anchored in historical data spanning 2020 through 2025 and projecting through 2032, this report provides the analytical rigor necessary to allocate capital, refine product roadmaps, and anticipate competitive disruption. What follows is an executive preview of the market architecture, the forces driving its trajectory, and the proprietary analytical frameworks embedded within our full publication.
A Market Navigating Growth and Structural Realignment
Over the past half-decade, the engine-driven welders sector has demonstrated remarkable resilience, rebounding from supply chain bottlenecks and transitioning into a phase of measured, sustainable expansion. Current market valuations reflect a maturing industry that has successfully absorbed post-pandemic operational adjustments while capitalizing on the global construction and energy pipeline boom. The research models a clear upward trajectory, with total market revenue positioning itself for steady accumulation through the end of the forecast period.
At the core of this forecast lies a moderate yet consistent compounding growth rate, signaling an industry that is expanding beyond cyclical volatility and settling into a pattern driven by fundamental industrial demand, technological refinement, and strategic fleet modernization. Decision-makers will find that the growth narrative is not monolithic; rather, it is segmented by propulsion technology preferences, regional economic priorities, and application-specific operational requirements. Our analysis deconstructs these layers to reveal where value creation is most concentrated and where margin pressures may emerge.
Welding Equipment Market
Crucially, the report does not merely project headline numbers. It maps the underlying demand vectors, correlating equipment adoption rates with macroeconomic indicators, project financing cycles, and evolving on-site labor economics. By isolating these dynamics, we provide leadership teams with a diagnostic lens to stress-test their market assumptions and align their strategies with the components of growth that are most sustainable.
Technological Divergence and the Mobility Imperative
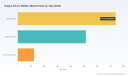
The modern engine-driven welder category is defined by a fundamental operational trade-off: portability and self-sufficiency versus fuel efficiency and emissions compliance. Within this tension, manufacturers are pursuing divergent engineering philosophies. Diesel-powered platforms continue to anchor heavy-duty and remote operations, capitalizing on torque reliability and extended runtime capabilities. Gasoline-driven units maintain strong footholds in lighter commercial and maintenance applications, where rapid deployment and lower upfront costs drive purchasing decisions. Meanwhile, LPG-fueled alternatives are carving out niche positioning, particularly in markets with stringent indoor or urban emissions regulations.
This technological segmentation is not merely a product classification exercise; it represents a strategic fork in the roadmap for equipment manufacturers and fleet operators alike. The research evaluates how engine architecture choices interact with total cost of ownership, service interval economics, and regional fuel availability. For procurement leaders, understanding the operational profile of each propulsion type is essential when aligning equipment specifications with project duration, site logistics, and local compliance frameworks.
Furthermore, the integration of auxiliary power generation into welding platforms has transformed these machines from single-purpose tools into multi-role assets. On active jobsites, this convergence directly reduces the logistical footprint of supporting equipment and mitigates the need for separate generator rentals. Our analysis quantifies the operational efficiency gains that arise from this consolidation, demonstrating how labor allocation and equipment utilization metrics shift when welding and power generation are unified into a single mobile unit.
Regulatory Pressure, Raw Material Volatility, and Operational Resilience
The engine-driven welders market operates at the intersection of mechanical engineering, emissions regulation, and commodity economics. Manufacturers and end-users alike must navigate an increasingly complex compliance environment, particularly in jurisdictions where engine emissions standards are tightening to align with broader environmental policy objectives. Recent product developments from leading OEMs highlight a clear industry response: new platform introductions are being engineered from the ground up to meet rigorous duty-cycle requirements while maintaining compact footprints suitable for service vehicles and confined job site logistics.
Simultaneously, raw material cost fluctuations remain a persistent variable in the manufacturing equation. Alternator components, control electronics, and engine subsystems are subject to supply chain pricing dynamics that ripple directly into production margins and, ultimately, end-user pricing strategies. The report incorporates scenario modeling that accounts for these input cost pressures, enabling readers to assess how different procurement and pricing architectures may hold up under periods of commodity volatility.
For competitive strategists, the regulatory and input-cost environment is not merely a constraint; it is a source of differentiation. Companies that can streamline compliance engineering, localize assembly where advantageous, and optimize bill-of-materials resilience are positioned to capture pricing power and market share. Our analysis highlights how the leading participants are structuring their operational responses to these external pressures, offering a template for evaluating internal capability gaps.
Competitive Architecture: Navigating an Oligopolistic Landscape
The competitive structure of this market is characterized by a high degree of concentration among established equipment manufacturers, with a handful of multinational players commanding a substantial share of industry revenue. This oligopolistic dynamic creates a market environment where brand recognition, service network density, and product lineage play decisive roles in procurement decisions. However, it also presents opportunities for focused differentiation, particularly among regional specialists and agile OEMs that can adapt quickly to localized application requirements and emerging market niches.
Our competitive profiling extends well beyond corporate biographies. The research evaluates each major participant through the lens of product architecture, engine partnerships, geographic assembly strategies, and end-market specialization. Large-cap manufacturers have historically leveraged established distribution channels and bundled service offerings to sustain market leadership, while mid-tier and regional producers have pursued competitive advantage through compact design optimization, fuel efficiency claims, and targeted deployment in agricultural, field-service, and export-oriented applications.
The report further examines the strategic significance of recent product launches that signal the industry's direction. New-generation platforms are increasingly emphasizing advanced arc performance, expanded generator capacity, and duty-cycle robustness tailored to harsh construction and industrial environments. These introductions reflect a broader market consensus: the next wave of competitive advantage will belong to manufacturers that can deliver high-utilization reliability without compromising mobility or compliance readiness. By mapping these product strategies against regional demand profiles, our analysis provides a tactical view of where competitive intensity is likely to escalate and where whitespace may still exist.
For strategic planners, understanding the concentration of market power is essential. The research provides a detailed assessment of how incumbent players are defending their positions through product portfolio breadth, technology licensing, and service ecosystem expansion, as well as where acquisition, partnership, or geographic entry strategies may reshape the competitive hierarchy over the forecast horizon.
Demand Vector: Where the Market Finds Its Pulse
The application landscape for engine-driven welders is diverse, stretching across heavy civil construction, pipeline installation and maintenance, mining operations, and broader infrastructure development. Each application segment carries distinct operational requirements, utilization patterns, and procurement cycles. In construction environments, for example, the ability to deploy self-contained power and welding capability directly to intermittent work zones translates into measurable efficiency gains. Pipeline and energy-sector projects demand equipment that can sustain prolonged duty cycles under remote or extreme conditions. Mining operations, meanwhile, prioritize fuel endurance, ruggedness, and compatibility with existing fleet logistics.
Our segmentation analysis isolates these application-specific drivers to reveal which end-use categories are generating the most consistent revenue streams and which are most sensitive to macroeconomic cycles or commodity price fluctuations. Rather than presenting static splits, the report contextualizes each application's growth potential within the broader framework of project financing, labor availability, and equipment utilization economics. Readers will gain a nuanced view of where fleet replacement demand, incremental capacity expansion, and new-project initiation are converging to drive volume.
Regional demand patterns are examined with equal rigor. The study evaluates how varying rates of infrastructure investment, energy sector activity, and industrial modernization shape geographic consumption profiles. By correlating regional project pipelines with equipment specification trends, the research identifies markets where localized assembly, distribution partnerships, or tailored product configurations may offer the highest strategic return. These insights are particularly valuable for organizations considering geographic expansion, export strategy refinement, or regional supply chain reconfiguration.
Report Architecture: Operational Intelligence for Strategic Execution
The full PW Consulting publication is engineered to be a working document, not merely a reference summary. Its architecture is designed to support cross-functional decision-making across product management, sales leadership, procurement, and corporate strategy. The report integrates quantitative market modeling with qualitative competitive assessment, delivering a unified view of market behavior and structural risk.
Core components of the analysis include a detailed historical reconstruction of market revenue dynamics from 2020 through 2025, a transparent demand-side forecast extending through 2032, and a segment-level diagnostic that maps propulsion technology preferences, application utilization profiles, and geographic consumption patterns. The research also incorporates a rigorous competitive benchmarking framework, profiling leading manufacturers and their strategic postures, recent product introductions, and regional assembly or distribution strategies.
In addition to market sizing and segmentation, the publication delivers forward-looking assessments of regulatory trajectory, input-cost exposure, and labor economics that directly influence equipment adoption. Scenario modeling is embedded throughout, enabling readers to evaluate how changes in compliance requirements, fuel pricing, or project financing conditions may alter demand momentum. The result is an analytical toolkit that can be applied to capital planning, product roadmap prioritization, pricing strategy, and market-entry evaluation.
Executive summaries, graphical data representations, and structured competitor matrices are integrated to ensure rapid assimilation of key insights, while the underlying methodology and source documentation provide the audit trail necessary for internal validation and board-level review.
Engine-Driven Welders Market
Strategic Takeaways for 2026 and Beyond
The engine-driven welders market is entering a phase where disciplined strategic positioning will separate long-term winners from reactive participants. Several high-level implications emerge clearly from our analysis. First, the market's growth trajectory is anchored in structural industrial demand rather than speculative cycles, creating a favorable environment for product innovation and service-led revenue expansion. Second, competitive differentiation will increasingly depend on the ability to balance compliance readiness, fuel efficiency, and field durability without sacrificing portability or total cost competitiveness.
Third, the concentration of market power among leading OEMs does not preclude opportunity; it reframes it. Regional specialists, export-focused manufacturers, and entrants with differentiated product configurations can capture value by serving application segments or geographic pockets where incumbent coverage is less dense or where localized assembly and service models confer a decisive advantage. Finally, the integration of labor-saving functionality, auxiliary power capability, and compliance-forward engineering is not a peripheral feature set; it is becoming a central purchasing criterion that will shape procurement specifications and fleet replacement cycles for years to come.
For decision-makers preparing their 2026 portfolios, the imperative is clear: base strategic commitments on granular, forward-validated market intelligence rather than on aggregate industry narratives.
Accessing the Full Research Intelligence
This article offers a strategic preview of the market architecture, competitive dynamics, and operational forces shaping the engine-driven welders sector. The underlying research contains a far more granular dissection of market sizing, segment-level demand modeling, competitive benchmarking, regulatory scenario mapping, and regional consumption diagnostics. Those detailed breakdowns are essential for calibrating investment thresholds, prioritizing product development, and validating market-entry assumptions.
To access the complete dataset, forecast tables, competitor profiles, and scenario frameworks, we invite you to consult the full PW Consulting Engine-Driven Welders Market research publication. The complete report provides the analytical depth required to translate market awareness into executable strategy.
For detailed analysis of this topic, please visit the official page: Engine-Driven Welders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Air Ambulance Market to Hit $29.63B by 2032 at 8.5% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Air Ambulance Sector: Navigating the 2026-2032 Growth Trajectory
The air ambulance industry stands at a critical inflection point. As healthcare systems worldwide grapple with aging demographics, rising trauma incidence, and the persistent need for rapid critical care transport, the operational and financial landscape has never demanded sharper strategic vision. At PW Consulting, our latest comprehensive market study on the Air Ambulance sector is engineered not merely as a data repository, but as a decision-making architecture for executives, investors, and operational leaders preparing for the 2026 fiscal cycle and beyond. This introduction outlines the strategic scaffolding of the research, the macroeconomic forces reshaping operational models, and the precise analytical lenses we have applied to decode a market defined by both clinical urgency and commercial complexity.
Market Trajectory and the Strategic Imperative of 2026
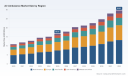
Historical performance provides the baseline for forward planning. Between 2020 and 2025, the sector expanded from approximately 10.92 billion USD to 16.75 billion USD, reflecting a compound trajectory driven by increased emergency transport volumes, expanded service coverage into underserved geographic zones, and the gradual institutionalization of air medical logistics within regional healthcare networks. Looking ahead, our forecast window extends through 2032, with the market projected to reach 29.63 billion USD by the terminal year of our model. This expansion is underpinned by an 8.5 percent CAGR, a rate that signals sustained structural growth rather than cyclical fluctuation.
For enterprise decision-makers, the 2026 baseline carries specific operational weight. The transition from retrospective analysis to forward-looking allocation requires a clear understanding of how demand signals are shifting across transport models, aircraft configurations, and geographic delivery networks. Our research isolates these vectors without fragmenting them into isolated percentages, ensuring that leadership teams can map capital deployment, fleet modernization, and partnership strategies against a cohesive growth narrative. The key is recognizing that revenue scaling in this sector is rarely linear; it is mediated by regulatory compliance, reimbursement predictability, workforce availability, and regional infrastructure readiness. The study is designed to translate these interdependencies into actionable planning frameworks.
Operating Environment and Structural Dynamics
The commercial reality of air ambulance operations is shaped by intersecting forces that extend far beyond flight hours or base locations. Reimbursement architecture, for instance, has undergone meaningful recalibration. In 2025, the Centers for Medicare and Medicaid Services finalized updated reimbursement schedules for air ambulance transport, delivering greater cost certainty for both independent operators and hospital-affiliated programs. This stability is critical for long-cycle capital planning, particularly for organizations considering fleet refresh cycles or new base activations. Yet reimbursement clarity does not eliminate financial friction; it merely changes the shape of the planning exercise.
Regulatory frameworks add another layer of operational discipline. The No Surprises Act, enforced from 2022, prohibits balance billing by air ambulance operators and mandates the submission of detailed transport and medical cost data to the Department of Health and Human Services. Compliance is not a static checkbox; it is an ongoing data governance requirement that influences billing systems, clinical documentation workflows, and cross-jurisdictional transport protocols. Simultaneously, the Federal Aviation Administration continues to enforce safety standards, including CAMTS accreditation expectations and enhanced data collection obligations. These requirements compress operational margins in the short term while simultaneously elevating the barrier to entry for under-resourced competitors, a dynamic that quietly reshapes competitive positioning over multi-year horizons.
Emergency Ambulance Market
Cost structure remains a defining constraint. Air ambulance transport demands specialized medical personnel, including flight nurses and paramedics, maintained on continuous duty rotations to support 24/7 readiness. This staffing architecture, combined with aircraft maintenance, fuel volatility, and insurance exposure, contributes to median single-transport costs that consistently reside in the 36,000 to 40,000 USD range. Managing this cost stack while preserving mission readiness is one of the central operational tensions the market must navigate. Our analysis treats cost management not as a standalone efficiency exercise, but as a strategic variable that interacts with service model design, fleet mix optimization, and regional demand density.
Competitive Landscape and Strategic Positioning
The industry is characterized by a concentrated core alongside a diverse periphery of specialized operators, regional providers, and affiliated network models. Concentration metrics indicate that the top three firms command approximately 52.6 percent of market revenue, while the top five extend reach to roughly 65.2 percent. This concentration does not imply uniformity; rather, it reflects divergent strategic playbooks operating within the same clinical mandate.
Several organizations anchor the competitive landscape through distinct operational propositions. Air Methods, headquartered in Greenwood Village, Colorado, positions itself as a leading provider of emergency air medical services, deploying critical care clinicians for trauma, cardiac, pediatric, and burn transports across 48 states via helicopter and fixed-wing fleets. The company's recent activity illustrates the strategic tools available to scale leaders: a fleet expansion initiative announced in early 2026 to add nearly 50 aircraft, a network partnership with HCA Florida Healthcare to launch enhanced critical care access in North Central Florida, and a 10-year air ambulance services contract with the Government of Yukon and Alkan Air valued at approximately 157 million USD. These moves span capacity deployment, institutional partnership, and regional contracting, demonstrating how leading operators sequence growth across multiple vectors.
Air Ambulance Market
Global Medical Response, based in Lewisville, Texas, emphasizes an integrated ground and air medical transport model, encompassing emergency response and inter-facility patient relocation supported by clinical teams. This integration strategy reflects a broader industry logic: reducing handoff friction, expanding geographic coverage, and aligning transport modality with clinical acuity rather than defaulting to a single vehicle type. PHI Air Medical, operating from Tempe, Arizona, runs a national footprint with more than 100 helicopters across 80-plus bases, delivering 24/7 critical care transport alongside membership programs that provide out-of-pocket protection for patients. The membership layer is strategically significant because it introduces a recurring revenue and demand-smoothing mechanism that partially decouples financial exposure from episodic utilization.
REVA Air Ambulance, headquartered in Fort Lauderdale, Florida, occupies a specialized fixed-wing niche as the world's largest dedicated fixed-wing jet air ambulance operator, providing 24/7 bedside-to-bedside ICU-level medical transport across North and South America. Its positioning highlights the strategic value of long-range, high-acuity transport in an increasingly interconnected patient referral environment. Acadian Companies, based in Lafayette, Louisiana, operates its Air Med division to deliver helicopter and fixed-wing emergency and inter-facility transport across rural Louisiana and surrounding states, illustrating how regional density, familiarity with local healthcare ecosystems, and rapid response protocols can sustain competitive relevance outside national-scale playbooks. AirMedCare Network, located in West Plains, Missouri, functions as the largest air ambulance membership network, providing financial protection and access to affiliated providers, including Air Evac Lifeteam and REACH, for emergency and non-emergency rotor and fixed-wing transports. Its model demonstrates how network aggregation can create patient access at scale while distributing operational execution across affiliated entities.
Understanding how these players diverge in fleet composition, service model emphasis, geographic coverage, and membership integration is essential for any market participant evaluating partnership opportunities, competitive benchmarking, or market entry prerequisites. The research dissects these strategic postures without reducing them to static snapshots, instead mapping how each operator's choices interact with reimbursement predictability, regulatory compliance costs, and regional demand elasticity.
Research Architecture and Actionable Intelligence
Our study is structured to convert macro trends into operational decision support. The report begins with a comprehensive market sizing and trajectory analysis, anchoring leadership planning in a transparent 2020 to 2025 historical baseline and a 2026 to 2032 forecast window. From there, the analysis layers in service model dynamics, aircraft type deployment logic, and regional delivery patterns, with the intent of revealing how demand flows through different operational architectures rather than simply reporting where it lands.
The competitive section profiles the core operators shaping the industry's direction, examining strategic posture, fleet and base considerations, partnership patterns, and membership or network strategies where relevant. These profiles are paired with a recent developments tracking module that captures the cadence of real-world moves: network launches, contract expansions, fleet additions, and institutional partnerships. For decision-makers, this sequence matters because market positioning is often established through a series of coordinated actions rather than a single announcement. Tracking that sequence allows organizations to anticipate competitor capacity adjustments, partnership clustering, and geographic focus shifts before they become fully visible in headline metrics.
A dedicated dynamics section integrates the regulatory and reimbursement environment, including the operational implications of the No Surprises Act, CMS reimbursement updates, FAA safety and accreditation requirements, and the labor cost architecture that underpins per-transport economics. This section is written for practitioners who must reconcile compliance obligations with cost management, fleet utilization, and service availability targets. By linking regulatory and reimbursement developments to operational workflow and financial planning, the research helps organizations avoid the common pitfall of treating compliance as an isolated legal function rather than a strategic input to service design.
The report also addresses segmentation logic in a manner suited to strategic planning. Rather than fragmenting the narrative into narrow numerical slices, we analyze how hospital-based and community-based service models, rotary-wing and fixed-wing platforms, and regional delivery variations interact with demand patterns, reimbursement behavior, and operational readiness. This approach equips executives to evaluate portfolio mix, capacity allocation, and partnership structures with a clear understanding of which configurations are best suited to high-acuity emergency response, inter-facility relocation, long-range transport, or membership-supported demand stabilization.
Translating Intelligence into 2026 Decision-Making
As organizations move into 2026, the strategic questions facing air ambulance operators, healthcare systems, investors, and policy-adjacent stakeholders are converging. How should fleet modernization be sequenced against reimbursement certainty and maintenance cycle economics? Where should new bases or partnership hubs be placed to capture demand without overextending fixed-cost structures? How can service model design balance hospital-based integration with community-based reach? What membership or financial protection mechanisms can smooth utilization volatility while preserving clinical access? And how should organizations interpret competitor activity, regulatory shifts, and reimbursement updates as a combined signal rather than a set of disconnected events?
Answering these questions requires a research instrument that is both broad enough to capture systemic dynamics and precise enough to inform capital and operational choices. Our Air Ambulance market study is built for that purpose. It synthesizes historical performance, forward-looking trajectory, competitive positioning, and regulatory context into a single decision framework, enabling leadership teams to test scenarios, prioritize investments, and calibrate risk exposure with a shared analytical foundation.
The full study contains the detailed segmentation logic, competitor profiles, recent development timelines, and scenario-ready analytical tables that executives need to move from directional insight to implementation planning. If your organization is preparing capability expansions, evaluating partnership structures, assessing competitive exposure, or mapping reimbursement-aware operational strategy, the complete research package provides the granularity required to act with confidence. We invite you to access the full report to explore the complete market intelligence, detailed segmentation analysis, and strategic planning toolkit designed specifically for 2026 decision-making and the multi-year horizon that follows.
For detailed analysis of this topic, please visit the official page: Air Ambulance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cheque Scanner Market Hits $1B in 2025, Projects 5.6% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence in the Cheque Scanner Market: Navigating the 2026 Digital Banking Transformation
The global financial infrastructure is undergoing a decisive shift toward automation, driven by regulatory mandates, operational efficiency imperatives, and the accelerating adoption of remote deposit capture. As enterprises across banking, retail, and corporate treasury functions reassess their document imaging architectures, the cheque scanner market has emerged as a critical enabler of next-generation capture ecosystems. PW Consulting’s latest strategic research on this sector provides decision-makers with a rigorous, forward-looking intelligence framework designed to inform capital allocation, technology procurement, and competitive positioning throughout the 2026–2032 forecast horizon. This article outlines the analytical architecture of the study and explains why its findings carry immediate strategic weight for executive teams operating in a rapidly consolidating hardware landscape.
Market Architecture and Growth Trajectory
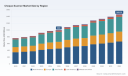
The cheque scanner market has demonstrated sustained expansion over the past half-decade, reflecting a structural transition from manual processing to automated, image-centric workflows. Drawing on historical performance data from 2020 through 2025, the sector has consistently outpaced broader peripheral equipment segments, supported by institutional digitization programs and compliance-driven infrastructure refresh cycles. The base year valuation sits at approximately one billion USD in annual revenue, with the trajectory accelerating into the forecast period. Our analysis projects compound annual growth through 2032, anchored by recurring enterprise refresh demand, expanding distributed capture deployments, and the gradual retirement of legacy single-function imaging devices.
This growth profile is not uniform. Macro-level expansion is shaped by intersecting forces: the maturation of image-based clearing frameworks, the standardization of transmission protocols, and the financial sector’s ongoing push to compress check processing cycles. Institutions are deploying capture hardware across branch networks, back-office operations, and remote deposit environments to satisfy regulatory expectations while reducing handling overhead. The resulting demand pattern favors vendors that can deliver reliable MICR reading, high-throughput imaging, and seamless integration with existing banking software stacks. Our research isolates these demand drivers and maps them against procurement cycles, depreciation schedules, and regional adoption curves to provide a clear operational horizon for strategic planning.
Importantly, the market remains moderately fragmented at the top tier, with leading participants commanding a combined share that leaves substantial runway for specialized players and integrated solution providers. This concentration dynamic creates both competitive tension and partnership opportunities, particularly as enterprises seek bundled capture-and-software offerings rather than standalone hardware. The report dissects these structural characteristics without relying on static snapshots, instead emphasizing the kinetic forces that will reshape vendor positioning, pricing power, and service-level expectations over the next several years.
Industry Dynamics Redefining Procurement and Deployment
The cheque scanner market does not operate in a vacuum. Its evolution is tethered to regulatory architectures that define image quality thresholds, retention requirements, and transmission standards. Frameworks established under the Check Clearing for the 21st Century Act have institutionalized image-based clearing, compelling participating institutions to maintain robust image retention capabilities and adopt standardized exchange protocols. Parallel guidelines from federal reserve authorities have codified minimum image quality specifications, converting technical compliance into a baseline procurement requirement rather than a differentiated feature. For procurement leaders, these mandates reshape vendor evaluation criteria, shifting emphasis from raw scanning speed to certification readiness, image fidelity consistency, and long-term software compatibility.
Beyond regulation, operational economics are accelerating hardware refresh. U.S. banks and financial institutions process and clear a substantial volume of checks each day, and branch-level scanner installations have become a pragmatic response to two pressures: shortening clearing timelines and aligning with government initiatives that encourage digital check workflows. The resulting deployment pattern is increasingly distributed. Rather than concentrating capture capacity in centralized operations centers, organizations are extending intelligent scanning to teller stations, remote deposit workflows, and back-office reconciliation points. This decentralization favors form factors that minimize footprint, simplify maintenance, and integrate cleanly with network imaging pipelines.
These dynamics are already visible in the product pipeline. Recent introductions highlight a clear industry direction: ultraviolet imaging enhancements, zero-footprint designs, and streamlined operator interfaces that reduce training friction and accelerate throughput. Suppliers are also refining network-enabled models that support centralized management across dispersed branch fleets. The strategic implication is straightforward. Engineering roadmaps are converging on reliability, compliance alignment, and deployment simplicity, while differentiation is increasingly expressed through software integration, service support, and reseller distribution reach. Our analysis tracks these product evolution patterns and correlates them with enterprise adoption readiness, enabling buyers to anticipate replacement cycles and providers to calibrate portfolio investments.
Competitive Landscape: Positioning, Product Portfolios, and Strategic Posture
The competitive field in cheque scanning is anchored by established manufacturers and imaging specialists that have built reputations around throughput reliability, MICR accuracy, and ecosystem compatibility. Market participants span specialized check capture vendors, broader office and financial imaging companies, and platform integrators that embed scanner hardware within larger retail and banking capture systems. The report evaluates these players through a multi-dimensional lens, assessing product line breadth, target workflow coverage, geographic distribution strength, and recent portfolio movements.
Cheque Scanner Market
Digital Check Corp. continues to emphasize teller capture, remote deposit, and high-volume production imaging, with recent product activity underscoring a transition toward next-generation ultraviolet-capable models and compact network-friendly configurations. Panini S.p.A. has built a strong presence in distributed check capture and remote deposit applications, leveraging intelligent scanner architectures designed for branch and back-office environments. Epson America, Inc. addresses desktop capture requirements with MICR reading and RDC/back-office features, while Canon U.S.A., Inc. supplies imageFORMULA CR-series devices that span desktop and check transport imaging scenarios. ARCA Tech Systems, LLC and RDM Corporation contribute specialized teller and remote deposit capture solutions, alongside network-enabled models for image capture and MICR applications. NCR Voyix Corporation extends the landscape by integrating scanner hardware with broader banking and retail capture systems, positioning at the intersection of hardware and workflow orchestration.
Recent activity among these participants reveals a market that is simultaneously consolidating around core imaging standards and experimenting with form-factor efficiency. Product launches and catalog updates signal a focus on ultraviolet imaging fidelity, compact physical design, and simplified operator interaction. These developments matter because they influence total cost of ownership, branch-level deployment speed, and the practical ease of fleet management across geographically dispersed locations. The research integrates these product movements with channel dynamics, credentialing requirements, and integration complexity to help stakeholders anticipate which vendor profiles will gain traction in specific procurement contexts.
What the Research Delivers: Analytical Depth and Decision-Ready Outputs
PW Consulting’s Cheque Scanner Market study is structured to translate market complexity into actionable intelligence. Rather than offering a static sizing table, the report builds a layered analytical model that connects historical performance, regulatory pressure, product evolution, and competitive behavior to a coherent forward view. The following components define the core value of the study for executive and operational audiences:
- Macro-market sizing and trajectory analysis covering historical performance through the base year and a multi-year forecast horizon, with growth characterized across compound annual rates and volume-driven demand shifts.
- Segment-level decomposition that examines how different device architectures and use-case environments contribute to demand formation, enabling readers to understand where growth concentrates and which deployment models are gaining operational preference.
- Regional demand mapping that situates adoption intensity, infrastructure maturity, and compliance-driven procurement across major geographic corridors, without reducing complex market behavior to oversimplified share comparisons.
- Competitive profiling of leading manufacturers and platform integrators, including headquarters location, core product families, target application coverage, and recent portfolio or product-launch activity, supporting vendor selection and partnership evaluation.
- Regulatory and operational context integration that ties image-clearing frameworks, federal image-quality guidance, and branch-level process optimization to procurement timing and hardware specification priorities.
- Strategic scenario considerations that help decision-makers assess replacement cycles, fleet standardization opportunities, and integration requirements as enterprises expand distributed capture networks.
Each analytical section is designed to support a specific decision context. Procurement teams can use the segmentation and product-portfolio analysis to align hardware specifications with workflow requirements and compliance expectations. Strategy and corporate development groups can leverage competitive positioning and market-concentration insights to evaluate partnership opportunities, channel strategies, and potential consolidation pathways. Technology leaders can incorporate the regulatory and operational context into architecture planning, ensuring that capture hardware choices remain compatible with image retention mandates and standardized transmission protocols.
Strategic Relevance for 2026 Decision-Making
The 2026 planning cycle is a pivotal moment for organizations that rely on check imaging and document capture. Several converging factors make timely, structured intelligence essential. First, regulatory expectations around image quality and retention have moved from abstract compliance goals to concrete procurement criteria, meaning that hardware selection now carries operational and legal implications. Second, the shift toward distributed capture and remote deposit workflows is expanding the number of deployment points where scanner performance, footprint, and manageability directly affect branch efficiency. Third, product roadmaps are increasingly emphasizing compact design, ultraviolet imaging capabilities, and network-oriented management features, which changes the basis of comparison among competing vendors.
In this environment, decision-makers need more than broad market narratives. They require a disciplined view of where demand is forming, how product differentiation is evolving, and which competitive moves are likely to reshape pricing and service expectations. The PW Consulting study provides that view by linking macro growth signals to segment behavior, regional deployment patterns, and vendor-specific activity. It also highlights the practical implications of recent product introductions and catalog updates, helping organizations distinguish between incremental feature changes and structural improvements that affect total cost of ownership and deployment speed.
For enterprises evaluating scanner fleets, the research supports more precise refresh planning by clarifying the relationship between compliance-driven adoption, workflow decentralization, and product-form evolution. For vendors and channel partners, the analysis illuminates where portfolio emphasis is gaining traction and how distribution reach, integration capability, and service models influence competitive resilience. For investors and market observers, the report frames concentration dynamics and growth sustainability in a way that separates cyclical procurement noise from durable structural expansion.
Document Scanner Market
Conclusion: Turning Market Intelligence into Confident Action
The cheque scanner market is being reshaped by regulatory clarity, operational pressure, and a product landscape that is converging around reliability, compact deployment, and network-enabled management. Organizations that approach 2026 planning with a structured understanding of these forces will be better positioned to align hardware selection with compliance requirements, optimize branch-level capture workflows, and anticipate competitive shifts before they affect procurement outcomes.
PW Consulting’s full market research goes beyond surface-level sizing to deliver the analytical detail, competitive context, and forward-looking scenario discussion that enterprise decision-makers require. The complete study contains the granular segmentation, regional deployment patterns, vendor profiles, and product-evolution analysis needed to convert strategic questions into defensible action plans. To access the full intelligence framework and integrate it into your 2026 planning process, visit the source page for the complete Cheque Scanner Market research.
For detailed analysis of this topic, please visit the official page: Cheque Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Booster Pump Market to Hit 226 Million in 2025, Projected 4.45% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Booster Pump Market: Navigating Growth from 2026 to 2032
The global infrastructure landscape is undergoing a fundamental recalibration, driven by urbanization, industrial expansion, and tightening regulatory frameworks. At the heart of water distribution and pressure management lies a critical mechanical component: the booster pump. As enterprises plan capital expenditures and supply chain strategies for the coming years, precise market intelligence is no longer a luxury but a necessity. PW Consulting presents a comprehensive analysis of the Booster Pump Market, designed to equip stakeholders with actionable data for decision-making in 2026 and beyond.
This market research serves as a strategic blueprint for navigating a sector characterized by steady consolidation and technological evolution. By examining historical trajectories and forecasting future demand, this report clarifies where value is being created and where risks are emerging. The following insights excerpt from our full study highlight the market's financial architecture, competitive intensity, and the regulatory currents shaping the industry.
Market Trajectory and Financial Framework
Understanding the scale and velocity of the booster pump market is essential for allocating resources effectively. Over the historical period from 2020 to 2025, the market demonstrated resilience and moderate expansion, reflecting steady global demand for water pressure solutions. The assessed market size reached 226.0 million USD in the 2025 base year, building upon a foundation established during the post-pandemic recovery phase. This growth underscores the essential nature of booster pump systems in maintaining infrastructure reliability across residential, commercial, and industrial sectors.
Looking forward, the forecast period spanning 2026 to 2032 projects a continued expansion trajectory. Market valuation is expected to ascend to approximately 228.88 million USD in 2026, reflecting the immediate year-over-year momentum. The compound annual growth rate during this forecast window is calculated at 4.45 percent. This steady CAGR suggests a mature yet growing market environment where incremental efficiency gains and replacement cycles drive volume, rather than explosive speculative demand. By 2032, the financial scope of the market is projected to reach 306.47 million USD. This long-term valuation provides a critical benchmark for stakeholders modeling ROI on manufacturing capacity or distribution network expansions.
Water Pumps Market
The financial data indicates a market that is not only growing but also stabilizing around predictable performance metrics. For investors and manufacturers, this reduces volatility risk. For procurement officers, it offers a clearer basis for budget forecasting. However, these top-level figures represent only the aggregate view. The distribution of this value across different technological types, application verticals, and geographic regions reveals distinct pockets of opportunity that are critical for targeted strategy.
Competitive Landscape and Strategic Positioning
The booster pump industry is defined by a mix of established global players and specialized manufacturers focusing on niche applications. Market concentration is moderate, with the top three players holding a combined share of 24.6 percent and the top five accounting for 31.8 percent of the market. This fragmentation implies that while dominance by major corporations exists, there is ample room for specialized competitors to thrive through customization and regional service excellence.
Key industry participants include Grundfos, headquartered in Denmark, which stands as a full-range manufacturer of energy-efficient booster pumps and packaged systems for residential, commercial, and industrial water pressure boosting. In the United States market, several firms hold significant positioning. US Pump Corp operates as a custom intelligent booster pump system manufacturer offering simplex to multi-pump configurations for commercial, industrial, irrigation, and domestic applications. Similarly, Nickerson Company serves as a supplier and installer of packaged booster pump systems with in-house repair services for municipal and commercial water pressure boosting.
Towle-Whitney contributes to the market as a manufacturer of simplex, duplex, and triplex water booster pump systems and digital mixing valves for residential to commercial and institutional use. Penn Pump & Equipment Company operates as a custom manufacturer and distributor of water pressure booster systems, variable-speed pumping packages, and related pumping equipment. Walrus of America supplies centrifugal booster pumps and plug-and-play replacement systems for residential, commercial, and OEM booster applications. Pentair provides high-pressure booster pumps and packaged booster systems under the Sta-Rite and Berkeley brands for residential and commercial use.
Further strengthening the competitive field, Gorman-Rupp Company manufactures centrifugal, submersible, and booster pump stations for municipal, industrial, and commercial water pressure boosting. Xylem offers domestic and commercial booster pump systems with digital connectivity options for high-rise and residential buildings. Wilo SE, based in Germany, manufactures compact domestic and commercial booster pumps with energy-efficient and smart control features. APEC Water Systems focuses on high-pressure reverse osmosis booster pumps for household and light commercial water pressure boosting. Finally, Franklin Electric supplies multi-stage water pressure booster pumps and VersaBoost Pro smart systems for residential and multi-unit applications.
Recent developments illustrate the dynamic nature of this competitive field. In March 2026, Duke Pumping Solutions launched a domestic vertical multistage booster pump series with DIN flange standards and steady flow performance. Following ASPE Tech Symposium discussions, Towle-Whitney introduced the TW2018W series variable-speed booster pump systems in April 2026. Pentair released an updated January 2025 list prices for high-pressure booster pumps and systems, signaling pricing adjustments relevant to procurement planning. Additionally, Gorman-Rupp completed the installation of a custom water booster pump station in Blaine, PA, in April 2026, while Islamorada Village issued RFP 26-05 for the upgrade of the North Plantation Key booster pump station, including demolition, new construction, and full commissioning. These events highlight the continuous cycle of product innovation and infrastructure investment driving the market.
Regulatory and Technical Dynamics
The market environment is heavily influenced by regulatory standards and technical specifications that dictate performance requirements and installation protocols. Compliance is not merely a legal obligation but a strategic differentiator for manufacturers offering certified solutions. In the United States, the New Jersey Administrative Code requires public community water systems to maintain a minimum pressure of 20 psi at street level. This regulation directly impacts the specification and sizing of booster pump systems in public infrastructure projects within the state.
Technical standards also play a pivotal role. The AWWA E102 standard updates for submersible vertical turbine pumps remain active for booster applications, guiding engineering choices for durability and efficiency. Furthermore, the Phius Water Pressure Booster Pump Estimator, released in July 2024, aids in residential energy use calculations for buildings over four stories, integrating energy performance into the design phase. These tools are becoming essential for engineers and architects aiming to meet sustainability goals.
Industry engagement continues to drive knowledge exchange. The AWWA Annual Conference & Expo is scheduled for June 21-24, 2026 in Washington, D.C., covering booster pump technologies. Such gatherings provide a forum for unveiling new standards and network-building. It is important to distinguish relevant regulatory shifts from noise in the broader consumer safety landscape. For instance, CPSC bicycle helmet recalls issued in June 2026 for non-compliant impact attenuation are unrelated to water booster pumps, yet they serve as a reminder of the broader compliance environment in which industrial manufacturers operate.
Operational Intelligence and Report Contents
To fully leverage the data outlined above, decision-makers require granular detail that goes beyond high-level trends. This report provides an in-depth examination of the segmentation structures that define revenue streams. It analyzes the breakdown of the market by product type, evaluating the dominance of centrifugal designs against reciprocating, rotary, and other specialized configurations. The study also dissects application verticals, providing visibility into how demand varies between water supply networks, industrial processes, agricultural operations, and other end-use scenarios.
Geographic analysis is another cornerstone of this research. The report delineates market performance across key regions, including North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa. Each region presents unique drivers, from infrastructure aging in developed economies to rapid urbanization in emerging markets. Understanding the relative weight and growth potential of these regions allows companies to prioritize market entry or expansion strategies.
Furthermore, the study incorporates a detailed competitive benchmarking analysis. It profiles the strategies, product portfolios, and financial health of key companies such as Grundfos, Pentair, and Xylem, among others. This section helps identify gaps in the market that competitors may be missing and highlights best practices in supply chain management and technology adoption. The report also includes a forecast model that extends through 2032, enabling sensitivity analysis for various economic scenarios.
Procurement decision-makers will find specific value in the sections dedicated to pricing trends and raw material cost dynamics. By correlating recent industry developments, such as the product launches by Duke Pumping Solutions and Towle-Whitney, with broader market pricing structures, the report offers a realistic view of cost pressures and margin opportunities. The inclusion of recent contract awards and RFPs, like the Islamorada Village project, provides real-world context for demand velocity in specific municipal segments.
Strategic Implications for 2026 Decision-Making
As we move deeper into 2026, the strategic imperative for booster pump market participants is to balance steady growth with technological agility. The market's projected growth to 306.47 million USD by 2032 suggests that scale will remain a viable path to profitability, but only for those who can navigate the moderate concentration of the top players. The 4.45 percent CAGR indicates that success will likely come from capturing share in specific high-growth segments rather than relying solely on overall market lift.
Energy efficiency and digital connectivity are emerging as key differentiators. With regulations like the Phius estimator influencing building design and standards like AWWA E102 guiding pump selection, manufacturers who integrate smart control features and energy-efficient designs into their commercial and residential offerings will be better positioned to capture premium segments. Companies like Grundfos and Wilo SE are already emphasizing these attributes, setting a benchmark for the rest of the industry.
Supply chain resilience and customization capabilities, showcased by firms like US Pump Corp and Penn Pump & Equipment Company, are also critical. As municipal and industrial clients seek tailored solutions for complex pressure boosting needs, the ability to deliver custom configurations without compromising lead times will be a significant competitive advantage. The recent installation activities by Gorman-Rupp and the RFP activities in regions like Florida suggest that infrastructure renewal projects are ongoing and present immediate revenue opportunities.
For investors, the moderate market concentration suggests a landscape where mergers and acquisitions could reshape the top tier, while organic growth remains strong in the mid-tier. For manufacturers, the focus must be on aligning product development with the regulatory and technical demands of the forecast period. For distributors, understanding the regional disparities in market size and growth potential is key to optimizing inventory and sales efforts.
Conclusion
The Booster Pump Market stands at a juncture where steady historical growth meets a future defined by regulatory precision and technological integration. The financial outlook supports confidence, but the details of segmentation, competition, and regional dynamics hold the keys to unlocking specific value. This report from PW Consulting provides the comprehensive intelligence required to navigate these complexities. It transforms raw data into strategic narratives, helping stakeholders identify where to invest, how to compete, and when to act.
Booster Pump Market
To access the complete dataset, including detailed segmentation percentages, regional revenue breakdowns, and full company profiles, we invite you to review the full market research report. The complete analysis offers the depth necessary for precision planning in 2026 and beyond. Ensure your strategy is built on the most robust intelligence available by accessing the full source material today.
For detailed analysis of this topic, please visit the official page: Booster Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Commercial Kitchen Ventilation Market to Hit $2,575.56M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Modern Kitchen: Inside Our 2026 Commercial Kitchen Ventilation Systems Market Report
The commercial kitchen ventilation sector is entering a decisive inflection point. What was once regarded as a static building infrastructure category is now a dynamic battleground where energy regulation, operational efficiency, and safety compliance intersect. For executives navigating capital allocation, supply chain strategy, and product portfolio optimization in 2026, the installation and service landscape is shifting faster than legacy forecasting models can capture. Our newly published market intelligence report maps this transformation with precision, offering a decision-ready compass for manufacturers, distributors, facility operators, and ecosystem investors across the commercial foodservice value chain.
The industry trajectory tells a clear story of sustained expansion. Drawing on a comprehensive historical window from 2020 through 2025 and projecting forward to 2032, the analysis quantifies momentum that has persisted through supply chain recalibration, labor constraints, and evolving building performance mandates. The underlying market has demonstrated consistent upward movement, with the base year establishing a firm valuation foundation that carries meaningful forward gravity. This calculated growth rate positions the sector as a structurally expanding category rather than a cyclical fluctuation, reinforcing its relevance in long-term strategic planning.
Adoption drivers are no longer limited to code compliance alone. While mandatory standards from the FDA Food Code and NFPA 96 continue to anchor baseline requirements for heat, smoke, grease, and vapor capture, a new layer of operational pressure is reshaping purchasing behavior. The 2021 Uniform Mechanical Code provides the technical framework for safe installation, but the market is now responding to deeper operational imperatives: utility cost volatility, localized emission controls, grease management accountability, and the financial drag of continuously running over-engineered exhaust systems. Against this backdrop, ventilation infrastructure is increasingly evaluated through the lens of total cost of ownership rather than upfront equipment pricing.
Decoding the Structural Composition of the Market
The commercial kitchen ventilation ecosystem is composed of interdependent product categories that collectively determine system performance, compliance outcomes, and lifecycle economics. The report dissects these segments to reveal where value is concentrated, which components face the most intense substitution dynamics, and how procurement patterns differ across installation contexts. Hoods remain the mechanical centerpiece of the category, but their dominance is increasingly measured against the growing strategic importance of exhaust fans, ducting architecture, makeup air balancing, and intelligent control integrations.
Each product pillar interacts with a distinct set of operational realities. Exhaust and ducting infrastructure dictates airflow efficiency and maintenance burden. Makeup air systems govern temperature stability and combustion safety within the kitchen envelope. Controls and accessories, once treated as peripheral add-ons, are now central to modulating fan speeds, matching ventilation output to actual cooking loads, and capturing energy savings in high-utilization environments. The study isolates these structural components not as isolated line items, but as a coordinated system where design choices in one layer directly alter performance, compliance exposure, and long-term operating expense in another.
Application-level demand patterns further complicate procurement planning. Commercial kitchens serve a wide spectrum of operational profiles, from high-turnover quick-service environments to institutional food preparation spaces with extended service hours and specialized ventilation needs. Hospitality venues, educational campuses, corporate and industrial dining facilities, and healthcare institutions each impose different hygiene standards, smoke management thresholds, and sanitation cycles. The report maps these application contexts to clarify where ventilation requirements diverge and where shared system architectures can be leveraged for scale without compromising regulatory alignment.
Regulatory Tailwinds and Technical Shifts Shaping 2026
The competitive and commercial rhythm of this market is being rewritten by regulatory evolution and engineering modernization. In 2025, the California Energy Commission advanced code change proposals targeting energy efficiency improvements and greenhouse gas reductions in commercial kitchens, with potential mandatory adoption of demand-controlled kitchen ventilation as the next progression beyond existing standards. Such developments signal a broader trajectory in which ventilation systems will be evaluated not only for their ability to capture contaminants, but for their capacity to modulate energy consumption in response to real-time cooking activity.
At the same time, foundational compliance expectations remain non-negotiable. FDA-driven public health protections require commercial exhaust systems to reliably capture and contain heat, smoke, grease, and vapors. NFPA 96 continues to mandate rigorous design, installation, and maintenance requirements for commercial cooking operations, while the Uniform Mechanical Code outlines the technical parameters for safe system deployment. These overlapping frameworks create both a compliance floor and a performance ceiling, compelling operators to balance safety assurance with efficiency optimization. The report examines how these regulatory pressures are translating into procurement criteria, service contract expectations, and retrofit decision-making.
Industry participants are already responding with product and service expansions that reflect this shifting mandate. Recent portfolio developments illustrate a clear industry trend toward integrated offering models. For example, a prominent foodservice equipment provider recently broadened its commercial kitchen hood service capabilities to encompass fully engineered ventilation systems, professional consultation, customized hood packages, makeup air units, ventless exhaust configurations, Type 1 and Type 2 hood variants, and specialized applications such as food truck and pizza oven exhaust designs, alongside fire suppression integration and hood filtration accessories. Such moves highlight a market moving from component sales toward end-to-end engineered solutions.
Competitive Landscape: Where Strategy Is Being Won or Lost
The market structure reflects meaningful concentration, with a limited group of established players commanding a significant share of revenue and engineering influence. This concentration shapes pricing dynamics, technology adoption velocity, and the pace at which new entrants can secure footholds in regulated segments. Understanding who leads, where they compete, and how they differentiate is essential for positioning product roadmaps, sales motions, and partnership strategies in 2026 and beyond.
CaptiveAire Systems, Inc., headquartered in Raleigh, North Carolina, stands as a leading manufacturer of commercial kitchen ventilation systems and is recognized for its breadth across exhaust hoods, fans, grease management, and complete HVAC solutions tailored to foodservice operations. Greenheck Fan Corporation, based in Schofield, Wisconsin, complements this competitive tier with a strong portfolio spanning exhaust hoods, fans, makeup air units, and energy recovery ventilation designed for restaurant and foodservice environments. Systemair AB, operating from Skinnskatteberg, Sweden, brings a distinctive emphasis on advanced kitchen exhaust systems, high-performance air purification, smart airflow controls, and demand-controlled ventilation approaches. Together, these players illustrate how leading manufacturers are converging around integrated air management rather than isolated hood fabrication.
A second layer of competition is defined by specialized technology positioning and regional execution strength. Gaylord Industries, located in Tualatin, Oregon, focuses on demand control kitchen ventilation systems, custom kitchen hoods, and pollution control equipment for commercial foodservice. FAST Kitchen Hoods, based in Mississauga, Ontario, has built recognition around cULus-rated commercial kitchen hoods, exhaust systems, island configurations, and low-ceiling solutions for restaurant applications. Chef’s Deal Restaurant Equipment, headquartered in Nashville, Tennessee, operates as both supplier and installer of comprehensive ventilation systems, covering engineered hoods, makeup air units, ventless exhaust, Type 1 and Type 2 grease hoods, and related accessories. This breadth of service orientation reflects an industry trend in which installation capability, customization, and after-sale support have become competitive differentiators, not optional adjuncts.
Commercial Kitchen Ventilation Systems Market
Additional participants continue to shape the market through control innovation and multi-region manufacturing presence. Melink Corporation, with nationwide operations in the United States, provides Intelli-Hood demand control kitchen ventilation systems and controls that target energy-efficient exhaust operations. North American Kitchen Solutions (NAKS), operating across Ohio, Georgia, and Texas, manufactures commercial kitchen hoods, exhaust and supply fans, fire suppression components, and portable ventless hood systems. These profiles underscore a market where product leadership is increasingly linked to control intelligence, modular deployment options, and the ability to serve both permanent and transient kitchen configurations.
Residential Ventilation Systems Market
What the Report Delivers: Actionable Intelligence for Decision-Makers
This study is designed to move beyond surface-level market sizing and into the operational and strategic details that inform investment and execution. The report maps current market size and forward valuation pathways, contextualizes historical performance from 2020 through 2025, and translates that trajectory into a forecast window extending to 2032. The emphasis is not simply on where the market has been, but on how structural variables will shape competitive outcomes over the coming planning cycle.
The analysis provides a practical framework for evaluating product and application dynamics without reducing them to static snapshots. Readers gain visibility into how core product categories relate to one another, where system-level design decisions influence downstream operating costs, and how application contexts alter ventilation priorities. This approach enables stakeholders to assess which segments are likely to attract the most engineering attention, which procurement groups will demand higher specification flexibility, and where service and integration capabilities will become essential to market access.
Equally important, the report situates competitive positioning within a realistic view of market concentration and differentiation levers. Rather than treating competitors as isolated company profiles, the study examines how leading manufacturers and specialized suppliers are aligning product architecture, regional execution, and service scope to capture distinct value pools. It also addresses the regulatory environment as a strategic variable, showing how evolving energy efficiency expectations, ventilation control requirements, and fire safety standards are reshaping procurement criteria and long-term system design philosophy.
Why This Research Matters for 2026 Strategy
The decisions being made in 2026 will determine how organizations position themselves for the next cycle of regulation, energy economics, and foodservice operational complexity. Capital deployed in ventilation infrastructure is no longer a passive compliance expense; it is a strategic asset that affects operating margin, safety performance, and readiness for emerging code requirements. A rigorous understanding of market direction, competitive intensity, and application-specific demand patterns is therefore essential for avoiding stranded investments and misaligned product plans.
This report is structured to support precisely those decisions. It gives executives the analytical clarity to evaluate growth pathways, the competitive context to benchmark positioning, and the operational insight to anticipate where specification, installation, and service expectations will tighten. For manufacturers, it clarifies where product emphasis and engineering investment are most defensible. For distributors and installers, it identifies where service breadth and solution integration will command premium value. For institutional and corporate operators, it supports more informed procurement and retrofit prioritization by linking ventilation design choices to compliance and lifecycle performance.
The broader takeaway is that the commercial kitchen ventilation market is being redefined by the convergence of safety mandates, energy performance expectations, and intelligent airflow control. Organizations that treat ventilation as a system-level discipline, rather than a component-level purchase, will be better positioned to navigate the next phase of market evolution. Our full research study provides the strategic anatomy required to make that transition with confidence.
To access the complete segmentation analysis, forecast timelines, competitive benchmarking, and regional and application-level intelligence behind this overview, we invite you to explore the full report on our website. The detailed data architecture, scenario considerations, and proprietary market mappings contained in the study are designed to support immediate planning as well as longer-range strategic commitment.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Connectors Market Hits $7B in 2025, Projects 6.97% CAGR to $11.17B by 2032
By pmarketresearch, 2026-09-15
Unlocking Strategic Value in the Automotive Connectors Market: A 2026 Decision-Maker's Preview
The automotive connectivity landscape is undergoing a structural transformation driven by electrification, software-defined architectures, and stringent safety mandates. As vehicle architectures consolidate domain controllers and transition toward zonal designs, the demand for precision interconnects has evolved from a commodity consideration to a core engineering and procurement priority. For executives navigating capital allocation, product roadmap planning, and supply chain resilience in 2026, understanding the trajectory of this market is no longer optional—it is a prerequisite for competitive positioning.
Our latest Automotive Connectors Market research publication delivers a comprehensive, forward-looking intelligence framework tailored for strategic decision-making. This article serves as a strategic preview, outlining the analytical depth, operational utility, and competitive context embedded within the full report. While we highlight the macro trajectory and structural dynamics shaping the sector, the granular segmentation breakdowns, regional revenue distributions, and application-specific growth vectors are intentionally reserved for the complete dataset available on our source page.
The Macro Trajectory: Scaling Momentum Through 2032
Historical tracking from 2020 through 2025 reveals a consistent upward progression in global connector revenue, reflecting sustained vehicle production volumes, the gradual phase-in of electrified platforms, and the expanding sensorification of both interior and exterior subsystems. The market has crossed the 7 billion USD threshold in the base year, establishing a robust foundation for the forecast horizon.
Looking ahead, the compounding growth rate projected at approximately 6.97 percent CAGR across the 2026 to 2032 forecast window underscores a market that is not merely expanding, but accelerating its structural complexity. By the close of the decade, total revenue is expected to approach the 11 billion USD mark, signaling a market that will be fundamentally reshaped by higher-voltage architectures, high-speed data transmission requirements, and the standardization of charging interfaces.
This trajectory is not uniform across all technical categories or end-use environments. The interplay between legacy wired harnesses, high-density board-level interconnects, radio frequency signaling components, and fiber optic solutions creates a layered demand profile that requires precise forecasting. Our analysis captures these intersecting growth vectors without reducing them to simplistic linear extrapolations, ensuring that procurement leaders and product strategists can anticipate inflection points rather than merely react to them.
Structural Segmentation: Where Growth Converges and Diverges
The automotive connector ecosystem spans multiple technical typologies, each responding to distinct engineering pressures and cost-performance thresholds. High-reliability board-level interconnects continue to anchor central electronic architectures, while integrated circuit positioning solutions serve the expanding footprint of power management and control modules. Radio frequency and fiber optic interfaces are gaining strategic relevance as vehicles transition toward advanced driver-assistance platforms, in-vehicle infotainment networks, and high-bandwidth telemetry systems.
Across the application spectrum, connectivity requirements are being reallocated. Passenger compartment control and interior subsystems maintain substantial volume, while safety and security architectures demand increasingly redundant, fault-tolerant interconnect specifications. Powertrain electrification, engine management, and thermal regulation pathways are driving higher current-carrying capacities and improved environmental sealing. The remaining segments capture emerging niche applications that collectively contribute to incremental but strategically significant revenue streams.
Our full report dissects these segmentation layers with granular precision, mapping absolute market sizing, relative share dynamics, and forward-looking demand elasticity. Rather than presenting static percentage allocations, the analysis contextualizes how technological roadmaps, packaging constraints, and tier-one supplier specifications will redistribute value across categories over the forecast period.
Competitive Landscape: Consolidation, Capability, and Cross-Functional Rivalry
The connector market exhibits a moderately concentrated structure, with a core group of multinational and regional specialists commanding a substantial share of global revenue. This concentration reflects the capital-intensive nature of qualification cycles, the importance of long-term automotive supply chain partnerships, and the technical barriers associated with high-voltage, high-speed, and extreme-environment interconnect solutions.
Several industry leaders define the competitive baseline. TE Connectivity maintains a broad portfolio spanning low-voltage signal and power connectivity across passenger vehicles, commercial trucks, buses, and off-road platforms. Amphenol Corporation focuses on ruggedized interconnect systems engineered for electrified powertrains, hybrid architectures, and advanced sensing deployments. Molex, operating as a Koch Industries company, has introduced high-voltage connector platforms and auxiliary power distribution solutions specifically designed for electric and hybrid vehicle architectures.
Automotive Connectors Market
In Japan, JAE Electronics has expanded its compact, high-density portfolio with high-current variants rated for substantial power throughput, alongside Ethernet-compatible models targeting next-generation in-vehicle networking. Hirose Electric continues to develop performance-oriented interconnects for infotainment and power distribution applications, while Sumitomo Electric Industries supplies high-voltage and wiring harness interfaces tailored to electrified vehicle platforms. Yazaki Corporation remains a major contributor to global wiring harness connector and terminal supply chains.
Asian manufacturing ecosystems contribute additional scale and specialization. KSTerminals emphasizes rigorously tested aftermarket and replacement-grade connectors focused on power and signal reliability. Greenconn Corporation delivers IATF 16949-certified electrical connectors and board-to-board solutions aligned with automotive quality management expectations. Sunkye Electronic Technology provides customized, specification-grade connectors for on-highway and off-highway vehicles, including hybrid applications.
European and cross-regional players further diversify the landscape. Rosenberger Group specializes in high-speed data and RF interconnect solutions for automotive communications and test environments. Aptiv integrates advanced connector and wiring systems directly into vehicle platform architectures, reinforcing the convergence between traditional interconnect suppliers and OEMsupplier system integrators.
The full competitive analysis within the report evaluates these players across revenue positioning, product portfolio breadth, geographic footprint, recent product introductions, and strategic alignment with electrification and connectivity megatrends. Rather than presenting a static leaderboard, the analysis maps competitive vulnerabilities, partnership dependencies, and innovation velocity to help decision-makers anticipate supplier consolidation, pricing pressure, and capacity allocation dynamics.
Recent Developments and Regulatory Accelerators
The market is not evolving in isolation. Recent product launches and standardization efforts are actively reshaping design requirements and procurement timelines. In late 2025, JAE Electronics introduced the MX81D Series, delivering up to 25 amperes for high-power automotive applications, and subsequently expanded its MX34 Series of compact automotive connectors. The same period saw the release of the MX74 Series, engineered for automotive Ethernet 1000BASE-T1 compatibility, reflecting the industry's accelerating push toward high-bandwidth in-vehicle networking.
Simultaneously, standardization bodies and industry consortia are formalizing the technical foundations for next-generation charging and interconnect safety. In May 2025, SAE International published SAE J3400/2, establishing specifications for connectors and inlets supporting the North American Charging System at voltages up to 1000 volts to enable faster EV charging. This followed a broader standardization sequence, including the issuance of the J3400 Recommended Practice for adapters in late 2023 and the publication of the J3400/1 Technical Information Report in April 2025 to improve safety and interoperability across charging interfaces. The US Department of Transportation had previously issued a Request for Information in early 2024 regarding the J3400 connector, signaling potential performance-based standards for EV charging equipment.
Internationally, the ZVEI published the TLF0214 technical guideline in mid-2024, introducing standardized validation procedures for low-voltage automotive connectors at DC levels up to 60 volts. These regulatory and technical specifications do not merely set compliance thresholds; they influence qualification lead times, testing investments, and the competitive positioning of suppliers whose portfolios are aligned or misaligned with emerging standards.
Supply chain resilience introduces an additional layer of complexity. Sentiment from major supplier disclosures highlights the dependency on raw materials such as plastic resins and precious metals, which are often sourced from a limited set of producing countries and subject to geopolitical volatility and import/export licensing constraints. This reality elevates the strategic importance of supplier geographic diversification, inventory buffer strategies, and qualification pathway planning.
Why This Research Matters for 2026 Strategic Decisions
Automotive procurement, engineering leadership, and investment teams face a converging set of challenges in 2026. Connector specifications are no longer determined solely by current rating or form factor; they must account for thermal management, signal integrity at higher data rates, high-voltage isolation, long-term environmental durability, and compatibility with evolving charging and communication standards. Supplier selection increasingly hinges on qualification readiness, geographic supply chain resilience, and the ability to support zonal architecture transitions without introducing costly redesign cycles.
Our report is structured to convert this complexity into actionable intelligence. It provides decision-makers with a defensible basis for capacity planning, supplier negotiation, technology investment, and portfolio prioritization. Rather than offering generic market narratives, the analysis anchors forecasts in verified historical patterns, clearly delineated forecast assumptions, and transparent segmentation logic. The result is a decision-support tool that can be integrated directly into roadmap reviews, sourcing strategies, and competitive benchmarking exercises.
Inside the Report: A Practical, Execution-Oriented Framework
The publication is designed as a multi-layered reference that balances high-level market intelligence with the operational detail required for execution. Core components include a complete market sizing and forecast model spanning historical baselines through the full 2032 outlook, enabling readers to trace growth inflection points and validate internal assumptions. Segmentation analysis is structured to support both technical and commercial planning, allowing engineering teams, procurement groups, and strategy functions to extract relevant views without friction.
Industrial Connectors Market
Competitive profiling goes beyond descriptive summaries. Each major player is evaluated through a consistent analytical lens that considers portfolio alignment with electrification and high-speed data trends, recent product introductions, geographic and manufacturing footprints, and likely strategic priorities over the forecast period. Recent developments, including product launches, standard publications, and technical guideline updates, are mapped to their likely impact on design requirements, qualification timelines, and supplier competitiveness.
The report also integrates regulatory and standardization catalysts into the broader market narrative, ensuring that readers understand not just what is changing, but why it matters for sourcing, testing, and product architecture decisions. By linking standard evolution to practical engineering implications, the analysis helps teams anticipate redesign risk, qualification cost, and supplier capability gaps before they become costly surprises.
Conclusion: Turning Market Complexity into Strategic Advantage
The automotive connectors market is entering a phase where growth is inseparable from technological redefinition. Electrification, zonal architectures, high-bandwidth in-vehicle networks, and formalized charging standards are collectively reshaping the specification, qualification, and sourcing landscape. For organizations making decisions in 2026, the ability to read these shifts early—and to align product, supply chain, and investment strategies accordingly—will determine whether the market is navigated reactively or shaped proactively.
This research preview has outlined the structural context, competitive dynamics, and recent standardization catalysts that define the market environment. The complete report builds on this foundation with detailed segmentation sizing, regional and application-level growth mapping, supplier capability benchmarking, and forecast sensitivity analysis. To access the full dataset, competitive deep dives, and the complete forecast model, please visit the source page for the Automotive Connectors Market research publication and secure the comprehensive intelligence needed to guide your next strategic moves.
For detailed analysis of this topic, please visit the official page: Automotive Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Powder Metallurgy Market Hits $9.08B in 2025, Forecasts 12.8% CAGR to Reach $21.25B by 2032
By pmarketresearch, 2026-09-15
Strategic Horizons: Why the Powder Metallurgy Market Demands Your Attention in 2026
The global powder metallurgy sector is entering a decisive phase of expansion and structural transformation. From 2020 through 2025, the market demonstrated consistent growth, transitioning from a cyclical industrial support function to a strategic materials enabler across transportation, advanced manufacturing, and specialty engineering. As organizations map out capital allocation, supply chain resilience, and product development roadmaps for 2026, a clear, evidence-based view of where this market is heading has never been more critical. This report is designed to provide that view.
Metal Powder Market
Rooted in a comprehensive historical baseline spanning 2020 to 2025, the study projects market trajectories through 2032, capturing demand shifts, production scaling, and competitive repositioning across the value chain. For executives, procurement leaders, R&D directors, and investors, the differentiation between reactive strategy and proactive advantage lies in how early and accurately they can read these signals. The following overview outlines the analytical architecture behind the research, the structural forces currently reshaping the landscape, and how the full dataset can be operationalized for 2026 decision-making.
The Growth Trajectory: Reading the Larger Arc Without Losing Sight of the Branches
The historical progression tells a story of compounding momentum. Market valuation climbed from 5.59 billion USD in 2020 to 9.08 billion USD by 2025, reflecting a steady acceleration in adoption and throughput across core end-use sectors. From that 2025 base, the forward curve steepens further, reaching an estimated 10.61 billion USD in 2026 and continuing upward to approximately 21.25 billion USD by 2032. Over the full forecast horizon, this translates to a compound annual growth rate of 12.8 percent.
These figures are not abstract benchmarks. They represent the cumulative effect of component design optimization, material substitution cycles, localized supply chain investment, and the ongoing migration of powder-based processes into precision engineering and advanced manufacturing workflows. Yet aggregate trajectories only reveal part of the picture. The decisive insights for enterprise strategy reside in how growth distributes across material categories, application verticals, and regional ecosystems, where supply bottlenecks, regulatory exposures, and customer concentration create divergent risk and reward profiles. Identifying which segments are expanding from volume leverage versus those driven by specification upgrades, and understanding where procurement cycles are lengthening or shortening, is essential for positioning product portfolios, service offerings, and capacity investments.
The research deliberately isolates these structural layers, mapping the interaction between material classification, end-market demand intensity, and geographic production footprints. By keeping the narrative focused on decision-ready architecture rather than isolated headline numbers, the report enables teams to place their own business units, competitors, and supply dependencies within the broader market geometry.
Competitive Landscape: Consolidation Dynamics, Strategic Shifts, and Three Recent Flashpoints
Market concentration remains meaningful. The leading three firms account for roughly half of total industry revenue, while the top five collectively capture approximately 60 percent. This level of concentration suggests both a maturing competitive field and the continued presence of room for differentiated entrants, particularly those bringing process innovation, feedstock flexibility, or region-specific manufacturing advantages.
The competitive roster spans established industrial powder specialists, engineering component producers, and emerging players focused on additive manufacturing feedstocks and low-carbon processing. European and North American incumbents maintain strong positions in ferrous and alloy powder supply, precision sintered components, and specialty material systems, while Asian-based suppliers have expanded their reach in iron, copper, nickel, and refractory powder streams. Regional footprints, intellectual property portfolios, and integration depth across the powder-to-component value chain are increasingly uneven, creating competitive differentiation that cannot be read from top-line size alone.
Recent corporate activity underscores how rapidly the field is repositioning. In mid-2026, Mimir signed an agreement to acquire Sandvik’s Osprey MIM and AM powder business, a move that signals intensifying consolidation around metal injection molding and additive manufacturing feedstock capabilities. Around the same period, CNPC Powder began construction of a new production and R&D facility in California, reflecting a strategic expansion of North American operational presence and a clear bet on localized engineering support. Meanwhile, IperionX commissioned a 300-ton six-axis press at its Virginia Titanium Manufacturing Campus, reinforcing the trend toward capacity scaling in titanium and specialty alloy powder processing. Each event illustrates a different vector of change: consolidation, geographic diversification, and process capacity investment.
Understanding who controls which processing routes, feedstock grades, and component capabilities is essential for pricing strategy, partnership selection, and risk assessment. The analysis maps these players across their core competencies and recent moves, enabling readers to benchmark their own exposure against the evolving competitive architecture.
Structural Dynamics Shaping Demand and Supply in the Near Term
Several overlapping forces are shaping how the market behaves heading into 2026. Regulatory and geopolitical factors are reintroducing constraints and incentives into refractory metal sourcing, with trade policy measures and defense procurement clauses beginning to influence demand patterns for certain metals and tungsten-based powders. At the same time, raw material cost volatility and shipment adjustments in specific North American metal powder categories highlight the sensitivity of the midstream to macroeconomic conditions and end-market order pacing.
Standardization continues to provide the technical backbone for qualification and interoperability. Industry specifications governing particle size distribution and related powder characteristics remain central to consistent processing outcomes, particularly as components move into higher-performance applications where repeatability is non-negotiable. On the demand side, ferrous powders continue to anchor a large share of shipments, particularly in precision gears and bearings, reinforcing the enduring importance of established PM applications even as advanced alloys and additive feedstocks capture a growing share of attention.
The interplay between these dynamics is where strategic judgment matters most. Regulation can redirect sourcing, cost fluctuations can compress margins or accelerate substitution, standards can raise barriers to entry or unlock new customer confidence, and application-level demand can shift faster than production capacity. The report isolates these forces within a structured dynamics section, allowing decision-makers to weigh near-term disruptions against longer-term structural demand drivers.
What the Report Delivers: An Operational Framework for 2026 Decisions
This study is built around actionability. It moves beyond market sizing into the operational strata that executives require to convert intelligence into strategy. The research begins with a rigorous historical reconstruction spanning 2020 to 2025, establishing the baseline against which current momentum and forecast assumptions are calibrated. From there, the forecast model extends through 2032, offering a forward arc that supports capacity planning, product investment timing, and procurement strategy development.
Powder Metallurgy Market
The segmentation architecture examines material categories and end-use applications in detail, identifying where volume growth, value intensity, and substitution risk are concentrated. Regional analysis covers major markets and emerging production hubs, highlighting differences in demand maturity, manufacturing localization, and supply dependency. Rather than presenting segments as isolated slices, the report situates them within the competitive and regulatory environment that shapes their trajectory.
The competitive section profiles the principal companies driving the market, assessing their operational scope, technological positioning, and recent strategic action. It further contextualizes these profiles through recent developments, including acquisitions, facility expansions, and equipment commissioning, giving readers visibility into where capital and capability are being deployed in real time. The dynamics section integrates regulatory exposure, materials cost considerations, standardization requirements, and application-level demand patterns to create a multi-factor view of market behavior.
Taken together, these components allow teams to answer practical questions: which geographic markets are expanding with the strongest demand pull, where material categories face the greatest supply or cost volatility, how consolidation and new capacity are likely to affect pricing and availability, and which application segments offer the clearest growth runway relative to competitive intensity.
How to Use This Intelligence for 2026 Planning
For leadership teams planning the 2026 horizon, the report is intended to serve as both a diagnostic and a planning scaffold. Procurement and supply chain leaders can use the regional and segmentation mapping to evaluate sourcing diversification, identify exposure to regulatory and cost shocks, and align inventory or contract strategies with anticipated demand shifts. Product and engineering teams can place their development roadmaps against application-level demand patterns, assessing where precision components, advanced alloys, or additive-compatible powders are likely to see the strongest pull. Strategy and corporate development groups can leverage the competitive and dynamics analysis to evaluate partnership opportunities, acquisition targets, or market entry assumptions with a clearer view of concentration and capability distribution.
Importantly, the value of the report lies not only in the numbers but in the connective analysis between them. Total market size and growth trajectory provide context, but the strategic signal emerges when those trends are layered with segmentation behavior, competitive movement, and regulatory or cost dynamics. That layered view is what allows an organization to move from general market awareness to specific, defensible action.
Next Steps: Accessing the Full Intelligence Package
The overview above is designed to demonstrate the analytical depth and decision orientation of the study while preserving the detailed segmentation data, regional breakdowns, application-level valuations, and company-specific intelligence that constitute the core deliverable. For teams that require the full dataset, scenario-ready segmentation, or a tailored read on how the 2026-to-2032 trajectory intersects with their own product lines and supply base, the complete report is available through the original research release. There, readers will find the granular breakdowns, competitive profiles, and dynamic-factor analysis needed to convert market intelligence into concrete 2026 strategy.
The powder metallurgy market is not simply growing; it is reconfiguring around material innovation, geographic investment, regulatory exposure, and consolidation. Organizations that understand these layers early will be better positioned to price, source, invest, and compete with confidence.
For detailed analysis of this topic, please visit the official page: Powder Metallurgy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Road Bikes Market Hits $3.85B in 2025, Forecast to Reach $5.49B by 2032
By pmarketresearch, 2026-09-15
Road Bikes Market Strategic Intelligence 2026: Navigating Growth Amid Regulatory Shifts
The global road bikes market stands at a pivotal inflection point as it enters the 2026–2032 forecast window. After a decade of steady volume expansion and material innovation, manufacturers now face a complex matrix of regulatory uncertainty, raw material volatility, and rapidly evolving consumer expectations. Our latest comprehensive market study transforms this complexity into a clear strategic roadmap. By integrating historical performance data, forward-looking modeling, and granular competitive intelligence, the research equips executive teams with the analytical precision needed to allocate capital, position product portfolios, and secure supply chains in a highly consolidated industry.
This introductory brief outlines the structural contours of the market, highlights the operational realities shaping decision-making in 2026, and demonstrates how our full report delivers actionable intelligence for stakeholders across manufacturing, distribution, and investment functions. The analysis deliberately reserves core segmentation metrics for the complete publication, ensuring that readers understand the strategic architecture of the study before accessing the detailed quantitative appendices.
Market Trajectory and Structural Foundations
The road bikes market has demonstrated consistent monetization growth over the past five years, with total industry revenue climbing from 3.12 billion USD in 2020 to an estimated 3.85 billion USD by 2025. This trajectory reflects sustained demand across performance-oriented and utilitarian segments, supported by expanding cycling infrastructure, rising health-conscious mobility preferences, and incremental consumer spending on durable recreational goods. The base year close establishes a resilient foundation, though the pace and composition of future growth will diverge meaningfully across geographies, material categories, and end-use applications.
Forward projections place the market on a compound annual growth path of approximately 4.85 percent through 2032, culminating in a valuation that materially outpaces the prior five-year cadence. Growth acceleration will not be uniform. Instead, it will be shaped by three interlocking forces: the maturation of carbon fiber adoption in mid-tier and endurance road platforms, the competitive pressure on aluminum and steel segments as price sensitivity intensifies, and the geographic realignment of demand as emerging cycling markets develop distribution networks and brand recognition. The full study models these vectors through scenario-based forecasting, enabling leadership teams to test portfolio assumptions against multiple macroeconomic and regulatory conditions rather than relying on single-point estimates.
Crucially, the market remains moderately concentrated. The top three participants collectively account for roughly 42.5 percent of global revenue, while the top five expand that share to 58.0 percent. This concentration profile indicates that margin protection, brand loyalty, and channel control remain decisive advantages, but it also signals meaningful whitespace for regional specialists and direct-to-consumer entrants that can exploit geometry customization, localized assembly, or niche performance positioning. Our report dissects how these concentration dynamics interact with product lifecycle timing, pricing elasticity, and distribution strategy, providing a comparative framework that helps both incumbents defend category leadership and challengers identify defensible entry points.
Regulatory and Supply Chain Dynamics Redefining Competitive Position
The operating environment for road bike manufacturers has shifted sharply since late 2025, and 2026 strategy must be calibrated to these new parameters. The US Department of Commerce initiated a public comment period in October 2025 examining proposals for tariffs reaching 50 percent on bicycle metal content and related derivatives. The trade association PeopleForBikes submitted formal comments opposing the measure, and internal industry communications projected that implementation would trigger layoffs and facility closures among domestic road bike producers. Beyond the immediate tariff headline, the broader implication is a recalibration of landed cost assumptions for aluminum and steel-intensive platforms, which will force pricing recalibration, inventory timing adjustments, and potential sourcing reconfiguration.
Simultaneously, the Union Cycliste Internationale introduced updated fork internal width restrictions effective for the 2026 season, capping front internal widths at 115mm and rear widths at 145mm. While framed as a competitive standardization measure, the rule carries direct engineering consequences. Design teams must validate aero gains, handling characteristics, and tire interface compatibility against the new dimensional envelopes. Manufacturers that can rapidly integrate compliant fork architectures while preserving system-level performance will gain a tangible product window advantage, particularly in racing and high-performance endurance categories. The report documents how rule compliance timelines intersect with product development cycles and supplier qualification processes across the competitive set.
Input cost pressure compounds these regulatory headwinds. Industry communications from 2025 highlighted that raw material expenditures for steel, aluminum, and carbon fiber have risen more than 30 percent in recent years, with pronounced steel and aluminum price surges documented by US-based manufacturers in mid-2025. These cost movements are reshaping frame pricing logic, margin negotiation, and vertical integration assessments. Companies are reevaluating whether to lock in forward material positions, shift geometry emphasis toward higher-margin material categories, or accelerate regionalized component sourcing. Our full market study quantifies the sensitivity of revenue and gross margin profiles to material price trajectories, enabling procurement and finance leaders to model mitigation scenarios with greater precision.
Bicycle Market
Beyond tariffs and materials, industry advocacy groups also advanced regulatory simplification efforts during 2025, including calls for clear e-moto classification standards to prevent high-powered electric motorcycles from being misclassified as e-bikes. While this development primarily affects adjacent categories, it contributes to broader market definition clarity that influences retail channel compliance, insurance frameworks, and consumer expectation management. The complete analysis addresses how adjacent regulatory clarity cascades into road bike category positioning and channel planning.
Competitive Architecture: Incumbent Influence and Tactical Moves
The competitive field leading into 2026 is anchored by a set of globally recognized brands that differentiate through engineering philosophy, material emphasis, and distribution strategy. Specialized, headquartered in Morgan Hill, California, continues to span entry-level aluminum platforms alongside top-tier carbon race machines, using tiered pricing architecture to capture both new riders and professional-grade buyers. Trek Bicycle Corporation, based in Waterloo, Wisconsin, maintains a strong focus on lightweight carbon geometry, with endurance and aerodynamic road lines emphasizing performance geometry and integrated efficiency gains. Cannondale, operating from Bethel, Connecticut, balances aluminum and high-modulus carbon offerings, aligning speed orientation with rider comfort characteristics across its road portfolio.
International manufacturers add significant dimension to the competitive landscape. Giant, headquartered in Taichung, Taiwan, has reinforced its 2026 product calendar with updated aero road platforms targeting measurable efficiency improvements through coordinated cockpit, wheel, and tire refinements. Cervélo, based in Toronto, Ontario, continues to specialize in aero and race road bikes built around advanced carbon construction and UCI-compliant geometries, appealing to serious amateur and professional competitive riders. Pinarello, from Vicenza, Italy, sustains strong brand resonance through lightweight carbon road platforms historically associated with professional team usage. Factor Bikes, located in Berkeley, California, manufactures high-performance road and triathlon platforms that align with evolving UCI fork compliance parameters for 2026. BMC, from Zürich, Switzerland, pursues racing and performance road bikes leveraging Swiss engineering principles, while Canyon, based in Mainz, Germany, maintains a direct-to-consumer model that combines custom geometry, carbon construction, and competitive pricing. Scott, operating from Borgomanero, Italy, emphasizes integrated cable routing and advanced carbon technology across endurance and race road lines, and Bianchi, from Desio, Italy, reinforces its heritage positioning while expanding professional team partnerships and carbon road offerings.
Recent tactical developments illustrate how these companies are timing product and partnership moves to capture demand momentum. In October 2025, PeopleForBikes submitted regulatory comments opposing the proposed metal-content tariff, signaling industry-wide concern about cost escalation. In November 2025, Bianchi finalized a multi-year supply agreement to equip the Bahrain Victorious WorldTour team beginning in 2026, reinforcing visibility and performance credibility at the top tier of competition. In March 2026, Giant introduced its updated aero road platform with an efficiency improvement achieved through cockpit, wheel, and tire refinements. In April 2026, OPEN launched a new gravel road platform with revised geometry and a shift in production to Portugal, reflecting ongoing interest in boundary-blurring road formats and European manufacturing positioning. In May 2026, Canyon released updated endurance and lightweight carbon road models with enhanced frame designs, demonstrating continued iteration in the endurance-to-performance continuum.
These actions are not isolated product events. They reflect a coordinated race to define 2026 relevance across compliance, performance optics, brand visibility, and channel economics. The full report maps each company's product cadence, pricing posture, and strategic emphasis to a unified competitive matrix, allowing readers to compare engineering priorities, launch timing, and market exposure without relying on surface-level brand narratives.
Report Coverage: Operational Intelligence for 2026 Decision Cycles
The complete market study is structured to support immediate operational use while providing strategic depth for multi-year planning. It begins with historical revenue reconstruction across the 2020–2025 period, then extends into a 2026–2032 forecast framework that incorporates material cost sensitivity, regulatory scenario effects, and regional demand divergence. The analysis decomposes market performance across material types and application categories, but the full publication reserves precise segmentation revenue figures and regional share percentages for its detailed appendices, ensuring that decision-makers engage with the complete analytical architecture before deploying granular inputs into internal models.
Beyond aggregate market sizing, the report delivers functional intelligence across multiple dimensions. These include product-level differentiation patterns, technology adoption timelines for carbon and aluminum platforms, distribution channel economics, and pricing architecture comparisons across entry-level, mid-tier, and performance road segments. The study also evaluates how fork compliance requirements, tariff exposure, and raw material inflation interact with each material and application category, helping manufacturers anticipate where margin compression risk is most acute and where premium positioning remains defensible. Supply chain considerations are addressed through the lens of sourcing concentration, regional cost exposure, and the strategic implications of direct-to-consumer versus traditional retail models.
The competitive section goes beyond company descriptions to assess launch sequencing, compliance readiness, brand visibility initiatives, and partnership signaling. It identifies which firms are prioritizing system-level efficiency improvements, which are leaning into geometry customization and production relocation, and which are using professional team associations to reinforce performance credibility. This comparative lens is designed to support product planning, competitive response timing, and channel positioning decisions rather than passive market observation.
Road Bikes Market
Strategic Implications for 2026 Leadership Decisions
The convergence of moderate market concentration, intensifying regulatory scrutiny, and material cost volatility creates a narrow window for strategic clarity. Companies that treat 2026 as a continuation of prior-year operating assumptions risk mispricing material exposure, underestimating compliance redesign cycles, and misreading competitive launch cadence. Conversely, organizations that align product roadmaps, sourcing strategy, and channel economics to the 2026–2032 forecast structure can convert uncertainty into differentiated positioning.
The most immediate implications center on three domains. First, pricing and margin planning must incorporate tariff sensitivity and raw material escalation rather than assuming stable input economics. Second, engineering roadmaps should reconcile performance optimization with UCI fork compliance and evolving geometry expectations, particularly for aero and race-oriented platforms. Third, competitive response timing matters: product updates, partnership announcements, and distribution moves are arriving in rapid succession, and the firms that coordinate these elements with forecast-driven timing will capture disproportionate attention in both retail channels and performance communities.
The full report is designed to support these decisions with disciplined segmentation logic, scenario modeling, and competitor mapping. It provides leadership teams with a defensible basis for capacity planning, portfolio emphasis, and investment prioritization, while protecting the most detailed quantitative inputs for analysts, planners, and strategy teams that need to integrate them directly into internal models.
Next Steps for Strategic Adoption
This brief has outlined the structural logic of the road bikes market as it transitions into the 2026–2032 period, highlighted the regulatory and competitive forces reshaping the operating environment, and described the operational intelligence embedded in the full study. The market trajectory, concentration profile, material cost pressure, and compliance shifts all point to a year in which strategic preparation determines competitive advantage.
Organizations seeking to translate this landscape into concrete action should access the complete report to obtain the full segmentation detail, company-level competitive mapping, and scenario-based forecast inputs required for planning cycles. The publication is intended for executives, product leaders, procurement and finance teams, and investors who need a rigorous, decision-ready view of market direction without relying on partial metrics or generalized industry narratives. Detailed market size figures, segmentation breakdowns, and competitive intelligence appendices are available in the complete version, which can be accessed through our official market research portal for comprehensive analysis and full data integration.
For detailed analysis of this topic, please visit the official page: Road Bikes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TV Wall Mounts Market to Hit $2.945B by 2032, Growing at 7.3% CAGR from 2026
By pmarketresearch, 2026-09-15
TV Wall Mounts Market Strategic Intelligence 2026: Navigating Growth, Supply Chains, and Competitive Shifts
As enterprises recalibrate capital allocation and operational strategies for the 2026 fiscal cycle, the TV Wall Mounts Market has emerged as a focal point for hardware manufacturers, professional AV integrators, retail channel managers, and real estate technology planners. What was once viewed as a mature peripheral accessory category has structurally evolved into a highly engineered support ecosystem driven by display revolutions, ergonomic optimization demands, and increasingly complex supply chain realities. Our newly released comprehensive market study functions as a strategic compass for decision-makers who require forward-looking clarity rather than retrospective summaries. This introduction outlines the analytical architecture of the report, demonstrates why it matters for 2026 planning, and reveals how the embedded frameworks can be operationalized across product roadmaps, procurement strategies, and competitive positioning exercises.
TV Wall Mounts Market
The 2026 Decision Imperative: Why Structural Clarity Matters Now
Market visibility at the aggregate level is merely the starting line. The strategic value of this research lies in its ability to translate macro trajectory into actionable decision nodes for product managers, channel directors, and procurement leaders who must navigate overlapping cycles of consumer upgrade behavior, commercial display standardization, and geopolitical trade recalibration. The global TV wall mount market demonstrated consistent expansion across the 2020-2025 historical window, with base-year valuation settling at 1,800.0 million USD and a forward projection reaching 1,943.9 million USD in 2026. This trajectory reflects a compound annual growth rate of 7.3% spanning the 2026-2032 forecast horizon, ultimately charting toward 2,945.0 million USD by the terminal year. These figures are not abstract indicators; they represent shifting capacity requirements, evolving margin structures, and expanding addressable surfaces across both residential and commercial environments.
For 2026 planning, the critical question is no longer whether the category is expanding, but where value creation is concentrating and which structural frictions will dictate execution speed. The report dissects the market through a multi-layered analytical lens that maps installation behavior, display format migration, channel economics, and regulatory cost transmission into a coherent strategic narrative. Decision-makers gain visibility into how mounting architecture preferences are diverging across use cases, how retail and professional integration channels are competing for margin pools, and how raw material volatility, container logistics, and tariff frameworks are compounding into landed-cost realities. By embedding these dynamics within a unified forecasting architecture, the study enables scenario-based planning rather than static extrapolation.
What the Report Delivers: Operational Intelligence Beyond Headline Figures
A robust market study must bridge the gap between high-level sizing and on-the-ground execution. This publication is structured to support concrete business decisions across multiple functional areas. The analytical framework integrates historical validation, forward-looking forecasting, and segmentation geometry that allows readers to isolate the structural drivers most relevant to their operating context.
- Comprehensive historical reconstruction covering the 2020-2025 baseline, with year-over-year inflection points mapped to technology adoption cycles, installation standardization, and channel expansion patterns.
- Forward forecasting through 2032 that separates baseline growth from demand acceleration scenarios, giving product planning teams a structured basis for capacity commitments, SKU architecture decisions, and inventory positioning.
- Segmentation analysis across mounting architecture types, end-use application environments, and geographic demand distribution, enabling targeted go-to-market alignment without relying on blunt portfolio averages.
- Competitive profiling that maps headquarters positioning, engineering specialization, channel footprint, and value proposition differentiation, allowing strategy teams to benchmark relative positioning and identify whitespace opportunities.
- Regulatory and cost-structure mapping that traces how VESA interface standardization, tariff exclusions, steel input sensitivity, and ocean freight dynamics flow through to production economics and retail pricing architecture.
The report deliberately avoids generic commentary. Every analytical section is anchored in operational questions: Which mounting architectures are capturing disproportionate adoption in premium OLED and large-format display environments? Where are commercial-grade articulating and smart-mount solutions outperforming traditional fixed brackets in professional integration workflows? How are hospitality and specialized healthcare environments reshaping bracket requirements around hygiene, cable concealment, and reconfiguration frequency? The study pulls these threads into a decision-ready format, so readers can align engineering priorities, channel mix, and procurement timing with verified structural signals rather than anecdotal industry noise.
Competitive Architecture: Specialized Engineering and Positioning Divergence
The competitive landscape reflects a clear bifurcation between premium engineered systems and broadly distributed value-oriented brackets, with a meaningful middle tier focused on heavy-duty performance and commercial-grade reliability. This structure matters because it determines how pricing power, channel access, and engineering differentiation interact at the segment level. The market remains moderately concentrated, with the top three players accounting for approximately 38% of revenue and the top five capturing roughly 45%, leaving substantial room for specialized entrants and channel-specific specialists to compete on application fit, installation efficiency, and compatibility assurance.
Strategic positioning varies sharply across the profiled leaders. Sanus continues to emphasize engineered versatility through 4D+Shift tilt and full-motion platforms, outdoor weatherproof configurations, and in-wall enclosures designed for seamless AV integration. Vogel's anchors its competitive identity in premium fixed, tilting, and full-motion brackets, leveraging GuidanceSystem and Elite series engineering to address large-format and OLED TV requirements where precision and finish quality drive purchase decisions. Peerless-AV differentiates through commercial-grade full-motion and smart mount solutions built for professional AV deployments and large-screen display environments. Mount-It! competes with heavy-duty full-motion, XXL, and PRO-series articulating brackets positioned across residential and commercial use cases where load capacity and range of motion are primary purchase drivers.
OmniMount focuses on articulating and ceiling/wall mounting solutions optimized for large 4K and UHD displays, while ECHOGEAR emphasizes budget-friendly full-motion and tilt mounts with strong compatibility coverage and value-led positioning. Kanto targets modern full-motion and articulating bracket designs with contemporary aesthetics and streamlined installation behavior, and VideoSecu provides universal and heavy-duty fixed, tilting, and full-motion mounts for broad TV size ranges, supporting volume-driven deployment scenarios. AVF rounds out the competitive field with commercial and healthcare-specific mount solutions that address sector-specific installation constraints, hygiene considerations, and integration standards.
The strategic takeaway is that product architecture is no longer a commodity discussion. It is a segmentation and channel strategy conversation. Companies that align engineering specialization with end-use requirements and installation efficiency are better positioned to defend margin pools, while broadly generic offerings face intensifying pressure from tariff-sensitive sourcing and freight-cost pass-through dynamics.
2026 Market Dynamics: Trade Policy, Material Costs, and Standardization Pressures
Structural cost pressure and regulatory alignment are reshaping the operating environment for 2026. Several concurrent forces are influencing production economics, sourcing architecture, and compatibility planning, and the report maps each of these dynamics into the forecasting model rather than treating them as isolated events.
Trade policy remains a central variable. Section 301 tariff exclusions on China-related goods were extended through November 10, 2026, affecting import costs for mounted components and creating a temporary buffer for certain supply chain configurations. At the same time, Section 301 tariffs on Chinese-origin goods continue to add 7.5-25% to the cost of most TV wall mounts where applicable, prompting supply chain reconfiguration, dual sourcing evaluations, and regional assembly reconsideration. These dynamics are not uniform; their impact varies by component mix, bill-of-materials composition, and destination market, which is exactly why the study isolates cost-transmission pathways rather than applying blanket assumptions.
Raw material exposure is another critical pressure point. Steel pricing represents roughly 25-35% of the bill-of-materials for typical TV wall mounts, directly affecting production margins and pricing flexibility. This sensitivity means that forecasting accuracy depends not only on demand-side modeling but also on input-cost volatility scenarios and hedging timing. Ocean container freight costs remain structurally higher than pre-pandemic levels, adding approximately 5-10% to landed costs for TV wall mount components. Combined with tariff exposure, these logistics and material factors are compressing margin flexibility and forcing more disciplined SKU economics and inventory planning.
Standardization is simultaneously tightening compatibility expectations. All TV wall mounts must comply with VESA interface standards for mounting hole patterns, and TV manufacturers are updating specifications through 2026 models. This is strategically significant because compatibility assurance now becomes a design, testing, and channel-support function rather than a passive feature. Product teams that anticipate interface evolution, maintain robust compatibility matrices, and align engineering updates with manufacturer specification cycles will reduce returns, installation friction, and channel friction.
Innovation signals are also emerging on the residential side. Displace introduced its Hub wireless wall-mounting system at CES 2026, debuting a smart TV repositioning approach that reduces dependence on traditional mechanical mounts. While this does not immediately displace conventional mounting hardware across the broader market, it signals a broader technology trajectory in which mounting, power delivery, and display flexibility are converging. The report places such developments in context, distinguishing near-term commercial reality from longer-term architectural disruption.
How to Use This Research for 2026 Strategy Execution
The study is designed as an operational tool rather than a static market snapshot. Engineering leaders can use the segmentation and compatibility analysis to prioritize bracket architecture investments, validate load-capacity requirements, and align product roadmaps with display-size migration patterns. Procurement and supply chain teams can leverage the cost-structure mapping to evaluate sourcing sensitivity, assess tariff exposure scenarios, and determine whether regional assembly, inventory buffering, or dual sourcing makes sense under different freight and material price trajectories. Channel and commercial strategy teams can deploy the competitive profiling and application segmentation to identify where installation efficiency, commercial-grade reliability, or premium finish quality creates defensible positioning.
The report also supports scenario planning around demand concentration. Because the market is not uniformly growing across all environments or mounting architectures, decision-makers need to know where adoption is accelerating and where saturation or substitution risk is rising. The forecasting architecture separates baseline momentum from segment-level acceleration so that capacity planning, channel investment, and SKU rationalization decisions can be calibrated instead of speculative.
Ultimately, the strategic value of this research lies in its ability to connect market structure to execution choices. It gives leadership teams a verified reference point for product prioritization, pricing architecture, channel investment, and supply chain resilience. It also preserves analytical integrity by providing the frameworks, ranges, and structural drivers needed to make sound decisions without prematurely exposing the granular figures that underpin proprietary forecasting outputs.
TV & Monitor Mounts Market
Conclusion: Convert Market Visibility Into Competitive Advantage
The TV Wall Mounts Market in 2026 is defined by the intersection of steady demand expansion, engineering specialization, cost-structure complexity, and evolving compatibility standards. Companies that treat mounting hardware as a simple accessory input will miss the strategic implications embedded in bracket architecture, installation efficiency, channel economics, and tariff-sensitive sourcing. Those that approach the category as a structured growth ecosystem can align product design, procurement timing, and commercial positioning with verified market direction. This study provides the intelligence architecture to do exactly that, translating historical validation and forward forecasting into decision-ready insight. For organizations preparing for the 2026 cycle and beyond, the full report offers the complete segmentation detail, competitive mapping, and scenario frameworks required to move from awareness to execution.
For detailed analysis of this topic, please visit the official page: TV Wall Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com