

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
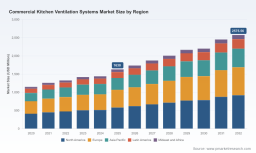
PW Consulting: Commercial Kitchen Ventilation Market to Hit $2,575.56M by 2032 at 6.8% CAGR

Strategic Intelligence for the Modern Kitchen: Inside Our 2026 Commercial Kitchen Ventilation Systems Market Report
The commercial kitchen ventilation sector is entering a decisive inflection point. What was once regarded as a static building infrastructure category is now a dynamic battleground where energy regulation, operational efficiency, and safety compliance intersect. For executives navigating capital allocation, supply chain strategy, and product portfolio optimization in 2026, the installation and service landscape is shifting faster than legacy forecasting models can capture. Our newly published market intelligence report maps this transformation with precision, offering a decision-ready compass for manufacturers, distributors, facility operators, and ecosystem investors across the commercial foodservice value chain.
The industry trajectory tells a clear story of sustained expansion. Drawing on a comprehensive historical window from 2020 through 2025 and projecting forward to 2032, the analysis quantifies momentum that has persisted through supply chain recalibration, labor constraints, and evolving building performance mandates. The underlying market has demonstrated consistent upward movement, with the base year establishing a firm valuation foundation that carries meaningful forward gravity. This calculated growth rate positions the sector as a structurally expanding category rather than a cyclical fluctuation, reinforcing its relevance in long-term strategic planning.
Adoption drivers are no longer limited to code compliance alone. While mandatory standards from the FDA Food Code and NFPA 96 continue to anchor baseline requirements for heat, smoke, grease, and vapor capture, a new layer of operational pressure is reshaping purchasing behavior. The 2021 Uniform Mechanical Code provides the technical framework for safe installation, but the market is now responding to deeper operational imperatives: utility cost volatility, localized emission controls, grease management accountability, and the financial drag of continuously running over-engineered exhaust systems. Against this backdrop, ventilation infrastructure is increasingly evaluated through the lens of total cost of ownership rather than upfront equipment pricing.
Decoding the Structural Composition of the Market
The commercial kitchen ventilation ecosystem is composed of interdependent product categories that collectively determine system performance, compliance outcomes, and lifecycle economics. The report dissects these segments to reveal where value is concentrated, which components face the most intense substitution dynamics, and how procurement patterns differ across installation contexts. Hoods remain the mechanical centerpiece of the category, but their dominance is increasingly measured against the growing strategic importance of exhaust fans, ducting architecture, makeup air balancing, and intelligent control integrations.
Each product pillar interacts with a distinct set of operational realities. Exhaust and ducting infrastructure dictates airflow efficiency and maintenance burden. Makeup air systems govern temperature stability and combustion safety within the kitchen envelope. Controls and accessories, once treated as peripheral add-ons, are now central to modulating fan speeds, matching ventilation output to actual cooking loads, and capturing energy savings in high-utilization environments. The study isolates these structural components not as isolated line items, but as a coordinated system where design choices in one layer directly alter performance, compliance exposure, and long-term operating expense in another.
Application-level demand patterns further complicate procurement planning. Commercial kitchens serve a wide spectrum of operational profiles, from high-turnover quick-service environments to institutional food preparation spaces with extended service hours and specialized ventilation needs. Hospitality venues, educational campuses, corporate and industrial dining facilities, and healthcare institutions each impose different hygiene standards, smoke management thresholds, and sanitation cycles. The report maps these application contexts to clarify where ventilation requirements diverge and where shared system architectures can be leveraged for scale without compromising regulatory alignment.
Regulatory Tailwinds and Technical Shifts Shaping 2026
The competitive and commercial rhythm of this market is being rewritten by regulatory evolution and engineering modernization. In 2025, the California Energy Commission advanced code change proposals targeting energy efficiency improvements and greenhouse gas reductions in commercial kitchens, with potential mandatory adoption of demand-controlled kitchen ventilation as the next progression beyond existing standards. Such developments signal a broader trajectory in which ventilation systems will be evaluated not only for their ability to capture contaminants, but for their capacity to modulate energy consumption in response to real-time cooking activity.
At the same time, foundational compliance expectations remain non-negotiable. FDA-driven public health protections require commercial exhaust systems to reliably capture and contain heat, smoke, grease, and vapors. NFPA 96 continues to mandate rigorous design, installation, and maintenance requirements for commercial cooking operations, while the Uniform Mechanical Code outlines the technical parameters for safe system deployment. These overlapping frameworks create both a compliance floor and a performance ceiling, compelling operators to balance safety assurance with efficiency optimization. The report examines how these regulatory pressures are translating into procurement criteria, service contract expectations, and retrofit decision-making.
Industry participants are already responding with product and service expansions that reflect this shifting mandate. Recent portfolio developments illustrate a clear industry trend toward integrated offering models. For example, a prominent foodservice equipment provider recently broadened its commercial kitchen hood service capabilities to encompass fully engineered ventilation systems, professional consultation, customized hood packages, makeup air units, ventless exhaust configurations, Type 1 and Type 2 hood variants, and specialized applications such as food truck and pizza oven exhaust designs, alongside fire suppression integration and hood filtration accessories. Such moves highlight a market moving from component sales toward end-to-end engineered solutions.
Competitive Landscape: Where Strategy Is Being Won or Lost
The market structure reflects meaningful concentration, with a limited group of established players commanding a significant share of revenue and engineering influence. This concentration shapes pricing dynamics, technology adoption velocity, and the pace at which new entrants can secure footholds in regulated segments. Understanding who leads, where they compete, and how they differentiate is essential for positioning product roadmaps, sales motions, and partnership strategies in 2026 and beyond.
CaptiveAire Systems, Inc., headquartered in Raleigh, North Carolina, stands as a leading manufacturer of commercial kitchen ventilation systems and is recognized for its breadth across exhaust hoods, fans, grease management, and complete HVAC solutions tailored to foodservice operations. Greenheck Fan Corporation, based in Schofield, Wisconsin, complements this competitive tier with a strong portfolio spanning exhaust hoods, fans, makeup air units, and energy recovery ventilation designed for restaurant and foodservice environments. Systemair AB, operating from Skinnskatteberg, Sweden, brings a distinctive emphasis on advanced kitchen exhaust systems, high-performance air purification, smart airflow controls, and demand-controlled ventilation approaches. Together, these players illustrate how leading manufacturers are converging around integrated air management rather than isolated hood fabrication.
A second layer of competition is defined by specialized technology positioning and regional execution strength. Gaylord Industries, located in Tualatin, Oregon, focuses on demand control kitchen ventilation systems, custom kitchen hoods, and pollution control equipment for commercial foodservice. FAST Kitchen Hoods, based in Mississauga, Ontario, has built recognition around cULus-rated commercial kitchen hoods, exhaust systems, island configurations, and low-ceiling solutions for restaurant applications. Chef’s Deal Restaurant Equipment, headquartered in Nashville, Tennessee, operates as both supplier and installer of comprehensive ventilation systems, covering engineered hoods, makeup air units, ventless exhaust, Type 1 and Type 2 grease hoods, and related accessories. This breadth of service orientation reflects an industry trend in which installation capability, customization, and after-sale support have become competitive differentiators, not optional adjuncts.
Commercial Kitchen Ventilation Systems Market
Additional participants continue to shape the market through control innovation and multi-region manufacturing presence. Melink Corporation, with nationwide operations in the United States, provides Intelli-Hood demand control kitchen ventilation systems and controls that target energy-efficient exhaust operations. North American Kitchen Solutions (NAKS), operating across Ohio, Georgia, and Texas, manufactures commercial kitchen hoods, exhaust and supply fans, fire suppression components, and portable ventless hood systems. These profiles underscore a market where product leadership is increasingly linked to control intelligence, modular deployment options, and the ability to serve both permanent and transient kitchen configurations.
Residential Ventilation Systems Market
What the Report Delivers: Actionable Intelligence for Decision-Makers
This study is designed to move beyond surface-level market sizing and into the operational and strategic details that inform investment and execution. The report maps current market size and forward valuation pathways, contextualizes historical performance from 2020 through 2025, and translates that trajectory into a forecast window extending to 2032. The emphasis is not simply on where the market has been, but on how structural variables will shape competitive outcomes over the coming planning cycle.
The analysis provides a practical framework for evaluating product and application dynamics without reducing them to static snapshots. Readers gain visibility into how core product categories relate to one another, where system-level design decisions influence downstream operating costs, and how application contexts alter ventilation priorities. This approach enables stakeholders to assess which segments are likely to attract the most engineering attention, which procurement groups will demand higher specification flexibility, and where service and integration capabilities will become essential to market access.
Equally important, the report situates competitive positioning within a realistic view of market concentration and differentiation levers. Rather than treating competitors as isolated company profiles, the study examines how leading manufacturers and specialized suppliers are aligning product architecture, regional execution, and service scope to capture distinct value pools. It also addresses the regulatory environment as a strategic variable, showing how evolving energy efficiency expectations, ventilation control requirements, and fire safety standards are reshaping procurement criteria and long-term system design philosophy.
Why This Research Matters for 2026 Strategy
The decisions being made in 2026 will determine how organizations position themselves for the next cycle of regulation, energy economics, and foodservice operational complexity. Capital deployed in ventilation infrastructure is no longer a passive compliance expense; it is a strategic asset that affects operating margin, safety performance, and readiness for emerging code requirements. A rigorous understanding of market direction, competitive intensity, and application-specific demand patterns is therefore essential for avoiding stranded investments and misaligned product plans.
This report is structured to support precisely those decisions. It gives executives the analytical clarity to evaluate growth pathways, the competitive context to benchmark positioning, and the operational insight to anticipate where specification, installation, and service expectations will tighten. For manufacturers, it clarifies where product emphasis and engineering investment are most defensible. For distributors and installers, it identifies where service breadth and solution integration will command premium value. For institutional and corporate operators, it supports more informed procurement and retrofit prioritization by linking ventilation design choices to compliance and lifecycle performance.
The broader takeaway is that the commercial kitchen ventilation market is being redefined by the convergence of safety mandates, energy performance expectations, and intelligent airflow control. Organizations that treat ventilation as a system-level discipline, rather than a component-level purchase, will be better positioned to navigate the next phase of market evolution. Our full research study provides the strategic anatomy required to make that transition with confidence.
To access the complete segmentation analysis, forecast timelines, competitive benchmarking, and regional and application-level intelligence behind this overview, we invite you to explore the full report on our website. The detailed data architecture, scenario considerations, and proprietary market mappings contained in the study are designed to support immediate planning as well as longer-range strategic commitment.
For detailed analysis of this topic, please visit the official page: Commercial Kitchen Ventilation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com