

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Connectors Market Hits $7B in 2025, Projects 6.97% CAGR to $11.17B by 2032

Unlocking Strategic Value in the Automotive Connectors Market: A 2026 Decision-Maker's Preview
The automotive connectivity landscape is undergoing a structural transformation driven by electrification, software-defined architectures, and stringent safety mandates. As vehicle architectures consolidate domain controllers and transition toward zonal designs, the demand for precision interconnects has evolved from a commodity consideration to a core engineering and procurement priority. For executives navigating capital allocation, product roadmap planning, and supply chain resilience in 2026, understanding the trajectory of this market is no longer optional—it is a prerequisite for competitive positioning.
Our latest Automotive Connectors Market research publication delivers a comprehensive, forward-looking intelligence framework tailored for strategic decision-making. This article serves as a strategic preview, outlining the analytical depth, operational utility, and competitive context embedded within the full report. While we highlight the macro trajectory and structural dynamics shaping the sector, the granular segmentation breakdowns, regional revenue distributions, and application-specific growth vectors are intentionally reserved for the complete dataset available on our source page.
The Macro Trajectory: Scaling Momentum Through 2032
Historical tracking from 2020 through 2025 reveals a consistent upward progression in global connector revenue, reflecting sustained vehicle production volumes, the gradual phase-in of electrified platforms, and the expanding sensorification of both interior and exterior subsystems. The market has crossed the 7 billion USD threshold in the base year, establishing a robust foundation for the forecast horizon.
Looking ahead, the compounding growth rate projected at approximately 6.97 percent CAGR across the 2026 to 2032 forecast window underscores a market that is not merely expanding, but accelerating its structural complexity. By the close of the decade, total revenue is expected to approach the 11 billion USD mark, signaling a market that will be fundamentally reshaped by higher-voltage architectures, high-speed data transmission requirements, and the standardization of charging interfaces.
This trajectory is not uniform across all technical categories or end-use environments. The interplay between legacy wired harnesses, high-density board-level interconnects, radio frequency signaling components, and fiber optic solutions creates a layered demand profile that requires precise forecasting. Our analysis captures these intersecting growth vectors without reducing them to simplistic linear extrapolations, ensuring that procurement leaders and product strategists can anticipate inflection points rather than merely react to them.
Structural Segmentation: Where Growth Converges and Diverges
The automotive connector ecosystem spans multiple technical typologies, each responding to distinct engineering pressures and cost-performance thresholds. High-reliability board-level interconnects continue to anchor central electronic architectures, while integrated circuit positioning solutions serve the expanding footprint of power management and control modules. Radio frequency and fiber optic interfaces are gaining strategic relevance as vehicles transition toward advanced driver-assistance platforms, in-vehicle infotainment networks, and high-bandwidth telemetry systems.
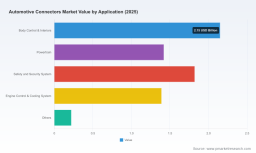
Across the application spectrum, connectivity requirements are being reallocated. Passenger compartment control and interior subsystems maintain substantial volume, while safety and security architectures demand increasingly redundant, fault-tolerant interconnect specifications. Powertrain electrification, engine management, and thermal regulation pathways are driving higher current-carrying capacities and improved environmental sealing. The remaining segments capture emerging niche applications that collectively contribute to incremental but strategically significant revenue streams.
Our full report dissects these segmentation layers with granular precision, mapping absolute market sizing, relative share dynamics, and forward-looking demand elasticity. Rather than presenting static percentage allocations, the analysis contextualizes how technological roadmaps, packaging constraints, and tier-one supplier specifications will redistribute value across categories over the forecast period.
Competitive Landscape: Consolidation, Capability, and Cross-Functional Rivalry
The connector market exhibits a moderately concentrated structure, with a core group of multinational and regional specialists commanding a substantial share of global revenue. This concentration reflects the capital-intensive nature of qualification cycles, the importance of long-term automotive supply chain partnerships, and the technical barriers associated with high-voltage, high-speed, and extreme-environment interconnect solutions.
Several industry leaders define the competitive baseline. TE Connectivity maintains a broad portfolio spanning low-voltage signal and power connectivity across passenger vehicles, commercial trucks, buses, and off-road platforms. Amphenol Corporation focuses on ruggedized interconnect systems engineered for electrified powertrains, hybrid architectures, and advanced sensing deployments. Molex, operating as a Koch Industries company, has introduced high-voltage connector platforms and auxiliary power distribution solutions specifically designed for electric and hybrid vehicle architectures.
Automotive Connectors Market
In Japan, JAE Electronics has expanded its compact, high-density portfolio with high-current variants rated for substantial power throughput, alongside Ethernet-compatible models targeting next-generation in-vehicle networking. Hirose Electric continues to develop performance-oriented interconnects for infotainment and power distribution applications, while Sumitomo Electric Industries supplies high-voltage and wiring harness interfaces tailored to electrified vehicle platforms. Yazaki Corporation remains a major contributor to global wiring harness connector and terminal supply chains.
Asian manufacturing ecosystems contribute additional scale and specialization. KSTerminals emphasizes rigorously tested aftermarket and replacement-grade connectors focused on power and signal reliability. Greenconn Corporation delivers IATF 16949-certified electrical connectors and board-to-board solutions aligned with automotive quality management expectations. Sunkye Electronic Technology provides customized, specification-grade connectors for on-highway and off-highway vehicles, including hybrid applications.
European and cross-regional players further diversify the landscape. Rosenberger Group specializes in high-speed data and RF interconnect solutions for automotive communications and test environments. Aptiv integrates advanced connector and wiring systems directly into vehicle platform architectures, reinforcing the convergence between traditional interconnect suppliers and OEMsupplier system integrators.
The full competitive analysis within the report evaluates these players across revenue positioning, product portfolio breadth, geographic footprint, recent product introductions, and strategic alignment with electrification and connectivity megatrends. Rather than presenting a static leaderboard, the analysis maps competitive vulnerabilities, partnership dependencies, and innovation velocity to help decision-makers anticipate supplier consolidation, pricing pressure, and capacity allocation dynamics.
Recent Developments and Regulatory Accelerators
The market is not evolving in isolation. Recent product launches and standardization efforts are actively reshaping design requirements and procurement timelines. In late 2025, JAE Electronics introduced the MX81D Series, delivering up to 25 amperes for high-power automotive applications, and subsequently expanded its MX34 Series of compact automotive connectors. The same period saw the release of the MX74 Series, engineered for automotive Ethernet 1000BASE-T1 compatibility, reflecting the industry's accelerating push toward high-bandwidth in-vehicle networking.
Simultaneously, standardization bodies and industry consortia are formalizing the technical foundations for next-generation charging and interconnect safety. In May 2025, SAE International published SAE J3400/2, establishing specifications for connectors and inlets supporting the North American Charging System at voltages up to 1000 volts to enable faster EV charging. This followed a broader standardization sequence, including the issuance of the J3400 Recommended Practice for adapters in late 2023 and the publication of the J3400/1 Technical Information Report in April 2025 to improve safety and interoperability across charging interfaces. The US Department of Transportation had previously issued a Request for Information in early 2024 regarding the J3400 connector, signaling potential performance-based standards for EV charging equipment.
Internationally, the ZVEI published the TLF0214 technical guideline in mid-2024, introducing standardized validation procedures for low-voltage automotive connectors at DC levels up to 60 volts. These regulatory and technical specifications do not merely set compliance thresholds; they influence qualification lead times, testing investments, and the competitive positioning of suppliers whose portfolios are aligned or misaligned with emerging standards.
Supply chain resilience introduces an additional layer of complexity. Sentiment from major supplier disclosures highlights the dependency on raw materials such as plastic resins and precious metals, which are often sourced from a limited set of producing countries and subject to geopolitical volatility and import/export licensing constraints. This reality elevates the strategic importance of supplier geographic diversification, inventory buffer strategies, and qualification pathway planning.
Why This Research Matters for 2026 Strategic Decisions
Automotive procurement, engineering leadership, and investment teams face a converging set of challenges in 2026. Connector specifications are no longer determined solely by current rating or form factor; they must account for thermal management, signal integrity at higher data rates, high-voltage isolation, long-term environmental durability, and compatibility with evolving charging and communication standards. Supplier selection increasingly hinges on qualification readiness, geographic supply chain resilience, and the ability to support zonal architecture transitions without introducing costly redesign cycles.
Our report is structured to convert this complexity into actionable intelligence. It provides decision-makers with a defensible basis for capacity planning, supplier negotiation, technology investment, and portfolio prioritization. Rather than offering generic market narratives, the analysis anchors forecasts in verified historical patterns, clearly delineated forecast assumptions, and transparent segmentation logic. The result is a decision-support tool that can be integrated directly into roadmap reviews, sourcing strategies, and competitive benchmarking exercises.
Inside the Report: A Practical, Execution-Oriented Framework
The publication is designed as a multi-layered reference that balances high-level market intelligence with the operational detail required for execution. Core components include a complete market sizing and forecast model spanning historical baselines through the full 2032 outlook, enabling readers to trace growth inflection points and validate internal assumptions. Segmentation analysis is structured to support both technical and commercial planning, allowing engineering teams, procurement groups, and strategy functions to extract relevant views without friction.
Industrial Connectors Market
Competitive profiling goes beyond descriptive summaries. Each major player is evaluated through a consistent analytical lens that considers portfolio alignment with electrification and high-speed data trends, recent product introductions, geographic and manufacturing footprints, and likely strategic priorities over the forecast period. Recent developments, including product launches, standard publications, and technical guideline updates, are mapped to their likely impact on design requirements, qualification timelines, and supplier competitiveness.
The report also integrates regulatory and standardization catalysts into the broader market narrative, ensuring that readers understand not just what is changing, but why it matters for sourcing, testing, and product architecture decisions. By linking standard evolution to practical engineering implications, the analysis helps teams anticipate redesign risk, qualification cost, and supplier capability gaps before they become costly surprises.
Conclusion: Turning Market Complexity into Strategic Advantage
The automotive connectors market is entering a phase where growth is inseparable from technological redefinition. Electrification, zonal architectures, high-bandwidth in-vehicle networks, and formalized charging standards are collectively reshaping the specification, qualification, and sourcing landscape. For organizations making decisions in 2026, the ability to read these shifts early—and to align product, supply chain, and investment strategies accordingly—will determine whether the market is navigated reactively or shaped proactively.
This research preview has outlined the structural context, competitive dynamics, and recent standardization catalysts that define the market environment. The complete report builds on this foundation with detailed segmentation sizing, regional and application-level growth mapping, supplier capability benchmarking, and forecast sensitivity analysis. To access the full dataset, competitive deep dives, and the complete forecast model, please visit the source page for the Automotive Connectors Market research publication and secure the comprehensive intelligence needed to guide your next strategic moves.
For detailed analysis of this topic, please visit the official page: Automotive Connectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com