

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Isoparaffin Solvents Market to Reach $1.14B by 2032 with 3.5% CAGR

Navigating the Isoparaffin Solvents Market: Strategic Intelligence for 2026 Decision-Makers
The global industrial landscape is undergoing a fundamental shift in how solvents are sourced, formulated, and regulated. As environmental compliance tightens and downstream manufacturers demand higher-purity, low-odor, and low-aromatic hydrocarbon solutions, isoparaffin solvents have emerged as a critical link in the value chain. For executives, procurement leaders, and investment strategists, understanding the trajectory of this market is no longer a niche analytical exercise—it is a core component of operational resilience and competitive positioning.
PW Consulting's latest Isoparaffin Solvents Market research report is designed precisely for this moment. Built on rigorous historical reconstruction and forward-looking scenario modeling, the study provides a structured, data-backed roadmap for 2026 planning. Rather than offering a static snapshot, this intelligence synthesizes multi-year demand signals, capacity adjustments, regulatory inflection points, and competitive maneuvers into an executable framework. Below, we outline the core architecture of this analysis and demonstrate why it belongs on your strategic dashboard this year.
Market Trajectory: A Multi-Year Arc of Measured Expansion
The isoparaffin solvents sector has demonstrated steady, compounding growth across the recent historical window, reflecting consistent demand from coatings, industrial cleaning, metalworking, and specialty formulation segments. From a foundational base of approximately 761 million USD in 2020, the market advanced to 766 million USD in 2021, climbed to 803 million USD in 2022, and continued its upward march to 851 million USD in 2023 and 858 million USD in 2024. By 2025, the overall market reached roughly 905 million USD, signaling a mature but still expanding revenue base.
Looking ahead, the forecast horizon through 2032 maps a projected ascent to approximately 1.14 billion USD, underpinned by a compound annual growth rate of 3.5% measured from the base year of 2025. The year-by-year progression—940 million USD in 2026, 983 million USD in 2027, 1.01 billion USD in 2028, 1.06 billion USD in 2029, a slight recalibration in 2030, and continued gains to 1.11 billion USD in 2031 and 1.14 billion USD in 2032—reveals a market that is neither hyper-volatile nor stagnant. Instead, it reflects disciplined expansion shaped by regional capacity investments, formulation substitution trends, and the gradual migration from aromatic-heavy solvent systems toward high-purity isoparaffinic alternatives.
For 2026 decision-makers, this trajectory matters because it establishes a realistic growth ceiling and floor. The 3.5% CAGR is not a headline-grabbing figure, but it carries significant strategic weight: it implies that market share gains, capacity optimization, and formulation agility will be the true differentiators rather than broad-based demand surges. Companies that treat the market as flat risk underinvesting in product readiness, while those that overindex on aggressive volume assumptions may misallocate capital. This report anchors those decisions in a structured, scenario-aware lens.
Segmentation Architecture: Where Value Is Created and Captured
The analytical depth of this study begins with a granular segmentation framework that dissects demand across type, application, and region. Rather than treating isoparaffin solvents as a monolith, the report isolates how different carbon-range families—spanning lighter C8-C9 streams, mid-range C10-C12 grades, heavier C13-C14 formulations, and other specialized variants—map to distinct performance requirements and end-use economics. This type-level breakdown is essential for sourcing teams evaluating compatibility, evaporation profiles, and regulatory fit across coatings, cleaning, and personal care systems.
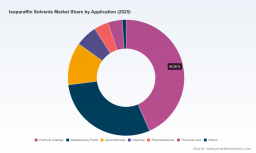
Application-level analysis further sharpens the picture. The research quantifies how paints and coatings continue to serve as a dominant demand anchor, while metalworking fluids, agrochemicals, cleaning formulations, pharmaceuticals, personal care, and other niche applications each present differentiated growth drivers and technical constraints. By separating these verticals, the report equips formulators and procurement leaders with the context needed to anticipate substitution cycles, purity thresholds, and odor control expectations that vary significantly by use case.
Regional distribution is similarly structured to reveal how demand concentrates across northern hemisphere industrial hubs, european compliance-driven markets, asia-pacific manufacturing intensity, and emerging activity in latin america and the mideast and africa. The report's regional architecture does not merely allocate percentages; it interrogates why certain geographies exhibit stronger pull factors, how logistics and feedstock proximity influence cost structures, and where regulatory calendars are likely to accelerate or dampen adoption timelines. This multi-dimensional segmentation is the backbone of the study's actionable recommendations, enabling readers to align product portfolios, inventory strategies, and partnership models with the pockets of highest marginal value.
Isoparaffin Solvents Market
Regulatory Dynamics and Feedstock Realities Reshaping the Landscape
No strategic assessment of the isoparaffin solvents market is complete without confronting the twin forces of compliance and input volatility. Over the 2023–2025 period, regulatory tightening has become a central market dynamic rather than a peripheral risk. South American jurisdictions, including Brazil and Argentina, have moved to tighten VOC emission standards, mandating reduced aromatic content across paints, coatings, and adhesives. In parallel, U.S. EPA VOC limits and the EU Solvent Emissions Directive continue to steer formulators toward high-purity isoparaffin grades as compliant alternatives to traditional aromatic solvents. These frameworks are not static; they are incrementally raising the performance bar for solvent suppliers and rewarding manufacturers who can demonstrate low-aromatic, low-odor, and low-impurity profiles at scale.
Shell Chemicals embodied this regulatory tailwind in 2025 by unveiling an expanded portfolio of high-purity, low-carbon isoparaffin solvents designed to meet tightening environmental compliance. Such portfolio expansions signal more than marketing posture; they reflect capital allocation toward grades that satisfy both performance and compliance criteria simultaneously. The broader implication for 2026 is clear: regulatory alignment is increasingly inseparable from commercial viability. Brands and converters that evaluate solvent suppliers solely on price per liter risk downstream reformulation costs, compliance exposure, and reputational friction.
Feedstock volatility, meanwhile, introduces a persistent margin tension. Isoparaffin solvents remain sensitive to hydrocarbon feedstock pricing and supply disruptions, which can compress production economics and alter competitive cost positioning. The report integrates these raw-material dynamics into its forecasting logic, allowing readers to stress-test pricing assumptions against plausible input-cost scenarios. By coupling regulatory timelines with feedstock sensitivity analysis, the study transforms what is often treated as an external shock into a manageable planning variable.
Competitive Landscape: Established Majors and Strategic Capacity Moves
The competitive field in isoparaffin solvents is defined by a concentrated but diversified set of global producers, each leveraging distinct feedstock positions, regional footprints, and brand portfolios. Shell plc remains a leading supplier through its ShellSol isoparaffins, high-purity synthetic hydrocarbon solvents characterized by narrow boiling ranges and low impurities, with applications spanning coatings, inks, dry cleaning, and industrial uses. Chevron Phillips Chemical Company continues to manufacture Soltrol isoparaffin solvents, including Soltrol 130, a low-odor grade compatible with parts cleaning, degreasing, paints, inks, and agrochemical formulations. Exxon Mobil Corporation produces the Isopar brand of high-purity isoparaffinic fluids for personal care, coatings, cleaning, and metalworking, emphasizing low aromatic content and odorless properties.
Beyond these major anchors, the market features a capable tier of regional and specialized producers. Braskem S.A. contributes isoparaffinic hydrocarbon solvents within its broader industrial and specialty portfolio. TotalEnergies SE supplies isoparaffin solvents across paints, coatings, and formulations. INEOS Group produces isoparaffins for industrial cleaning, coatings, and personal care applications. Idemitsu Kosan Co., Ltd. offers IP Clean and IP Solvent products for industrial and specialty uses. Calumet Specialty Products Partners, L.P. focuses on isoparaffinic solvents for hydrocarbon applications in industrial cleaning and coatings. Sasol Limited manufacturers isoparaffin-based solvents as part of its chemical portfolio, and SK Global Chemical produces ISOL isoparaffins for industrial solvents and formulations.
Market concentration metrics underscore the structural balance between incumbency and opportunity: a CR3 of approximately 28.3% and a CR5 of about 32.1% indicate a landscape where top-tier players hold meaningful share while ample room remains for differentiated positioning, specialty grades, and regional service excellence. This concentration profile matters for 2026 strategy because it suggests that competitive advantage will increasingly accrue to firms that combine technical reliability with agile compliance readiness, rather than those competing solely on volume.
Recent corporate developments reinforce this interpretation. In February 2025, Shell Chemicals inaugurated a new isoparaffin solvent production plant in Brazil, increasing local capacity by 30%. That same spring, Chevron Phillips Chemical Company increased its manufacturing capacity for isoparaffin solvents. By mid-2025, ExxonMobil Chemical updated the technical datasheet for Isopar M, highlighting low aromatic content, and Shell Chemicals released an updated product datasheet for ShellSol emphasizing low odor and suitability for surface coatings. These moves—capacity additions, datasheet refreshes, and regional expansions—are not isolated events; they are coordinated signals of where incumbents are placing bets on demand, compliance, and application performance. The report maps these developments against demand pockets and regulatory calendars, helping readers distinguish between routine capacity updates and strategically significant market repositioning.
What the Report Delivers: Operational Intelligence for 2026 Planning
This study is structured to convert macro insight into operational clarity. The report combines historical reconstruction with forward-looking forecasts, segmentation analysis, competitive profiling, and regulatory mapping into a unified decision-support framework. Specifically, readers gain access to:
- A multi-year market size and CAGR trajectory that anchors volume and revenue expectations across the forecast window, enabling scenario planning for production, inventory, and capital allocation.
- Segment-level analysis by type and application that clarifies where purity, odor, boiling range, and compatibility requirements drive premium positioning and where cost-competitive grades retain relevance.
- Regional demand distribution that highlights where compliance calendars, manufacturing intensity, and feedstock logistics converge to shape cost and availability dynamics.
- A competitive landscape assessment covering major and specialized producers, including capacity moves, product updates, and portfolio expansions that signal shifting supply-side priorities.
- Regulatory and raw-material context that integrates VOC standards, aromatic-content mandates, and feedstock volatility into planning assumptions rather than treating them as external noise.
- Actionable interpretative guidance for procurement, formulation, market entry, and partnership decisions, tailored to the realities of a moderately growing but compliance-sensitive market.
Importantly, the full report goes beyond the summary figures and qualitative themes previewed here. It provides the detailed split data, forecast tables, and segment-by-segment interpretations that procurement and strategy teams need to validate internal assumptions, benchmark supplier proposals, and prioritize investment across grades and geographies. The executive summary and preview narrative are designed to establish trust and demonstrate analytical rigor; the complete dataset and methodology are reserved for the full study, ensuring that subscribers receive the depth required for board-level and operational decision-making.
Solvent Naphtha Market
Why This Research Matters for 2026 Strategic Decisions
As organizations enter 2026 planning cycles, the isoparaffin solvents market presents a classic strategic paradox: growth is steady but unspectacular, compliance pressure is rising but predictable, and competitive differentiation is increasingly technical rather than transactional. In such environments, the cost of imprecise intelligence is high. Overbuying low-demand grades ties up working capital; underinvesting in compliant, low-aromatic portfolios exposes formulators to regulatory and customer-requirement risk; and misreading regional capacity shifts can leave supply chains exposed to localized constraints.
This report is built to reduce that uncertainty. By fusing historical performance, forecast logic, segmentation detail, competitive signaling, and regulatory context into a single coherent architecture, it gives decision-makers a shared reference point for conversations across procurement, R&D, sales, and finance. The 3.5% CAGR and the multi-year size progression provide a realistic growth baseline; the segmentation framework identifies where value concentrates; the competitive and regulatory mapping reveals where incumbents are investing and where compliance will reshape demand; and the operational guidance translates all of this into planning-relevant choices.
For leaders who need to move from awareness to action, the full study offers the granular evidence base required to set grade strategies, evaluate supplier roadmaps, anticipate reformulation triggers, and align capacity or sourcing decisions with the regions and applications most likely to reward precision. The preview presented here demonstrates the analytical standard and the strategic lens of the research; the complete report delivers the execution-ready intelligence that turns that lens into decisions.
For detailed analysis of this topic, please visit the official page: Isoparaffin Solvents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com