

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Road Bikes Market Hits $3.85B in 2025, Forecast to Reach $5.49B by 2032

Road Bikes Market Strategic Intelligence 2026: Navigating Growth Amid Regulatory Shifts
The global road bikes market stands at a pivotal inflection point as it enters the 2026–2032 forecast window. After a decade of steady volume expansion and material innovation, manufacturers now face a complex matrix of regulatory uncertainty, raw material volatility, and rapidly evolving consumer expectations. Our latest comprehensive market study transforms this complexity into a clear strategic roadmap. By integrating historical performance data, forward-looking modeling, and granular competitive intelligence, the research equips executive teams with the analytical precision needed to allocate capital, position product portfolios, and secure supply chains in a highly consolidated industry.
This introductory brief outlines the structural contours of the market, highlights the operational realities shaping decision-making in 2026, and demonstrates how our full report delivers actionable intelligence for stakeholders across manufacturing, distribution, and investment functions. The analysis deliberately reserves core segmentation metrics for the complete publication, ensuring that readers understand the strategic architecture of the study before accessing the detailed quantitative appendices.
Market Trajectory and Structural Foundations
The road bikes market has demonstrated consistent monetization growth over the past five years, with total industry revenue climbing from 3.12 billion USD in 2020 to an estimated 3.85 billion USD by 2025. This trajectory reflects sustained demand across performance-oriented and utilitarian segments, supported by expanding cycling infrastructure, rising health-conscious mobility preferences, and incremental consumer spending on durable recreational goods. The base year close establishes a resilient foundation, though the pace and composition of future growth will diverge meaningfully across geographies, material categories, and end-use applications.
Forward projections place the market on a compound annual growth path of approximately 4.85 percent through 2032, culminating in a valuation that materially outpaces the prior five-year cadence. Growth acceleration will not be uniform. Instead, it will be shaped by three interlocking forces: the maturation of carbon fiber adoption in mid-tier and endurance road platforms, the competitive pressure on aluminum and steel segments as price sensitivity intensifies, and the geographic realignment of demand as emerging cycling markets develop distribution networks and brand recognition. The full study models these vectors through scenario-based forecasting, enabling leadership teams to test portfolio assumptions against multiple macroeconomic and regulatory conditions rather than relying on single-point estimates.
Crucially, the market remains moderately concentrated. The top three participants collectively account for roughly 42.5 percent of global revenue, while the top five expand that share to 58.0 percent. This concentration profile indicates that margin protection, brand loyalty, and channel control remain decisive advantages, but it also signals meaningful whitespace for regional specialists and direct-to-consumer entrants that can exploit geometry customization, localized assembly, or niche performance positioning. Our report dissects how these concentration dynamics interact with product lifecycle timing, pricing elasticity, and distribution strategy, providing a comparative framework that helps both incumbents defend category leadership and challengers identify defensible entry points.
Regulatory and Supply Chain Dynamics Redefining Competitive Position
The operating environment for road bike manufacturers has shifted sharply since late 2025, and 2026 strategy must be calibrated to these new parameters. The US Department of Commerce initiated a public comment period in October 2025 examining proposals for tariffs reaching 50 percent on bicycle metal content and related derivatives. The trade association PeopleForBikes submitted formal comments opposing the measure, and internal industry communications projected that implementation would trigger layoffs and facility closures among domestic road bike producers. Beyond the immediate tariff headline, the broader implication is a recalibration of landed cost assumptions for aluminum and steel-intensive platforms, which will force pricing recalibration, inventory timing adjustments, and potential sourcing reconfiguration.
Simultaneously, the Union Cycliste Internationale introduced updated fork internal width restrictions effective for the 2026 season, capping front internal widths at 115mm and rear widths at 145mm. While framed as a competitive standardization measure, the rule carries direct engineering consequences. Design teams must validate aero gains, handling characteristics, and tire interface compatibility against the new dimensional envelopes. Manufacturers that can rapidly integrate compliant fork architectures while preserving system-level performance will gain a tangible product window advantage, particularly in racing and high-performance endurance categories. The report documents how rule compliance timelines intersect with product development cycles and supplier qualification processes across the competitive set.
Input cost pressure compounds these regulatory headwinds. Industry communications from 2025 highlighted that raw material expenditures for steel, aluminum, and carbon fiber have risen more than 30 percent in recent years, with pronounced steel and aluminum price surges documented by US-based manufacturers in mid-2025. These cost movements are reshaping frame pricing logic, margin negotiation, and vertical integration assessments. Companies are reevaluating whether to lock in forward material positions, shift geometry emphasis toward higher-margin material categories, or accelerate regionalized component sourcing. Our full market study quantifies the sensitivity of revenue and gross margin profiles to material price trajectories, enabling procurement and finance leaders to model mitigation scenarios with greater precision.
Bicycle Market
Beyond tariffs and materials, industry advocacy groups also advanced regulatory simplification efforts during 2025, including calls for clear e-moto classification standards to prevent high-powered electric motorcycles from being misclassified as e-bikes. While this development primarily affects adjacent categories, it contributes to broader market definition clarity that influences retail channel compliance, insurance frameworks, and consumer expectation management. The complete analysis addresses how adjacent regulatory clarity cascades into road bike category positioning and channel planning.
Competitive Architecture: Incumbent Influence and Tactical Moves
The competitive field leading into 2026 is anchored by a set of globally recognized brands that differentiate through engineering philosophy, material emphasis, and distribution strategy. Specialized, headquartered in Morgan Hill, California, continues to span entry-level aluminum platforms alongside top-tier carbon race machines, using tiered pricing architecture to capture both new riders and professional-grade buyers. Trek Bicycle Corporation, based in Waterloo, Wisconsin, maintains a strong focus on lightweight carbon geometry, with endurance and aerodynamic road lines emphasizing performance geometry and integrated efficiency gains. Cannondale, operating from Bethel, Connecticut, balances aluminum and high-modulus carbon offerings, aligning speed orientation with rider comfort characteristics across its road portfolio.
International manufacturers add significant dimension to the competitive landscape. Giant, headquartered in Taichung, Taiwan, has reinforced its 2026 product calendar with updated aero road platforms targeting measurable efficiency improvements through coordinated cockpit, wheel, and tire refinements. Cervélo, based in Toronto, Ontario, continues to specialize in aero and race road bikes built around advanced carbon construction and UCI-compliant geometries, appealing to serious amateur and professional competitive riders. Pinarello, from Vicenza, Italy, sustains strong brand resonance through lightweight carbon road platforms historically associated with professional team usage. Factor Bikes, located in Berkeley, California, manufactures high-performance road and triathlon platforms that align with evolving UCI fork compliance parameters for 2026. BMC, from Zürich, Switzerland, pursues racing and performance road bikes leveraging Swiss engineering principles, while Canyon, based in Mainz, Germany, maintains a direct-to-consumer model that combines custom geometry, carbon construction, and competitive pricing. Scott, operating from Borgomanero, Italy, emphasizes integrated cable routing and advanced carbon technology across endurance and race road lines, and Bianchi, from Desio, Italy, reinforces its heritage positioning while expanding professional team partnerships and carbon road offerings.
Recent tactical developments illustrate how these companies are timing product and partnership moves to capture demand momentum. In October 2025, PeopleForBikes submitted regulatory comments opposing the proposed metal-content tariff, signaling industry-wide concern about cost escalation. In November 2025, Bianchi finalized a multi-year supply agreement to equip the Bahrain Victorious WorldTour team beginning in 2026, reinforcing visibility and performance credibility at the top tier of competition. In March 2026, Giant introduced its updated aero road platform with an efficiency improvement achieved through cockpit, wheel, and tire refinements. In April 2026, OPEN launched a new gravel road platform with revised geometry and a shift in production to Portugal, reflecting ongoing interest in boundary-blurring road formats and European manufacturing positioning. In May 2026, Canyon released updated endurance and lightweight carbon road models with enhanced frame designs, demonstrating continued iteration in the endurance-to-performance continuum.
These actions are not isolated product events. They reflect a coordinated race to define 2026 relevance across compliance, performance optics, brand visibility, and channel economics. The full report maps each company's product cadence, pricing posture, and strategic emphasis to a unified competitive matrix, allowing readers to compare engineering priorities, launch timing, and market exposure without relying on surface-level brand narratives.
Report Coverage: Operational Intelligence for 2026 Decision Cycles
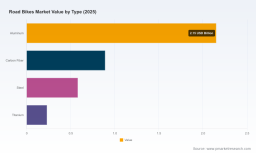
The complete market study is structured to support immediate operational use while providing strategic depth for multi-year planning. It begins with historical revenue reconstruction across the 2020–2025 period, then extends into a 2026–2032 forecast framework that incorporates material cost sensitivity, regulatory scenario effects, and regional demand divergence. The analysis decomposes market performance across material types and application categories, but the full publication reserves precise segmentation revenue figures and regional share percentages for its detailed appendices, ensuring that decision-makers engage with the complete analytical architecture before deploying granular inputs into internal models.
Beyond aggregate market sizing, the report delivers functional intelligence across multiple dimensions. These include product-level differentiation patterns, technology adoption timelines for carbon and aluminum platforms, distribution channel economics, and pricing architecture comparisons across entry-level, mid-tier, and performance road segments. The study also evaluates how fork compliance requirements, tariff exposure, and raw material inflation interact with each material and application category, helping manufacturers anticipate where margin compression risk is most acute and where premium positioning remains defensible. Supply chain considerations are addressed through the lens of sourcing concentration, regional cost exposure, and the strategic implications of direct-to-consumer versus traditional retail models.
The competitive section goes beyond company descriptions to assess launch sequencing, compliance readiness, brand visibility initiatives, and partnership signaling. It identifies which firms are prioritizing system-level efficiency improvements, which are leaning into geometry customization and production relocation, and which are using professional team associations to reinforce performance credibility. This comparative lens is designed to support product planning, competitive response timing, and channel positioning decisions rather than passive market observation.
Road Bikes Market
Strategic Implications for 2026 Leadership Decisions
The convergence of moderate market concentration, intensifying regulatory scrutiny, and material cost volatility creates a narrow window for strategic clarity. Companies that treat 2026 as a continuation of prior-year operating assumptions risk mispricing material exposure, underestimating compliance redesign cycles, and misreading competitive launch cadence. Conversely, organizations that align product roadmaps, sourcing strategy, and channel economics to the 2026–2032 forecast structure can convert uncertainty into differentiated positioning.
The most immediate implications center on three domains. First, pricing and margin planning must incorporate tariff sensitivity and raw material escalation rather than assuming stable input economics. Second, engineering roadmaps should reconcile performance optimization with UCI fork compliance and evolving geometry expectations, particularly for aero and race-oriented platforms. Third, competitive response timing matters: product updates, partnership announcements, and distribution moves are arriving in rapid succession, and the firms that coordinate these elements with forecast-driven timing will capture disproportionate attention in both retail channels and performance communities.
The full report is designed to support these decisions with disciplined segmentation logic, scenario modeling, and competitor mapping. It provides leadership teams with a defensible basis for capacity planning, portfolio emphasis, and investment prioritization, while protecting the most detailed quantitative inputs for analysts, planners, and strategy teams that need to integrate them directly into internal models.
Next Steps for Strategic Adoption
This brief has outlined the structural logic of the road bikes market as it transitions into the 2026–2032 period, highlighted the regulatory and competitive forces reshaping the operating environment, and described the operational intelligence embedded in the full study. The market trajectory, concentration profile, material cost pressure, and compliance shifts all point to a year in which strategic preparation determines competitive advantage.
Organizations seeking to translate this landscape into concrete action should access the complete report to obtain the full segmentation detail, company-level competitive mapping, and scenario-based forecast inputs required for planning cycles. The publication is intended for executives, product leaders, procurement and finance teams, and investors who need a rigorous, decision-ready view of market direction without relying on partial metrics or generalized industry narratives. Detailed market size figures, segmentation breakdowns, and competitive intelligence appendices are available in the complete version, which can be accessed through our official market research portal for comprehensive analysis and full data integration.
For detailed analysis of this topic, please visit the official page: Road Bikes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com