

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Engine-Driven Welders Market Hits $1,380M in 2025, Forecast 4.91% CAGR to 2032

The Engine-Driven Welders Market: Strategic Intelligence for the 2026 Decision-Maker
The industrial equipment landscape is undergoing a quiet but decisive transformation. As infrastructure projects multiply across emerging economies and legacy assets in developed markets demand intensive rehabilitation, the demand for reliable, mobile power and welding solutions has never been more critical. For executives in manufacturing, procurement, and strategic planning, navigating this space requires more than surface-level consumption forecasts. It demands a rigorous understanding of engine technology adoption, regional demand shifts, regulatory pressures, and the competitive maneuvers shaping the next seven years of market evolution.
PW Consulting's latest research initiative delivers a comprehensive, forward-looking analysis of the Global Engine-Driven Welders Market. Anchored in historical data spanning 2020 through 2025 and projecting through 2032, this report provides the analytical rigor necessary to allocate capital, refine product roadmaps, and anticipate competitive disruption. What follows is an executive preview of the market architecture, the forces driving its trajectory, and the proprietary analytical frameworks embedded within our full publication.
A Market Navigating Growth and Structural Realignment
Over the past half-decade, the engine-driven welders sector has demonstrated remarkable resilience, rebounding from supply chain bottlenecks and transitioning into a phase of measured, sustainable expansion. Current market valuations reflect a maturing industry that has successfully absorbed post-pandemic operational adjustments while capitalizing on the global construction and energy pipeline boom. The research models a clear upward trajectory, with total market revenue positioning itself for steady accumulation through the end of the forecast period.
At the core of this forecast lies a moderate yet consistent compounding growth rate, signaling an industry that is expanding beyond cyclical volatility and settling into a pattern driven by fundamental industrial demand, technological refinement, and strategic fleet modernization. Decision-makers will find that the growth narrative is not monolithic; rather, it is segmented by propulsion technology preferences, regional economic priorities, and application-specific operational requirements. Our analysis deconstructs these layers to reveal where value creation is most concentrated and where margin pressures may emerge.
Welding Equipment Market
Crucially, the report does not merely project headline numbers. It maps the underlying demand vectors, correlating equipment adoption rates with macroeconomic indicators, project financing cycles, and evolving on-site labor economics. By isolating these dynamics, we provide leadership teams with a diagnostic lens to stress-test their market assumptions and align their strategies with the components of growth that are most sustainable.
Technological Divergence and the Mobility Imperative
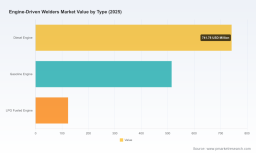
The modern engine-driven welder category is defined by a fundamental operational trade-off: portability and self-sufficiency versus fuel efficiency and emissions compliance. Within this tension, manufacturers are pursuing divergent engineering philosophies. Diesel-powered platforms continue to anchor heavy-duty and remote operations, capitalizing on torque reliability and extended runtime capabilities. Gasoline-driven units maintain strong footholds in lighter commercial and maintenance applications, where rapid deployment and lower upfront costs drive purchasing decisions. Meanwhile, LPG-fueled alternatives are carving out niche positioning, particularly in markets with stringent indoor or urban emissions regulations.
This technological segmentation is not merely a product classification exercise; it represents a strategic fork in the roadmap for equipment manufacturers and fleet operators alike. The research evaluates how engine architecture choices interact with total cost of ownership, service interval economics, and regional fuel availability. For procurement leaders, understanding the operational profile of each propulsion type is essential when aligning equipment specifications with project duration, site logistics, and local compliance frameworks.
Furthermore, the integration of auxiliary power generation into welding platforms has transformed these machines from single-purpose tools into multi-role assets. On active jobsites, this convergence directly reduces the logistical footprint of supporting equipment and mitigates the need for separate generator rentals. Our analysis quantifies the operational efficiency gains that arise from this consolidation, demonstrating how labor allocation and equipment utilization metrics shift when welding and power generation are unified into a single mobile unit.
Regulatory Pressure, Raw Material Volatility, and Operational Resilience
The engine-driven welders market operates at the intersection of mechanical engineering, emissions regulation, and commodity economics. Manufacturers and end-users alike must navigate an increasingly complex compliance environment, particularly in jurisdictions where engine emissions standards are tightening to align with broader environmental policy objectives. Recent product developments from leading OEMs highlight a clear industry response: new platform introductions are being engineered from the ground up to meet rigorous duty-cycle requirements while maintaining compact footprints suitable for service vehicles and confined job site logistics.
Simultaneously, raw material cost fluctuations remain a persistent variable in the manufacturing equation. Alternator components, control electronics, and engine subsystems are subject to supply chain pricing dynamics that ripple directly into production margins and, ultimately, end-user pricing strategies. The report incorporates scenario modeling that accounts for these input cost pressures, enabling readers to assess how different procurement and pricing architectures may hold up under periods of commodity volatility.
For competitive strategists, the regulatory and input-cost environment is not merely a constraint; it is a source of differentiation. Companies that can streamline compliance engineering, localize assembly where advantageous, and optimize bill-of-materials resilience are positioned to capture pricing power and market share. Our analysis highlights how the leading participants are structuring their operational responses to these external pressures, offering a template for evaluating internal capability gaps.
Competitive Architecture: Navigating an Oligopolistic Landscape
The competitive structure of this market is characterized by a high degree of concentration among established equipment manufacturers, with a handful of multinational players commanding a substantial share of industry revenue. This oligopolistic dynamic creates a market environment where brand recognition, service network density, and product lineage play decisive roles in procurement decisions. However, it also presents opportunities for focused differentiation, particularly among regional specialists and agile OEMs that can adapt quickly to localized application requirements and emerging market niches.
Our competitive profiling extends well beyond corporate biographies. The research evaluates each major participant through the lens of product architecture, engine partnerships, geographic assembly strategies, and end-market specialization. Large-cap manufacturers have historically leveraged established distribution channels and bundled service offerings to sustain market leadership, while mid-tier and regional producers have pursued competitive advantage through compact design optimization, fuel efficiency claims, and targeted deployment in agricultural, field-service, and export-oriented applications.
The report further examines the strategic significance of recent product launches that signal the industry's direction. New-generation platforms are increasingly emphasizing advanced arc performance, expanded generator capacity, and duty-cycle robustness tailored to harsh construction and industrial environments. These introductions reflect a broader market consensus: the next wave of competitive advantage will belong to manufacturers that can deliver high-utilization reliability without compromising mobility or compliance readiness. By mapping these product strategies against regional demand profiles, our analysis provides a tactical view of where competitive intensity is likely to escalate and where whitespace may still exist.
For strategic planners, understanding the concentration of market power is essential. The research provides a detailed assessment of how incumbent players are defending their positions through product portfolio breadth, technology licensing, and service ecosystem expansion, as well as where acquisition, partnership, or geographic entry strategies may reshape the competitive hierarchy over the forecast horizon.
Demand Vector: Where the Market Finds Its Pulse
The application landscape for engine-driven welders is diverse, stretching across heavy civil construction, pipeline installation and maintenance, mining operations, and broader infrastructure development. Each application segment carries distinct operational requirements, utilization patterns, and procurement cycles. In construction environments, for example, the ability to deploy self-contained power and welding capability directly to intermittent work zones translates into measurable efficiency gains. Pipeline and energy-sector projects demand equipment that can sustain prolonged duty cycles under remote or extreme conditions. Mining operations, meanwhile, prioritize fuel endurance, ruggedness, and compatibility with existing fleet logistics.
Our segmentation analysis isolates these application-specific drivers to reveal which end-use categories are generating the most consistent revenue streams and which are most sensitive to macroeconomic cycles or commodity price fluctuations. Rather than presenting static splits, the report contextualizes each application's growth potential within the broader framework of project financing, labor availability, and equipment utilization economics. Readers will gain a nuanced view of where fleet replacement demand, incremental capacity expansion, and new-project initiation are converging to drive volume.
Regional demand patterns are examined with equal rigor. The study evaluates how varying rates of infrastructure investment, energy sector activity, and industrial modernization shape geographic consumption profiles. By correlating regional project pipelines with equipment specification trends, the research identifies markets where localized assembly, distribution partnerships, or tailored product configurations may offer the highest strategic return. These insights are particularly valuable for organizations considering geographic expansion, export strategy refinement, or regional supply chain reconfiguration.
Report Architecture: Operational Intelligence for Strategic Execution
The full PW Consulting publication is engineered to be a working document, not merely a reference summary. Its architecture is designed to support cross-functional decision-making across product management, sales leadership, procurement, and corporate strategy. The report integrates quantitative market modeling with qualitative competitive assessment, delivering a unified view of market behavior and structural risk.
Core components of the analysis include a detailed historical reconstruction of market revenue dynamics from 2020 through 2025, a transparent demand-side forecast extending through 2032, and a segment-level diagnostic that maps propulsion technology preferences, application utilization profiles, and geographic consumption patterns. The research also incorporates a rigorous competitive benchmarking framework, profiling leading manufacturers and their strategic postures, recent product introductions, and regional assembly or distribution strategies.
In addition to market sizing and segmentation, the publication delivers forward-looking assessments of regulatory trajectory, input-cost exposure, and labor economics that directly influence equipment adoption. Scenario modeling is embedded throughout, enabling readers to evaluate how changes in compliance requirements, fuel pricing, or project financing conditions may alter demand momentum. The result is an analytical toolkit that can be applied to capital planning, product roadmap prioritization, pricing strategy, and market-entry evaluation.
Executive summaries, graphical data representations, and structured competitor matrices are integrated to ensure rapid assimilation of key insights, while the underlying methodology and source documentation provide the audit trail necessary for internal validation and board-level review.
Engine-Driven Welders Market
Strategic Takeaways for 2026 and Beyond
The engine-driven welders market is entering a phase where disciplined strategic positioning will separate long-term winners from reactive participants. Several high-level implications emerge clearly from our analysis. First, the market's growth trajectory is anchored in structural industrial demand rather than speculative cycles, creating a favorable environment for product innovation and service-led revenue expansion. Second, competitive differentiation will increasingly depend on the ability to balance compliance readiness, fuel efficiency, and field durability without sacrificing portability or total cost competitiveness.
Third, the concentration of market power among leading OEMs does not preclude opportunity; it reframes it. Regional specialists, export-focused manufacturers, and entrants with differentiated product configurations can capture value by serving application segments or geographic pockets where incumbent coverage is less dense or where localized assembly and service models confer a decisive advantage. Finally, the integration of labor-saving functionality, auxiliary power capability, and compliance-forward engineering is not a peripheral feature set; it is becoming a central purchasing criterion that will shape procurement specifications and fleet replacement cycles for years to come.
For decision-makers preparing their 2026 portfolios, the imperative is clear: base strategic commitments on granular, forward-validated market intelligence rather than on aggregate industry narratives.
Accessing the Full Research Intelligence
This article offers a strategic preview of the market architecture, competitive dynamics, and operational forces shaping the engine-driven welders sector. The underlying research contains a far more granular dissection of market sizing, segment-level demand modeling, competitive benchmarking, regulatory scenario mapping, and regional consumption diagnostics. Those detailed breakdowns are essential for calibrating investment thresholds, prioritizing product development, and validating market-entry assumptions.
To access the complete dataset, forecast tables, competitor profiles, and scenario frameworks, we invite you to consult the full PW Consulting Engine-Driven Welders Market research publication. The complete report provides the analytical depth required to translate market awareness into executable strategy.
For detailed analysis of this topic, please visit the official page: Engine-Driven Welders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com