

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Air Intake Resonator Market to Reach USD 1,291.2 Million by 2032, Growing at a 6.85% CAGR

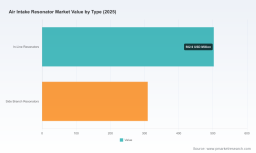
Air Intake Resonator Market: A Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases an executive industry briefing that distills the strategic implications of our full Air Intake Resonator Market study. As OEMs, tier suppliers, aftermarket specialists and private equity investors set budgets and roadmaps for 2026, this briefing highlights the forces reshaping the resonator value chain, the investment levers that matter, and the practical next steps to convert macro trends into defensible, near-term competitive advantage.
Worldwide Enterprise Database Management Suite Market
Executive snapshot
The global air intake resonator market has evolved from a niche noise-control component into a system-level design consideration embedded in air management strategies across powertrains. Our analysis shows a sustained expansion trajectory: the market moved from a mid-single‑hundreds USD million base in 2020 to a stronger position by 2025, and is projected to grow at a compound annual growth rate (CAGR) of 6.85% over the 2026–2032 forecast period. By 2032 the market is on course to be materially larger than in 2025, reflecting an intersection of regulatory pressure, rising demand for NVH-optimised combustion systems, and aftermarket performance trends.
Worldwide Colored Glass Bead Market
Why 2026 is a strategic inflection point
- Regulatory pressure (for example, tightening combustion emissions standards) makes air intake performance a lever for both compliance and optimization. Investments made in 2026 will influence vehicle architectures and supplier relationships for the remainder of the decade.
- Raw material and thermal-design tradeoffs are converging with manufacturing-tech advancements. These dynamics change cost curves and determine which resonator technologies are scalable for different vehicle architectures.
- Competitive consolidation and vertical integration are accelerating. Our concentration metrics indicate that a handful of established players exert meaningful influence, but room remains for specialization, especially where thermal resilience and integrated system design matter.
Market trajectory and what it means for budgets
The market’s historical progression underscores recovery and expansion phases that have been reshaping supplier economics. Between 2020 and 2025 the sector expanded notably, and our forecast through 2032 shows continued growth driven by OEM platform refresh cycles, aftermarket demand for performance and acoustic tuning, and regulatory-driven reinvestment in intake systems. For 2026 planners, two budgetary implications follow:
Forestry Seeds Market
- Capex and R&D allocation should prioritize integrated air management — not isolated resonator parts. Investments in design tools, prototype validation for NVH and flow, and materials testing deliver outsized returns compared with incremental part-only upgrades.
- Sourcing strategies must account for material- and manufacturing-driven cost volatility. Suppliers that can offer validated material substitutions or hybrid component architectures mitigate procurement risk while preserving performance thresholds.
Materials and design: the trade-offs that matter
Material selection is a practical battleground where design objectives (noise attenuation, thermal endurance, weight, and cost) compete. Two material realities deserve special attention in 2026 planning:
- Polypropylene (PP) remains attractive where cost and lightweighting dominate. Its lower material cost—on the order of double-digit percentage savings versus higher-performance polymers—supports volume applications where intake temperatures remain moderate. However, PP’s thermal ceiling constrains its use in turbocharged or high-underhood temperature environments.
- Glass-fiber-reinforced polyamides (PA6/PA66) retain preference for premium, turbocharged and high-thermal-load applications because of their superior thermal resistance and dimensional stability. While costlier, they lower risk in high-temperature service and permit more compact geometries and integrated assemblies.
The practical implication: companies that can validate material performance with costed manufacturing routes — and demonstrate NVH and durability equivalence in system-level tests — will win specification slots as OEMs rationalize architectures under emissions and acoustic constraints.
Competitive landscape: established leaders and emergent opportunities
The market exhibits a mixed structure: sizeable global players with system-integration expertise coexist with specialized aftermarket and component suppliers. Our industry mapping highlights incumbent strengths and adjacent opportunities:
- MANN+HUMMEL (Ludwigsburg, Germany) — a filtration and systems leader offering integrated air cleaner housings and resonators; strong OEM relationships and systems know-how are core advantages.
- Röchling Automotive (Mannheim, Germany) — specializes in high-frequency resonators and integrated duct systems; their capability in acoustics engineering supports premium and performance applications.
- Toyoda Gosei (Inazawa, Japan) — provides hose and duct solutions with noise-absorbing features tailored to engine efficiency and intake noise reduction.
- Magna International (Aurora, Canada) — leverages broad vehicle systems engineering to offer resonators as part of larger powertrain and thermal management solutions.
- K&N Engineering (Riverside, USA) — an aftermarket performance player introducing NextGen intake systems that influence aftermarket demand and provide insights into consumer-driven acoustic and airflow preferences.
Recent product activity in the aftermarket (for example, cold-air intake launches and performance-focused systems) signals a continuing two-track market: OEM-driven, regulation-sensitive systems on one side, and performance-led aftermarket innovations on the other. Market concentration indicators show that the top players capture a disproportionate share of value, but specialized suppliers with acoustics, materials, or integration IP can still carve defensible niches.
Practical content in the PW Consulting report
Our full study is intentionally operational: beyond forecasts it supplies decision-ready assets that executives will use in 2026 planning cycles.
- Modular strategic playbooks for OEMs and tier suppliers — including product roadmaps, specification prioritization matrices, and supplier selection criteria.
- Cost-to-serve and materials-cost modelling templates with sensitivity analysis for PP versus PA architectures and reinforced material formulations.
- Manufacturing economics assessment — tooling CAPEX profiles, cycle-time benchmarks, and scale-entry thresholds for injection-moulded and hybrid assemblies.
- Regulatory scenario analyses — Euro 7 and comparable regimes modelled for how intake-system performance affects combustion optimization and emissions compliance, under multiple vehicle mileage and duty-cycle assumptions.
- Competitive intelligence dossiers — executive profiles, recent moves, technology patents and partnership heatmaps for the leading suppliers and targeted challengers.
- M&A and partnership playbook — a prioritized shortlist of targets and capability gaps, with valuation multipliers and integration risk checklists tailored to resonator and intake-system assets.
- Action templates — 90/180/365 day tactical plans for procurement, validation, and go-to-market for aftermarket channels.
How decision-makers should use this intelligence in 2026
Whether you are an OEM engineering director, a tier supplier head of strategy, or an investor assessing platform plays, the report supports three clear 2026 use cases:
- Portfolio prioritization: allocate R&D and platform capital to intake-system architectures where material and acoustic advantages yield the highest impact on emissions, fuel/energy efficiency, and brand-differentiated NVH.
- Sourcing and supplier governance: apply our materials and cost models to renegotiate supply agreements, evaluate material-substitution pilots, and set procurement guardrails around thermal-performance confidence levels.
- M&A and partnership targeting: use the deal playbook to identify bolt-on capabilities (acoustic modelling, multi-material assembly, aftermarket distribution) and accelerate time-to-market through alliances or strategic acquisitions.
Risk factors and mitigation levers
Executives must weigh three principal risks and the mitigating actions we recommend:
- Raw material volatility and substitution risk — mitigate with dual-sourcing strategies and qualification of hybrid-material designs backed by accelerated thermal/aging validation.
- Regulatory uncertainty — hedge with modular designs that allow incremental performance upgrades without full-platform redesigns; prioritize systems that offer measurable combustion benefits.
- Competitive displacement from vertically integrated suppliers — respond by deepening system-integration capabilities or locking strategic long-term supplier agreements tied to performance KPIs.
Conclusion and recommended next steps
Our analysis shows that air intake resonators are no longer peripheral components: they are leverage points for emissions strategy, acoustic differentiation, and cost optimization. The market’s trajectory through 2032—underpinned by a 6.85% CAGR over the forecast window—creates both pressure and opportunity. For 2026, the decisive actions are clear: reallocate R&D toward system-level validation, redesign procurement to capture material-driven cost and performance upside, and use targeted partnerships or M&A to acquire missing acoustics or materials expertise.
PW Consulting’s full Air Intake Resonator Market report provides the datasets, proprietary models and tactical templates to implement these recommendations. To access the complete forecasts, segment-level analytics, supplier matrices and actionable playbooks, visit the PW Consulting report landing page and download the executive package. The full report preserves the detailed regional and application splits, scenario tables, and validated supplier profiles that you will need to finalize 2026 budgets and strategic priorities.
For detailed analysis of this topic, please visit the official page: Air Intake Resonator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com