

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EV Charger Market Hits $25.55B in 2025, Poised for 18.12% CAGR Through 2032

Navigating the Electric Vehicle Charger Market: Strategic Intelligence for 2026 Decision-Makers
The global transition toward electrified transportation has moved beyond early adoption curves and entered a phase of structural scaling. For executives, investors, and strategic planners, 2026 represents a critical inflection point where infrastructure deployment, regulatory compliance, and competitive positioning converge. Our latest Electric Vehicle Charger (EVC) Market research delivers a disciplined, data-grounded assessment of this evolving landscape, designed to inform capital allocation, product roadmaps, and market entry strategies throughout the forecast horizon.
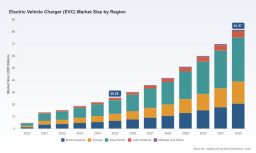
The market has demonstrated remarkable momentum over the past half-decade. Revenue expanded from approximately 4.82 billion USD in 2020 to 25.55 billion USD in 2025, reflecting a compound trajectory that underscores both consumer adoption and enterprise fleet transition. Looking ahead, the forecast period extending to 2032 projects sustained expansion, with the market anticipated to reach 81.57 billion USD by the terminal year. This growth is anchored by a forecast CAGR of 18.12 percent, a figure that signals durable demand rather than speculative hype. Navigating this environment requires more than top-line visibility; it demands a granular understanding of technology shifts, regional deployment patterns, competitive maneuvers, and the regulatory frameworks that will shape operational feasibility.
Market Architecture and Forecast Trajectory
The EVC market is no longer a monolithic category. It has differentiated into distinct technology tiers, application environments, and geographic corridors, each with its own adoption drivers, margin structures, and deployment constraints. Our research maps these layers systematically, allowing stakeholders to evaluate where value is created, where bottlenecks persist, and how capital should be weighted across the stack.
Technology Segmentation and Power Architecture
Charging infrastructure has bifurcated into three principal power categories, each serving different use cases and customer expectations. Level 1 chargers continue to serve low-intensity residential and light commercial needs, while Level 2 deployments form the backbone of workplace, multi-family, and retail environments. Level 3 DC fast charging represents the highest-growth and highest-complexity segment, targeting public corridors, fleet depots, and heavy-duty applications where downtime minimization is paramount. The revenue mix across these categories reflects a market that is simultaneously maturing in baseline residential and commercial installations while accelerating toward high-power public and fleet-facing solutions.
Application Environments and Deployment Logic
Demand is distributed across residential, commercial, and public application environments, but the strategic implications differ sharply by segment. Residential installations are shaped by consumer incentives, home energy integration, and installation logistics. Commercial deployments are increasingly driven by fleet electrification, workplace charging programs, and property-value considerations for retail and hospitality venues. Public infrastructure remains the most policy-sensitive segment, dependent on corridor planning, utility coordination, grid capacity, and municipal permitting regimes. Understanding how these application environments interact with technology tiers is essential for companies deciding whether to prioritize volume-oriented residential products, commercial fleet solutions, or high-power public hub architectures.
Geographic Distribution and Regional Priorities
Revenue activity spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, but the strategic weight of each region varies according to policy intensity, vehicle sales mix, utility readiness, and supply chain positioning. Some markets are advancing through coordinated public investment and corridor planning, while others are pulling forward through private fleet commitments and residential adoption. The research breaks down regional dynamics without oversimplifying them, enabling stakeholders to assess where near-term revenue is most accessible and where long-term positioning requires patience, local partnerships, or regulatory engagement.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a concentrated but dynamically shifting field. The market exhibits a CR3 of 28.5 percent and a CR5 of 35.2 percent, indicating that while leading players command meaningful share, the remaining landscape is open to specialized entrants, regional specialists, and technology-first innovators. This structure rewards companies that can combine hardware performance, software integration, service reliability, and deployment speed.
XCharge: High-Power DC and Grid-Integrated Systems
XCharge, headquartered in Kyle, Texas, has built its identity around high-power DC fast charging solutions, including 400 kW C7 chargers and GridLink battery-integrated systems designed for grid support and public fleet applications. The company's recent expansion underscores a commitment to scaling production capacity for advanced high-power hardware. In April 2026, XCharge North America opened a new 3,000 sqm assembly plant in Valencia, Spain, focused on C7 400 kW chargers and GridLink solutions. This move signals a strategic emphasis on manufacturing flexibility, regional deployment capability, and the integration of storage-coupled charging architecture that can mitigate grid constraints at high-demand sites.
Kempower: Modular DC Fast Charging and Ecosystem Partnerships
Kempower, based in Lahti, Finland, manufactures modular DC fast chargers, including the Station Charger platform capable of up to 400 kW and Power Module systems tailored for public hubs, fleets, and heavy-duty vehicles. The company's modular philosophy enables scalable deployment and operational flexibility, which is particularly valuable for operators managing variable demand profiles across sites. In January 2026, Kempower announced a global partnership with DC fast charger OEM Tritium to simplify EV charger payment enablement. This collaboration highlights a broader industry shift toward reducing friction in user experience and transaction processing, areas that increasingly differentiate operators in public and fleet segments.
Enphase Energy: Bidirectional Charging and Energy Integration
Enphase Energy, headquartered in California, produces AC and DC bidirectional EV chargers through its IQ Bidirectional platform, enabling vehicle-to-home and vehicle-to-grid integration with compatible solar systems. As energy management becomes inseparable from charging infrastructure, bidirectional capability positions Enphase at the intersection of EV adoption and distributed energy resources. In February 2026, Enphase Energy announced that it would begin volume manufacturing of the IQ Bidirectional EV Charger platform in Q4 2026 following product demonstrations. This timeline reflects a deliberate transition from demonstration to scaled production, aligning with growing interest in home energy resilience, solar coupling, and grid services enabled by parked electric vehicles.
Regulatory Dynamics and Operational Imperatives
Regulatory frameworks are no longer peripheral considerations; they are becoming central to site selection, product design, service commitments, and financial modeling. Several recent developments illustrate how policy is reshaping operational expectations across the EVC value chain.
In April 2026, the California Energy Commission adopted Electric Vehicle Charging Data and Reliability Standards, effective April 2026. These standards require semi-annual reporting of charger inventory and uptime for entities operating EV chargers, with exclusions for single-family homes and multi-family homes with four or fewer units. This creates a formal accountability layer for commercial and public operators, elevating uptime and transparency as measurable performance metrics rather than aspirational goals.
Related reliability expectations were reinforced in October 2025, when the California Energy Commission established that entities operating EV chargers installed on or after January 1, 2024 must maintain a minimum annual average uptime rate of 97 percent for the first six years after installation. For operators and OEMs, this standard changes the economics of maintenance, remote monitoring, and component durability. It also raises the stakes for companies that can demonstrably deliver higher reliability through modular architecture, predictive service, and faster fault resolution.
Ev Charging Card Market
On the supply chain and manufacturing side, the proposed modification of Buy America requirements for EV charger projects obligated on or after October 1, 2025 mandates that all manufactured products must be manufactured in the United States. Published as a Federal Register Notice of Proposed Modification in February 2026, this development has direct implications for sourcing strategy, domestic production capacity, and the cost structure of projects seeking federal support. Companies with flexible manufacturing footprints or domestic assembly capabilities may gain a distinct advantage in qualifying for funded deployments.
Incentives continue to shape end-user economics as well. The Alternative Fuel Vehicle Refueling Property Credit allows up to 1,000 USD tax credit per charging port for eligible equipment installed at principal residences, according to IRS guidance issued in March 2026. This credit supports residential adoption and can influence the value proposition of home charging products, particularly when bundled with energy management features or installation services.
Electric Vehicle Charger (EVC) Market
Report Scope and Decision-Ready Content
Our Electric Vehicle Charger Market research is structured to translate complex market signals into actionable intelligence. Rather than offering a static snapshot, the report is designed as a working reference for teams that need to evaluate opportunities, manage risk, and prioritize initiatives across the 2026 to 2032 horizon.
- Historical and forecast revenue analysis grounded in a 2025 base year, with backward visibility from 2020 to 2025 and forward projections through 2032, enabling trend validation and scenario planning.
- Technology-level assessment across Level 1, Level 2, and Level 3 charger categories, with attention to power ratings, deployment contexts, and the operational trade-offs that influence product strategy.
- Application-level analysis covering residential, commercial, and public segments, helping stakeholders align product features, pricing, and go-to-market models with the needs of each environment.
- Regional evaluation across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, supporting market prioritization, partnership screening, and localized expansion planning.
- Competitive profiling of leading participants, including XCharge, Kempower, and Enphase Energy, with coverage of product architectures, recent operational developments, and strategic moves that signal where the market is heading.
- Regulatory and policy tracking that connects standards, incentives, and procurement requirements to practical implications for deployment feasibility, compliance burden, and cost structure.
- Concentration and share dynamics that contextualize the competitive field, helping companies gauge where differentiation is most needed and where scale or niche positioning may be more effective.
The research is built for cross-functional use. Strategy teams can use it to frame market entry and expansion decisions. Product and engineering leaders can use it to triangulate technology investment against demand signals. Sales and business development teams can use it to identify high-potential segments and align messaging with the operational realities of each application environment. Finance and investor relations teams can use it to ground revenue expectations in a transparent trajectory rather than anecdotal momentum.
Strategic Implications for 2026 Planning
The EVC market in 2026 is defined by three interlocking realities. First, demand is broad enough to support multiple business models, but not uniform enough to reward undifferentiated playbooks. Residential, commercial, and public segments each require distinct installation logic, customer engagement, and service commitments. Second, technology choice is increasingly a strategic variable rather than a specification detail. The balance between Level 1, Level 2, and Level 3 deployments shapes everything from site selection and grid interaction to user experience and maintenance economics. Third, regulatory and incentive environments are maturing in ways that reward reliability, transparency, and compliant manufacturing footprints.
Companies that treat uptime as a core product attribute, not a service afterthought, will be better positioned for markets where reliability standards are becoming explicit. Organizations that can align hardware, software, and payment or energy-integration capabilities will have an easier path to reducing friction for end users and operators alike. Firms with manufacturing and supply chain flexibility will be more resilient to procurement rules and regional content requirements that are beginning to influence project qualification. And stakeholders that understand the interplay between charging infrastructure and distributed energy resources will be better prepared for a market in which vehicles, homes, solar systems, and grids increasingly operate as a connected system rather than separate silos.
The trajectory from 25.55 billion USD in 2025 toward 81.57 billion USD by 2032 is not merely a growth statistic. It is a signal that the market is scaling into a strategically complex environment where execution quality, regulatory literacy, and segment-specific positioning determine who captures durable advantage. This research is designed to help decision-makers move beyond surface-level optimism and into the operational and competitive details that actually shape outcomes.
Why This Research Matters Now
Market momentum alone does not create strategy. The value of this report lies in its ability to convert a fast-moving landscape into a structured basis for choice. By combining historical context, forecast visibility, technology and application segmentation, regional dynamics, competitive profiling, and regulatory tracking, the research gives stakeholders a shared framework for discussing where to invest, what to build, and how to compete.
For organizations planning 2026 initiatives, the report provides the kind of decision intelligence that reduces uncertainty without oversimplifying it. It highlights where demand is most concentrated, where reliability and compliance are becoming decisive, and where leading companies are placing their bets through product launches, manufacturing expansion, and partnership activity. It also preserves enough analytical depth to support internal debate, while remaining focused on the practical questions that executives and project teams face day to day.
The Electric Vehicle Charger market is entering a phase in which the winners will be those who can integrate technology, operations, policy, and customer experience into a coherent strategy. Our research is built to support that effort, offering a clear view of the market's current architecture and the forward dynamics that will shape the next several years.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Charger (EVC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com