

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PM2.5 Monitors Market to hit USD 770 Million by 2032 at a 6.98% CAGR

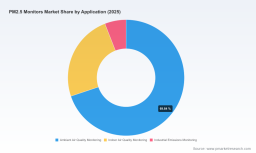
PM2.5 Monitors Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise but insight-rich preview of our forthcoming PM2.5 Monitors Market study. This piece is designed to orient senior executives, procurement leads, investors, and public-sector planners as they set priorities for 2026. It demonstrates the analytical depth of the full report while deliberately withholding granular segmentation outputs and proprietary scorecards — the exact intelligence that will drive operational choices and M&A moves is available in the complete study on our website.
PM2.5 Monitors Market
Market trajectory you need to internalize
The PM2.5 monitors market has moved from a niche regulatory niche into a mainstream technology category that straddles environmental policy, public health, and IoT-enabled services. Our modeling, based on a detailed historical series (2020–2025) and an explicit forecast window (2026–2032), shows a clear expansion path: the market reached an institutionalized scale by the 2025 base year and is projected to grow at a compounded annual growth rate (CAGR) of roughly 6.98% across the forecast period. By the end of the outlook horizon, the market is materially larger than in 2025, reflecting both sustained regulatory upgrade cycles and growing private-sector adoption of continuous monitoring.
PM2.5 Monitors Market
For executives, the takeaway is simple: procurement, product development, and channel strategies framed around a single-year mindset will miss the structural growth in demand. Capital allocation for monitoring networks, service contracts, and data platforms must be planned across multi-year tranches to align with regulatory timetables and technology refresh cycles.
PM2.5 Monitors Market
Regulatory inflection points that accelerate demand
-
Standard tightening: The U.S. Environmental Protection Agency’s reduction of the primary annual PM2.5 National Ambient Air Quality Standard has been a catalyst for network upgrades. That regulatory tightening translated into practical procurement waves as networks moved to comply with stricter thresholds.
-
Method designations and approvals: Updated lists of reference and equivalent methods (including recent designations in late 2025) directly alter the vendor landscape by elevating devices that meet reference-grade performance. Vendors that hold or actively pursue these designations become default suppliers for regulated networks and competitive in bid processes for municipal and state contracts.
-
Network modernization: Several jurisdictions that historically relied on filter-based FRMs have transitioned to continuous analyzers. That shift has implications for capital timing, operational budgets, and data comparability between legacy and modern systems.
These regulatory signals are not academic. They create discrete windows during which municipalities and national authorities commit to upgrade or expand monitoring capacity — windows that vendors, integrators, and financiers must target with tailored offerings and finance structures.
Competitive landscape: fragmented but credibility-driven
The market remains moderately fragmented, with top-tier suppliers accounting for a small but meaningful slice of global revenue. Market concentration metrics indicate that the largest three players control roughly a quarter of the market, with the top five approaching one-third — a structure that favors both specialized entrants and consolidation plays. In practice, this means two viable strategic postures for vendors and investors: commit to scale and pursue consolidation, or specialize deeply in validated reference-grade instrumentation and data services.
Key vendor archetypes and implications:
-
Regulatory reference-grade incumbents: Established manufacturers offering FRM/FEM-capable instruments have a durable advantage for government networks. Their certification pathways and long-term service arrangements often secure multi-year revenues tied to network operations. Recent EPA-level designations have reinforced the market positions of several long-standing suppliers.
-
Innovative entrants with validated performance: Newer vendors that obtain reference- or equivalent-method recognition can leapfrog into regulated procurements. Certification events in 2025 demonstrate that when a device proves reference-grade performance, market access expands rapidly.
-
Portable and citizen-science players: The lower-cost, portable, and wearable segments are expanding in parallel — driven by corporate wellness, smart-building applications, and consumer awareness. These devices shift the competitive focus toward sensor calibration, data harmonization, and lightweight analytics rather than pure hardware sales.
-
Systems and platform integrators: Firms that combine hardware supply with cloud-based analytics, QA/QC workflows, and managed services can capture higher-margin recurring revenue and lock in long-term data service contracts with municipal and enterprise clients.
Representative vendors covered in the full study — spanning reference-grade manufacturers, OEMs of beta attenuation and tapered element oscillating microbalance (TEOM) systems, portable sensor specialists, and integrators — are analyzed across validation status, route-to-market, service footprint, and capability synergies. Recent developments we track carefully include the EPA’s late-2025 designations and high-profile vendor certifications that materially affect competitive positioning.
What the PW Consulting report delivers (practical, operational outputs)
-
Robust market sizing and a transparent forecasting model (history: 2020–2025; forecast: 2026–2032) that links demand to regulatory milestones, capex cycles, and product lifespans.
-
A regulatory tracker that maps designation timelines, standard setting, and state-level network plans to procurement windows.
-
Vendor profiles and a comparative framework that score firms on validation status, installed base, service capability, and platform readiness.
-
Technology assessment covering measurement principles (beta attenuation, TEOM, optical particle counters, gravimetric samplers), drift characteristics, calibration strategies, and IoT integration patterns.
-
Go-to-market playbooks for manufacturers and system integrators: RFP tactics, financing structures for fleet upgrades, and channel strategies for hybrid public–private opportunities.
-
Procurement and specification checklists, including QA/QC process templates and sample bid evaluation criteria tailored for municipal and corporate buyers.
-
Scenario-based investment cases and M&A target shortlists for strategic acquirers and private equity, with metrics to prioritize candidates.
-
Methodology appendix: primary interviews, calibration lab validations, and sensitivity testing so buyers and investors can audit our assumptions.
To preserve the tactical value of our analysis for subscribers, the full report refrains from public disclosure of proprietary segment splits and device-level pricing benchmarks. Those items are available exclusively in the paid study and are unavoidable inputs when executing procurement or M&A activity.
Strategic implications for 2026 planning — by stakeholder
-
Municipal and state air agencies: Prioritize interoperability and device validation. Where possible, procure FEM/FRM-designated instruments for compliance networks and leverage hybrid strategies (continuous analyzers + low-cost sensor arrays) to expand spatial coverage without compromising compliance-grade data.
-
Equipment manufacturers: Invest in demonstration programs that accelerate recognition by regulatory authorities. Certification is a gateway to the largest and stickiest contracts; concurrent investments in aftermarket services can convert hardware sales into recurring revenue.
-
Systems integrators and platform providers: Build standardized ingestion pipelines and QA/QC toolsets that normalize data across device types and generations. Offer managed services that reduce operational burden for public-sector customers facing tight budgets.
-
Investors and acquirers: Look for targets with validated measurement performance, strong service contracts, or cloud analytics that promise recurring cash flow. The relatively modest headroom in market concentration suggests attractive roll-up opportunities in regional markets.
-
Corporate sustainability teams: Factor in multi-year replacement cycles and data quality requirements when specifying monitors for campuses and facilities. High-frequency, verifiable data becomes a corporate asset for regulatory engagement and stakeholder communication.
Immediate next steps for teams planning 2026 budgets and programs
-
Map compliance timelines against capital planning cycles. Use multi-year procurement frameworks to smooth budget impact and secure vendor lead times.
-
Prioritize pilot projects that pair certified reference instruments with low-cost sensor networks to validate hybrid approaches under local conditions.
-
Require vendor demonstrations tied to QA/QC acceptance criteria and ensure long-term maintenance contracts are benchmarked professionally.
-
Engage early with potential partners who have confirmed method designations or who are on certification roadmaps; that shortens procurement cycles and mitigates regulatory misalignment risk.
Our full PM2.5 Monitors Market report unpacks these actions into executable timelines, vendor scorecards, and procurement-ready specifications. It is intentionally structured as a decision-support tool for teams that must translate regulatory pressure into compliant, cost-effective monitoring networks.
How to access the complete intelligence
This preview highlights the strategic arcs and high-level metrics you need to include in 2026 planning. The full report contains the proprietary segmentation, vendor rankings, pricing matrices, and downloadable models that your procurement, product, or M&A teams will use to finalize decisions. Visit the PW Consulting research portal to review the executive package, secure client briefings, and access our modeling toolkit.
If you would like a tailored briefing for your organization — including scenario modeling against your specific fleet, geography, and budget constraints — our consultants are available to convert the study’s insights into a 90-day action plan.
For detailed analysis of this topic, please visit the official page: PM2.5 Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com