

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ion Beam Machining Market Poised for 7.85% CAGR, Report Forecasts Robust 2026–2032 Growth

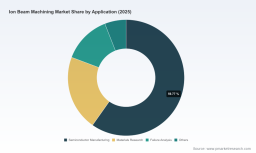
Ion Beam Machining Market 2026: Strategic Imperatives for Leaders — PW Consulting Preview
As PW Consulting publishes its flagship Ion Beam Machining Market report, this briefing outlines the high-level implications that senior executives, corporate strategists, and investment committees must factor into 2026 planning cycles. Built on a robust 2020–2025 historical base and a 2026–2032 forecast framework, the analysis projects a resilient expansion trajectory — driven by advanced semiconductor nodes, next‑generation photonics and optics, and intensifying demand for precision materials analysis. Our model anticipates the market to expand from a 2025 base of USD 215.75 Million to a materially larger industry by 2032, reflecting a compound annual growth rate (CAGR) of 7.85% across the forecast horizon. This release is a strategic “preview”: it surfaces the decision‑critical insights and actionable implications while preserving the granular segment-level intelligence for report subscribers.
AI Server Low Dielectric Glass Fiber Market
Why Ion Beam Machining Matters to 2026 Corporate Strategy
Ion beam machining (IBM) technologies — including focused ion beam (FIB), broad ion beam (BIB) and emerging plasma-based ion systems — are now mission‑critical in three strategic domains: advanced semiconductor manufacturing, high-precision optics/coatings, and materials science research & failure analysis. For technology OEMs and capital equipment investors, IBM is less a niche process and more a leverage point for enabling tighter tolerances, higher yields, and new device architectures (e.g., heterogeneous integration, photonic integration, and advanced packaging). The projected mid‑single‑digit to high‑single‑digit CAGR reflects both sustained demand for replacement and retrofit systems as well as a wave of new unit deployments tied to capacity expansions and R&D investments.
Wireless Network Simulator Market
Market Structure and Competitive Dynamics — What Leaders Should Read First
Two structural features define competitive dynamics and should shape boardroom deliberations in 2026:
Engine Compartment Protective Panel Assembly Market
- Consolidation and Concentration: The industry exhibits a moderate level of concentration among the top players, reflecting high technical barriers, IP intensity, and capital requirements. This concentration supports premium pricing for differentiated platforms but also creates acquisition windows for fast‑moving challengers and specialized service providers.
- Platform Diversification: Market leaders are pursuing multi‑technology portfolios — combining FIB, PFIB, and broad ion beam capabilities with software, automation, and service contracts — to capture end‑to‑end value and to reduce cyclicality tied to capex spending patterns of end customers.
Key incumbents profiled in our study exhibit distinct but complementary competitive plays. Some vendors emphasize precision thin‑film and optical coatings; others push integrated FIB‑SEM and high‑throughput failure analysis solutions. Meanwhile, specialized service providers and regional OEMs deploy nimble product programs and local service networks to win aftermarket share.
Recent Strategic Moves That Signal the Next Phase
- Product modularity and platform launches are accelerating: recent modular platforms bring together ion beam and plasma processes onto configurable toolsets, shortening time‑to‑qualification for multi‑process customers.
- Order flows into optical and laser supply chains point to renewed capex activity in select photonics segments, indicating pockets of above‑market growth outside pure semiconductor fabs.
- Broad ion beam tooling for sample preparation and cooling configurations have moved from laboratory staples into higher‑throughput production settings, unlocking new addressable use cases.
These directional shifts are evident in multiple vendor announcements over the past 18 months and are reflected in our scenarios for 2026 planning. For practitioners, the strategic question is not whether to play in ion beam, but how to structure participation — direct OEM play, system rental and service, software and automation, or vertical integration with end‑user fabs and research institutions.
Supply Chain and Technology Risks: What to Monitor Closely
Two risk vectors deserve board‑level attention in 2026:
- Raw material and source dependencies: Traditional FIB tools commonly rely on gallium liquid metal ion sources. This creates potential supply chain vulnerability to gallium availability and price volatility. Companies should stress‑test procurement and consider alternative ion sources or dual‑sourcing strategies where feasible.
- Process artifacts and rework needs: Post‑FIB implantation can introduce surface amorphization and contamination that necessitate follow‑up milling or low‑energy broad ion polishing. Product roadmaps that incorporate downstream mitigation (e.g., argon/xenon polishing, plasma treatments) will offer superior yield and lower total cost of ownership for end customers.
Regulatory and quality frameworks remain exacting — ion beam equipment must meet high‑vacuum and precision manufacturing standards. This reality elevates the importance of validated supply chains, accredited calibration services, and robust documentation for customers operating in regulated sectors.
Strategic Playbook — Four High‑Impact Moves for 2026
From our work with OEMs, fab operators, and private equity clients, the following four moves consistently preserve optionality and maximize upside in an IBM ecosystem growing at ~7.85% CAGR.
- Prioritize modularity and software differentiation: Invest in control software, AI‑driven process recipes, and modular hardware architectures that enable rapid reconfiguration. Software licensing and remote diagnostics materially increase annuity‑style revenue and improve gross margins.
- Pursue targeted M&A and partnership plays: Given the sector’s concentration dynamics, smaller acquisitions or licensing deals can accelerate entry into complementary process domains (e.g., PFIB, deposition/etch hybrids) faster than organic R&D alone.
- Shift to solutions and services: Expand into process development, application labs, and uptime guarantees. Service‑heavy contracts reduce customer capex sensitivity and create sticky long‑term relationships.
- Hedge supply risks and redesign consumable strategies: Secure multi‑year supply agreements for strategic feedstock, qualify alternate ion sources, and re‑engineer consumable lifecycles to reduce single‑supply dependencies.
What Our Full Report Delivers — Practical Tools for Decision‑Making
Our full Ion Beam Machining Market report goes beyond narrative and delivers executable assets that teams can use immediately in 2026 strategy cycles. Highlights include:
- Revenue and unit shipment models with scenario toggles for high/medium/low demand trajectories across the 2026–2032 horizon.
- Competitor scorecards and product roadmaps that benchmark technology readiness, service coverage, and commercialization timelines.
- CapEx and TCO calculators tailored to OEMs and end‑users that quantify payback periods under alternative utilization rates.
- An M&A screening matrix that flags targets by strategic fit, integration complexity, and accretion/dilution sensitivities.
- Supply chain risk heatmaps and mitigation playbooks addressing raw material sourcing, logistics constraints, and regulatory compliance checkpoints.
- Go‑to‑market blueprints for service expansion, including pricing models for subscriptions, uptime SLAs, and application lab commercialization.
- Executive dashboards for board reporting, with pre‑built visualizations for revenue run‑ways, margin scenarios, and capital planning.
Each tool is built to be directly plug‑and‑play within corporate financial models or to be adapted by private equity due diligence teams. While this preview highlights our core recommendations and strategic direction, the granular segmentation analytics, supplier share tables, and downloadable Excel models are gated in the full report to preserve subscriber value.
Competitive Appendix — Vendor Schemes to Watch
Our competitive synthesis profiles leading vendors across several strategic postures:
- Vendors focused on optical and thin‑film process integration are leveraging ion beam sputtering and deposition solutions to penetrate photonics and laser supply chains.
- Firms with integrated FIB‑SEM and plasma FIB roadmaps are capturing high‑value applications in failure analysis and volume imaging, enabling higher ASPs and service contracts.
- Specialized implanter and service providers are expanding their footprint by bundling processing services with equipment sales, creating hybrid commercial models that lower adoption friction for capital‑constrained customers.
Recent product launches and order flows underscore that incumbents are doubling down on modular platforms, higher throughput configurations, and service ecosystems — strategies that raise the bar for new entrants but create defined partnership pathways for niche innovators.
How to Use This Preview in Your 2026 Planning Cycle
For executive teams building 2026 strategic plans, this preview frames three immediate actions:
- Embed ion beam technological scenarios in capital planning: include upside/cushion scenarios tied to photonics and research capital cycles, not just mainstream fab investments.
- Update procurement and supplier strategies to reflect material source risk: run stress tests on gallium and alternative ion lines and prioritize multi‑source qualification.
- Allocate R&D and commercial resources to software and service offerings that convert cyclical hardware revenue into recurring annuities.
PW Consulting’s full report supplies the numbers, supplier maps, and decision tools required to operationalize each recommendation and quantify trade‑offs under a range of demand conditions.
Next Steps — Accessing the Full Report
This strategic preview is intentionally selective: it communicates the high‑level market trajectory and the decision levers that matter to leaders in 2026, while preserving the granular segment and vendor intelligence that forms the core of our premium analysis. For procurement teams, corporate strategists, and investors seeking the full dataset — including per‑segment forecasts, regional dynamics, and downloadable financial models — please visit the PW Consulting report page to license the complete Ion Beam Machining Market report and associated toolkits.
PW Consulting stands ready to support bespoke workshops, scenario stress tests, and M&A due diligence engagements that translate the report’s insights into executable 2026 strategies. Contact our industry team to schedule a briefing and receive a tailored package that aligns with your short‑ and medium‑term objectives.
For detailed analysis of this topic, please visit the official page: Ion Beam Machining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com