

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: Machinery & Automotive
PW Consulting: Copper Sulfate Pentahydrate Market to Hit USD 576.8M by 2032 (5.4% CAGR)
By pmarketresearch, 2026-07-30
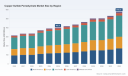
Copper Sulfate Pentahydrate Market: Strategic Intelligence for 2026 Decision-Making
Executive trailer
As companies realign supply chains and product portfolios for the post‑pandemic and decarbonization eras, Copper Sulfate Pentahydrate emerges as a quietly critical intermediate across agriculture, feed, electroplating and specialty industrial applications. This PW Consulting briefing introduces our full Copper Sulfate Pentahydrate Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) and explains why the insights it contains are indispensable for boardrooms and procurement teams planning for 2026.
Copper Sulfate Pentahydrate Market
Key macro position: the global market, measured in USD Million, expanded from approximately 315.2 in 2020 to 402.5 in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.4% through 2032 — reaching an estimated 576.8 by 2032. These topline dynamics reflect the combined effects of agricultural demand resilience, selective industrial recovery, and periodic supply shocks that amplify volatility in certain grades.
Copper Sulfate Pentahydrate Market
Why this report matters for 2026 strategy
-
Operational resilience: the market’s steady mid‑single‑digit CAGR masks episodic supply and quality disruptions that can rapidly cascade into production stoppages or costly recalls. Companies that treat copper sulfate as a strategic raw material — not a commoditized, low‑touch buy — will avoid expensive remediation.
Copper Sulfate Pentahydrate Market -
Regulatory and reputational risk: recent regulatory activity (notably a voluntary recall in April 2026 of contaminated feed‑grade lots originating from China) underscores the need for traceability, batch testing, and contract clauses that allocate recall costs. The recall and confirming reports of dioxin contamination have already prompted faster adoption of upstream verification protocols among North American and European buyers.
-
Commercial differentiation: as customers demand higher‑assurance materials (GMP/USP/FCC/technical certificates, documented supply chains, and product stewardship), producers with certified quality systems and transparent traceability can capture premium pricing and longer contracts.
-
M&A and vertical plays: the market’s structure and pockets of regional specialization create tactical opportunities for acquisitive buyers to secure high‑purity feeds, backward integrate into feed‑grade production, or establish regional hubs that reduce lead times and import risk.
What the full report delivers (practical, transaction‑ready content)
-
Robust market sizing and forecast model (USD Million; 2020–2032) with build‑up logic and sensitivity toggles to test price, feedstock availability and regulatory stress scenarios.
-
Demand driver diagnostics by grade and application, with elasticities and scenario impacts (presented qualitatively in this preview; granular subsegment volumes and shares are reserved for the full report to maintain competitive value).
-
Supply map and capacity registry covering global producers, conversion facilities, and logistical chokepoints; includes lead‑time benchmarks and alternative routing playbooks for emergency sourcing.
-
Supplier due‑diligence toolkit: audit checklists, required certificate templates, in‑market testing regimes and contract language to mitigate contamination risk and supplier non‑performance.
-
Price build and trade dynamics: raw‑material drivers, pass‑through analysis, and a proprietary pricing deck for use in negotiation and budgeting.
-
Regulatory tracker and recall playbook: mapping of current controls across major markets, recall impact scenarios, insurance considerations and crisis communication templates.
-
Competitive landscape intelligence: profiles and strategic positioning of key players, capability matrices, and a short list of potential targets and partners for buyers and investors.
-
Actionable growth roadmaps: go‑to‑market plays, cost‑to‑serve optimization, and a prioritized list of tactical initiatives with expected ROI and implementation timelines for 6–24 months.
High‑level competitive landscape and strategic implications
The Copper Sulfate Pentahydrate market sits in a middle ground of specialization: several established producers serve distinct channels (pharma/nutraceutical, agricultural, feed, electroplating, and industrial uses), while many smaller suppliers address local commodity demand. The market is best characterized as moderately fragmented: the largest regional players collectively do not exert dominant, global pricing control, leaving room for consolidation and margin capture through quality differentiation and logistics efficiency.
-
Shreeji Industries (India) — GMP‑certified manufacturer supplying IP/BP/USP/FCC grades. Strengths: pharmaceutical‑grade credentials, multi‑grade capability and a clear focus on higher‑value channels (nutraceuticals, fungicides, electroplating). Strategic implication: potential partner or acquisition target for firms seeking a certified, Asia‑based, quality‑assured source and faster entry into regulated markets.
-
Sulfozyme Agro India Pvt Ltd (India) — supplier oriented to agricultural and technical grades for plant nutrition, fungicide formulations and feed additives. Strengths: proximity to large agricultural demand pools, specialized technical grade production. Strategic implication: attractive for agricultural chemical formulators that require integrated supply and formulation co‑development; also a candidate for off‑taker agreements or joint quality uplift programs.
-
Univerical (United States) — North American manufacturer of high‑purity liquid and crystalline products for electroplating and industrial uses. Strengths: regional manufacturing, focus on high‑purity and plating‑on‑plastics niches, shorter lead times for North American customers. Strategic implication: natural partner for Western buyers seeking to reduce import dependency and to secure more consistent quality for industrial applications.
Each player illustrates a strategic axis buyers should evaluate: quality certification (GMP/USP/FCC), geographic risk (local production vs. import dependence), and channel focus (agriculture/feed vs. electroplating/industrial). The full report contains head‑to‑head capability matrices and supplier scorecards that buyers can use immediately in sourcing decisions.
Supply‑chain vulnerability spotlight — the 2026 contamination episode
April 2026 saw a voluntary recall of contaminated feed‑grade Copper (II) Sulfate Pentahydrate lots originating from China, reported by the Animal Nutrition Association of Canada and flagged by national food safety authorities. The contamination—associated with dioxin residues—has tangible operational implications:
-
Immediate testing and batch hold policies are now business‑critical for feed and agricultural formulators selling into regulated markets.
-
Buyers must reassess audit frequency, third‑party lab validation, and contractual warranties to allocate recall and remediation costs.
-
Regionalization of supply (or strategic inventory buffers) may be justified despite added holding costs for customers with zero‑tolerance product profiles.
The PW report contains a forensic appendix on the recall, a recommended lab‑testing protocol, and a supplier‑risk matrix that quantifies expected disruption costs under multiple contamination scenarios.
Strategic recommendations for leadership teams planning in 2026
-
Procurement: shift from single‑source spot buys toward blended buying strategies: certified regional suppliers for critical applications and vetted global suppliers for cost flexibility. Implement mandatory incoming batch testing for feed and pharma grades.
-
Quality & Regulatory: prioritize suppliers with third‑party certifications and documented chain‑of‑custody. Insert contractual clauses for recall liability, and secure contingent supply agreements with tested alternates.
-
Operations: evaluate regional buffer stocks and near‑shoring for high‑assurance grades. Rebalance safety stock vs. working capital to reflect the realized risk premium post‑recall.
-
Commercial & R&D: explore premiumization for traceable, certified grades and invest in formulation changes that reduce copper sulfate dependence where possible (or increase recrystallization/upgrade steps to capture margin).
-
M&A & Partnerships: screen targets that provide quality uplift, regional manufacturing, or access to regulated markets. Consider minority investments in certified producers to secure preferential supply.
-
Risk & Finance: stress‑test budgets with the PW forecast scenarios (base, supply shock, regulatory tightening) and ensure insurance coverage aligns with identified recall exposure.
How to use this briefing and next steps
This article is a focused executive preview designed to communicate the strategic value embedded in our full market study. For procurement teams, the buyer’s toolkit and supplier scorecards are immediately actionable. For corporate strategy and M&A teams, the sector mapping and candidate shortlists accelerate diligence. For R&D and product teams, the formulation impact assessments spotlight opportunities to reduce raw material intensity or develop premium, differentiated product lines.
The complete PW Copper Sulfate Pentahydrate Market report contains the granular sub‑segment volumes, regional and application splits, price decks, full company profiles and the quantitative scenario models that underpin the recommendations summarized above. Those detailed elements are intentionally held in the full report to preserve competitive advantage — and they are precisely what your commercial and sourcing teams will need to operationalize 2026 plans.
Call to action
To obtain the full dataset, supplier scorecards, risk matrices and the downloadable forecast model (2026–2032), visit our report page or contact PW Consulting’s industry team. If you are preparing 2026 budgets, negotiating multi‑year offtake agreements, or evaluating acquisition targets, securing the complete intelligence now will materially shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Copper Sulfate Pentahydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Treatment Equipment Market to Expand at 6.2% CAGR (2026-2032)
By pmarketresearch, 2026-07-30
Water Treatment Equipment Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a forward-looking synthesis of the Water Treatment Equipment market designed to influence executive decisions in 2026. Built on a base-year assessment for 2025 and a robust time series across 2020–2025, our view projects the sector through 2032 at a compound annual growth rate (CAGR) of 6.2%. The market has expanded markedly over the past half-decade and is expected to approach the high‑double‑digit billions (USD, revenue unit: Billion) by the end of the forecast window. This briefing highlights the structural drivers, competitive dynamics, risk vectors, and practical actions that matter for procurement, investment, and M&A in 2026 — while intentionally withholding the granular segment and regional line‑items that are reserved for the full report.
Water Treatment Equipment Market
Why 2026 Is a Strategic Inflection Point
-
Policy and capital alignment: Public financing frameworks and renewed regulatory emphasis on conservation are converging with heightened public spending on clean water infrastructure. This alignment reduces funding uncertainty and accelerates opportunities for equipment upgrades, retrofits, and new-build projects across municipal and industrial end-markets.
Water Treatment Equipment Market -
Energy and cost pressure: Water and wastewater treatment remain energy‑intensive activities. The combination of utility cost pressure and corporate sustainability targets is forcing operators to prioritize energy-efficient process equipment, smarter controls, and performance-based O&M arrangements.
Water Treatment Equipment Market -
Technology stacking: Innovations in membranes, disinfection, AI-driven pump management, and modular zero-liquid-discharge (ZLD) systems are shifting buyer economics — moving capital allocation from one-off CAPEX purchases toward integrated solutions that deliver lifecycle OPEX savings.
-
Fragmented supplier base: The market rewards scale in technology development and after‑sales reach but also offers openings for specialist vendors with demonstrable lifecycle economics. Expect both horizontal consolidation and vertical partnerships in 2026–2028.
Market Trajectory (Headline View)
From 2020 through the 2025 base year, the market experienced sustained expansion driven by regulatory compliance projects, industrial water reuse initiatives, and municipal replacement cycles. With a 6.2% CAGR through 2032, the trajectory is clear: demand will keep rising, but the nature of demand is changing — more retrofit projects, greater appetite for modular systems, and an increasing share of purchases tied to services and digital performance guarantees rather than equipment alone.
Practical, Actionable Contents of the Full Report
-
Market sizing and scenario modelling: Transparent methodology with base/bull/bear scenarios, sensitivity testing around energy prices, regulatory tightening, and capital availability.
-
Technology and procurement playbooks: Comparative TCO models for membranes, filtration, UV/chemical disinfection, pumps, and ZLD; recommended procurement structures including availability-based contracting and pay-for-performance clauses.
-
Supplier benchmarking: Qualitative and quantitative scorecards covering technology readiness, service footprint, digital platform maturity, balance-sheet strength, and OEM‑to‑distributor channel economics.
-
Go‑to‑market strategies: Segmented commercial approaches for municipal utilities, heavy industry (chemical, power, mining), food & beverage, and residential/commercial retrofit channels.
-
Regulatory & funding map: Crosswalk of major funding mechanisms, permitting trends, and compliance timelines that materially affect project pipelines and procurement windows.
-
M&A and partnership playbook: Target archetypes, valuation drivers, integration risks, and a checklist for diligence focused on service contracts and digital telemetry assets.
-
Risk register and mitigation: Supply‑chain stress scenarios (critical materials, logistics), cybersecurity controls for digital assets, and contingency plans for rapid policy shifts.
Competitive Landscape — Where Advantage Will Be Won
The competitive map is characterized by three broad supplier archetypes: global systems integrators with full‑service water portfolios; component and chemical specialists; and agile niche innovators focused on a single technology or service model. Leading companies span these archetypes and display differentiated propositions:
-
Systems & services integrators (e.g., Veolia, SUEZ, Evoqua): Strengths lie in end‑to‑end project execution, O&M contracts, and cross-border project financing. Their advantage is in converting large infrastructure programs into multi‑year revenue streams.
-
Technology & chemical leaders (e.g., The Dow Chemical Company, Ecolab, Calgon Carbon): Competitive moats emerge from proprietary chemistries, advanced media, and dosing/control platforms that deliver measurable reductions in chemical and energy consumption.
-
Equipment and digital innovators (e.g., Xylem, Grundfos, Pentair): These suppliers combine hardware excellence with digital monitoring and optimization platforms that lower lifetime costs and create upsell paths into services.
-
Regional OEMs and full-service distributors (e.g., Aquatech, Kurita, Newater, VESSCO, ALAR, Water Treatment Supply): They win where customization, speed-to-delivery, and local compliance knowledge are decisive — particularly in industrial applications.
Across these groups, market winners in 2026 will be those that can shift buyer focus from cheapest initial CAPEX to guaranteed lifecycle performance. Partnerships between chemical houses, membrane manufacturers, and digital platform providers will accelerate; likewise, modular ZLD and decentralized purification variants create entry points for agile specialists.
Recent Developments to Watch (Strategic Implications)
-
Next‑gen UV and disinfection systems with smarter control stacks reduce energy and chemical needs — making retrofits attractive for mid‑life municipal plants that face operating‑cost scrutiny.
-
Intelligent pump systems incorporating AI can unlock 10–20% energy savings at scale, changing the business case for replacing legacy pumping inventories in treatment trains.
-
Modular ZLD solutions lower entry barriers for industrial operators targeting zero discharge, creating prospective demand that favors suppliers offering scalable, factory‑assembled modules.
-
Advanced whole‑house and point‑of‑use membrane technologies expand the residential and commercial retrofit market, but they also commoditize some traditional mid‑market channels.
Strategic Recommendations for 2026 Decision-Makers
-
Reframe procurement KPIs: Shift from equipment price to three‑year and five‑year TCO and guaranteed outcomes. Insist on telemetry and performance SLAs tied to payments.
-
Prioritize modularity and retrofitability: Capex‑constrained operators should prioritize equipment that reduces downtime during installation and can be scaled incrementally.
-
Invest in partnerships, not only acquisitions: Fast followers can secure access to advanced membranes, ZLD modules, or digital control platforms through JV and licensing models rather than full M&A.
-
Design for energy: All procurement decisions must be evaluated against energy intensity targets. Digital pump optimization and advanced disinfection platforms will produce the quickest measurable wins.
-
Lock service economics: For vendors, compress the sales cycle by offering bundled O&M and remote monitoring. For buyers, convert uncertain OPEX into predictable service contracts.
-
Prepare for regulatory acceleration: Build a regulatory scenario playbook — faster compliance timelines materially change capex scheduling and funding applications.
Risk & Opportunity Matrix
Key risks include supply‑chain disruption for critical membranes and electronic components, sudden regulatory shifts in regional jurisdictions, and cyber risks tied to increased digitization. Conversely, opportunities exist in retrofits financed by public funds, decarbonization-linked incentives, and cross‑sector reuse projects (e.g., industrial symbiosis and potable reuse). The full report contains quantified scenario impacts on project pipelines and vendor revenues, enabling prioritized action plans for each risk bucket.
What the Full PW Consulting Report Unlocks
This preview is deliberately high‑level to underline strategic direction and to guide 2026 decision priorities. The complete Water Treatment Equipment Market study provides the missing granular intelligence that executives, investors, and procurement teams need to act decisively: detailed segment and regional breakdowns, vendor scorecards with commercial playbooks, project-level case studies, bid templates, margin benchmarks, and an M&A target shortlist refined by fit‑for‑scale criteria. For teams that must translate strategy into contracts, the delivered toolkits include RFP language, SLA templates tied to performance telemetry, and rollout sequences optimized for capital availability.
PW Consulting’s approach blends market economics, engineering realism, and commercial pragmatism. In an industry where capital choices made in 2026 determine operational cost curves for decades, our guidance helps you prioritize the initiatives that protect EBITDA, reduce regulatory exposure, and deliver sustainable water outcomes.
Next Steps
-
Request the full report to access the data tables, segment-level forecasts, and vendor financial overlays that underpin the strategic recommendations summarized here.
-
Engage our advisory team for a short diagnostic workshop: we’ll map your asset base to the report’s opportunity heatmaps and produce a 90‑day decision agenda.
For detailed analysis of this topic, please visit the official page: Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DTH Drill Market USD 1,355M in 2025, set for 4.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-30
DTH Drill Market — 2026 Strategic Preview
As organizations calibrate capital deployment and operational priorities for 2026, the Deep Trench Hammer (DTH) drill market is transitioning from incremental improvement to selective reinvention. PW Consulting’s latest DTH Drill Market study (base year 2025, forecast 2026–2032) synthesizes longitudinal market sizing, competitive positioning, and applied technology levers into a single usable framework for commercial leaders, procurement chiefs, and engineering heads. This preview highlights the study’s strategic value while intentionally withholding granular subsegment tables and regional/application splits — the exact data and scenario matrices are available in the full report.
DTH Drill Market
Macro Snapshot: Growth Trajectory and What It Means
The DTH drill market has shown steady expansion over the past half-decade. Our modeling indicates growth from approximately USD 1,100 Million in 2020 to USD 1,355 Million in 2025, and a continued rise through the forecast window to roughly USD 1,853 Million by 2032. That trajectory implies a mid-single-digit compound annual growth rate (CAGR) of 4.5% across the forecast period (2026–2032).
DTH Drill Market
For executives, that CAGR and trajectory carry three immediate implications: (1) demand is stable enough to justify targeted investment in product development and aftermarket services; (2) competition will increasingly center on lifecycle economics — fuel/energy efficiency, serviceability, and digital productivity — rather than raw unit volume; and (3) incremental technology adoption (electrification, real-time sensing, optimized consumables) will deliver disproportionate value for operators with large drilling portfolios.
DTH Drill Market
Dynamics Driving Strategic Choices in 2026
-
Productivity-as-Primary KPI: Field benchmarks and vendor claims point to productivity gains that materially change cost-per-meter economics. Optimized hammers and bit designs can enable high hourly footage (industry reports indicate best-practice DTH setups achieving up to 50 meters per hour), while advanced consumables reduce change intervals and air/fuel usage. Executives should reframe procurement conversations around enabled meters per operating hour rather than unit price alone.
-
Energy and Emissions Pressure: Regulatory and corporate sustainability targets are elevating the strategic importance of energy efficiency. Vendors are positioning products with lower air/fuel consumption and improved energy conversion — a trend that translates into both Opex savings and a compliance hedge as emissions accounting becomes more rigorous.
-
Digital & Automation Uptake: Real-time sensing and analytics (for example, systems that deliver vibration and performance telemetry) are shifting DTH from a purely mechanical category into a data-driven service offering. Early adopters extract productivity gains, predictive maintenance benefits, and improved safety outcomes; laggards face increasing aftermarket cost pressures.
-
Supply-Chain and Materials Intensity: Cemented carbide and specialized head geometries remain central to tool performance. Raw-material sourcing and refining bottlenecks can create delivery and margin volatility — an operational risk that should be actively hedged via supplier diversification and recycling/remanufacturing strategies.
-
Consolidation vs. Specialization: The market shows a meaningful concentration among the top players, with a three-firm concentration ratio and a five-firm concentration ratio indicating that leading manufacturers hold a sizable portion of market revenue. That dynamic favors scale players for global contracts and aftermarket coverage but opens niche opportunities for specialized or regional suppliers that can undercut on responsiveness and customization.
What the PW Consulting Report Delivers — Practical, Actionable, Executable
- Proprietary market-sizing model (2020–2032) with scenario sensitivity to energy costs, regulatory tightening, and automation adoption rates.
- Commercial playbooks for OEMs, distributors, and large end-users including pricing architectures, spare-parts inventory strategies, and warranty structures that optimize lifecycle margins.
- CapEx/Opex comparison tools to evaluate internal combustion vs. electric-drive DTH systems under varied fuel and electricity cost regimes.
- Field-level productivity benchmarks and a standardized set of KPIs — meters per hour, bits-per-meter, downtime drivers — enabling apples-to-apples vendor evaluation.
- Supplier due-diligence templates addressing manufacturing footprint, raw-material security, quality assurance, and aftermarket capability.
- Buy-side negotiation playbook and RFP language focusing on guaranteed meters, energy consumption per meter, and digital service level agreements (SLAs).
- Scenario-driven M&A and partnership thesis mapping for strategic entrants seeking bolt-on technologies (e.g., telemetry, remanufacturing) or geographic expansion.
Note: the public preview purposefully omits the full set of regional, type- and application-level tables and the underlying revenue splits. Those critical tables and the interactive model are provided in the full report to registered subscribers.
Competitive Landscape — Who Matters and Why
The DTH landscape blends global OEM scale, regional manufacturing strengths, and focused niche specialists. The market’s top-tier firms — headquartered largely across Sweden, Ireland, Finland, the U.S., China, and Australia — combine deep product portfolios with aftermarket networks and expanding digital capabilities. Below is a strategic snapshot of several influential participants:
-
Sandvik (Stockholm, Sweden): A long-standing engineering leader with a strong portfolio in DTH bits and drilling tools. Recent product introductions include resharpening equipment aimed at extending consumable life and reducing lifecycle cost. Sandvik’s strength is integrated product-service offers and a brand trusted for field reliability.
-
Atlas Copco (Stockholm, Sweden): Known for low-energy hydraulic DTH systems and a broad distribution base, Atlas Copco is leveraging energy-efficiency positioning to win specifications in construction and quarry segments where operating costs are a competitive lever.
-
Epiroc (Stockholm, Sweden): Aggressively pursuing the digital frontier with a DTH Optimizer solution and a new DTH hammer family that emphasizes sensing and real-time optimization. Epiroc’s product+software play is designed to lock in long-term service contracts and generate data-derived aftermarket revenue.
-
Mincon (Naas, Ireland): Focused on consumables and hammer designs optimized for fuel efficiency and penetration rates. Recent catalog refreshes underscore incremental performance improvements that appeal to water-well and geothermal segments.
-
Boart Longyear (Perth, Australia): A traditional exploration and production tools supplier with strong ties to resource-sector customers; their value is deep domain expertise in exploration workflows and global logistical reach.
-
Regional and Niche Players: Rockmore International (Austria), Robit Plc (Finland), Center Rock (USA), and several China-based producers (Drill King, Sinodrills, BD Drill Group) deliver valuable local cost advantages, rapid lead times, and product variations tuned to specific rock types and applications. U.S.-based Infinity Tool MFG supplies industry-standard bit geometries with flexible small-batch capability.
Recent vendor activity in 2025–2025 highlights the twin themes of product evolution and digital enablement: Epiroc’s multi-configuration hammer plus sensing platform; Sandvik’s mid-range resharpening machine; Mincon and Rockmore updating catalogs with performance and efficiency upgrades; and Sinodrills emphasizing low-consumption hammers from their production line. These moves are competitive signals — incumbents are protecting installed bases while newer entrants target efficiency-sensitive subsegments.
Strategic Imperatives for 2026
-
Prioritize Total Cost of Operation (TCO): Replace legacy procurement metrics with TCO models that weigh fuel/energy, consumable lifespan, and downtime. Demand guaranteed performance metrics in contracts (e.g., meters-per-hour performance commitments) and link payments to realized productivity.
-
Invest in Digital Integration: Require telemetry-ready hardware and secure data access clauses in procurement to enable predictive maintenance and performance-based contracting.
-
Hedge Raw-Material Risk: Lock supplier agreements for critical alloys and carbide supply, explore remanufacturing partners, and evaluate in-house reconditioning as a margin lever.
-
Reconfigure Aftermarket Strategy: For OEMs: bundle digital subscriptions with consumables and service; for end-users: regionalize spare kits and centralized analytics to cut downtime.
-
Pursue Focused M&A: Target small to mid-sized technology players (telemetry, bit metallurgy) or regional distributors that can accelerate route-to-market in high-growth corridors.
Execution Checklist — 90-Day Plan for Leadership Teams
- Run a TCO pilot comparing incumbent tools and two alternative vendor solutions across representative rigs.
- Negotiate sample supply contracts that include energy-per-meter and bit-life guarantees.
- Map spare-parts nodes and implement a critical-parts reorder point tied to meters drilled rather than time elapsed.
- Initiate a proof-of-concept with a telemetry vendor to capture drill-vibration and penetration data for a minimum of 30 days.
- Perform a sourcing risk assessment for carbide and specialty alloys and prioritize suppliers for long-term agreements.
Conclusion: The DTH drill market in 2026 is sufficiently mature to reward targeted investments but not so consolidated as to preclude disruptive entry. Scale matters — particularly in aftermarket coverage and digital enablement — but significant opportunities remain for operators that can convert technical gains (lower air/fuel per meter, reduced bit-change frequency) into verifiable commercial outcomes.
Get the Full Intelligence
This preview demonstrates the strategic contours and immediate decision levers. The full PW Consulting DTH Drill Market report contains the withheld regional, type, and application breakdowns, the interactive forecasting model, vendor scorecards, and downloadable RFP templates required to operationalize these recommendations. Access the complete study on our report page to obtain the detailed tables, scenario models, and the actionable annexes that empower confident 2026 capital and procurement decisions.
For detailed analysis of this topic, please visit the official page: DTH Drill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Saccharin Market Poised for USD 456M by 2032 at 7.84% CAGR
By pmarketresearch, 2026-07-30
Saccharin Market — Strategic Outlook for 2026 (PW Consulting)
As companies set priorities for 2026, understanding the commercial dynamics of high-intensity sweeteners has become a board‑level imperative. PW Consulting’s latest Saccharin Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes primary supplier intelligence, regulatory developments and scenario-driven demand modeling into an operationally focused playbook. The market stood at approximately USD 272 Million in 2025 and is projected to grow to roughly USD 456 Million by 2032, reflecting a compound annual growth rate of 7.84% across the forecast window. This introduction outlines why that trajectory matters, what strategic choices it forces on industry participants in 2026, and where the report adds immediate, actionable value — while intentionally withholding detailed segment-level figures to protect the report’s proprietary granularity and guide readers to the source for full access.
Saccharin Market
Why this report matters for 2026 decision-making
-
Timing: The sector is transitioning from steady replacement demand toward differentiated growth driven by product reformulation in food & beverage, expanded pharmaceutical use-cases and niche personal-care formulations. The growth profile through 2032 validates near-term capacity planning decisions.
Saccharin Market -
Margin pressure and cost arbitrage: Structural cost advantages in certain geographies are compressing global margins for commodity saccharin, while premiumisation (high‑purity grades, certified food‑grade and pharma‑grade streams) opens routes to margin recovery.
Saccharin Market -
Regulatory stability — with conditional caveats: Longstanding regulatory frameworks remain in force, but evolving compliance requirements (REACH, food additive authorizations and local import HS code enforcement) are shifting compliance cost lines for cross‑border supply chains.
-
Fragmented supply base: The market is not concentrated in a handful of dominant global incumbents; instead, a broad supplier ecosystem (from large-scale producers to specialty high‑purity houses) creates win paths for both scale and niche strategies.
What our full report delivers (practical, deal‑ready content)
-
Verified market sizing and growth scenarios: granular total addressable market modelling by demand tier with transparent assumptions (historical validation, consumption drivers and price elasticity ranges).
-
Demand-supply mapping: supplier capacity overlays, utilization scenarios and export flow analysis to identify potential bottlenecks and strategic sourcing locations.
-
Cost-to-serve and margin decomposition: unit cost modeling (raw materials, energy, logistics, compliance) and sensitivity runs to detect margin inflection points under alternative feedstock and freight scenarios.
-
Regulatory risk matrix and compliance playbook: impact assessments for major jurisdictions and a checklist for REACH, FDA and EFSA compliance pathways together with typical timelines and cost ranges for certification.
-
Commercial playbooks for buyers and sellers: contracting templates, quality acceptance protocols, dual-sourcing strategies and sample testing regimens designed for 2026 procurement cycles.
-
M&A and partnership pipeline: candidate screening criteria, valuation anchors for specialty vs commodity assets and integration risk checklists for private equity and strategic buyers.
-
Scenario planning suite: three vetted scenarios (baseline, accelerated adoption, regulatory tightening) with P&L and working capital impacts for immediate deployment in 2026 planning cycles.
Competitive landscape: profiles and strategic implications
The saccharin supply chain comprises multiple archetypes — large-volume commodity producers with backward integration, regional specialists focused on cost-efficient exports, and small, high‑purity producers serving regulated end‑markets. Our competitive analysis profiles each archetype and highlights near‑term strategic moves to watch in 2026.
-
Large-scale commodity producers (China and select EM manufacturers): These players leverage scale, integrated raw-material sourcing and cost advantages to serve global food and industrial channels. Their ISO and food‑safety certifications enable broad export footprints; market entrants and buyers should expect competitive pricing discipline and fast order fulfillment where logistics are optimized.
-
Back‑integrated Indian manufacturers: Some manufacturers combine in‑country raw material sourcing with sizable annual production capability. This reduces exposure to overseas feedstock shocks and supports competitive export pricing, particularly into regional pharma and feed markets.
-
High‑purity and specialty producers (Korea, select EU/US suppliers): These vendors focus on the upper end of the value chain — pharmaceutical and specialized food applications — and command pricing premia tied to traceability, certifications and production controls. For buyers requiring documented safety histories and formulation stability, these suppliers mitigate regulatory and reputational risk.
-
Laboratory and niche distributors: US-based and regional distributors provide just-in-time small-batch supplies and regulatory documentation for R&D and niche applications; their strategic value lies in enabling rapid product development without the overhead of direct supplier qualification.
Recent market developments reinforce these dynamics: in 2025, we tracked launches of new sodium saccharin formulations targeted at food and beverage reformulation and recognition awards for long-established high‑purity producers — signals of both product innovation and brand positioning that matter for premium channels.
Regulation, trade and supply‑chain realities shaping 2026
-
Regulatory foundations: The additive remains subject to long-established food‑additive frameworks in major markets; regulators continue periodic reassessment rather than wholesale bans, which supports continued commercial use but increases the importance of documented safety dossiers and supply‑chain traceability.
-
EU REACH and trade codes: Compliance requirements tied to import classifications and REACH obligations are materially affecting sourcing decisions for companies that sell into European markets — non‑compliance risks can translate into shipment delays and costly remediation.
-
Feedstock and regional cost bases: Readily available raw materials in certain countries underpin persistent cost advantages and have driven capacity expansion. Buyers should model supplier landed costs inclusive of tariffs, compliance spend and freight volatility to understand true unit economics.
Strategic choices for 2026 — recommended actions by stakeholder
-
Manufacturers: Prioritize a two‑track strategy — defend commodity volumes through scale and cost management while investing in a premium stream (pharma‑grade, certified food ingredients). Consider selective capex to improve flexibility (reactors, filtration, certification processes) and pursue backward integration where feedstock volatility is material.
-
Buyers (F&B, pharma, personal care): Implement dual‑sourcing and supplier maturity models; add contractual clauses for traceability and regulatory audit rights. For reformulation initiatives, partner early with high‑purity suppliers to de‑risk shelf‑life and organoleptic outcomes.
-
Investors: Seek platform targets that combine production scale with documented quality pathways. Value accretion is likely where buyers can consolidate fragmented regional capacity, upgrade quality systems and cross‑sell into pharma and specialty markets.
-
Policy and compliance teams: Build REACH readiness and import‑classification checks into 2026 procurement cycles; factor these into landed cost models and supplier selection criteria.
Risk and reward — an executive summary view
Upside drivers include continued reformulation in food and beverages, incremental clinical and OTC pharmaceutical demand and the ability for premium producers to capture value through certification and technical service. Downside risks are concentrated in regulatory shocks, feedstock/energy price volatility and logistics disruptions that could materially affect near‑term margins for commodity suppliers. The interplay between low-cost scale and premium differentiation will determine winners in 2026: companies with flexible supply chains and documented compliance programs will outcompete peers on both price and access to regulated markets.
Immediate takeaways for 2026 planning
-
Recalibrate procurement to reflect true landed costs, not only ex‑works prices; include compliance and logistics as line items in 2026 budgets.
-
For manufacturers, allocate capital to either expand flexible capacity or to up‑grade quality systems — both are defensible in the current growth scenario, but not simultaneously without clear returns.
-
Investors should prioritise targets offering a credible transition path from commodity to specialty segments, or assets that meaningfully consolidate regional supply chains.
-
All stakeholders should lock in vendor audits and certification timelines early; regulatory lead times are non-trivial and can bottleneck commercial plans.
Next steps — how to extract the full strategic value
The summary above highlights the commercial levers and regulatory contours that will shape decisions in 2026. PW Consulting’s full Saccharin Market report contains the granular segmentation, price curves, supplier scorecards, capacity maps and downloadable scenario models required to convert this strategic direction into executable plans (procurement RFP language, M&A diligence packs, capex justification templates). If you are leading procurement, manufacturing strategy or M&A evaluation in this sector, the full dataset and modelling workbench will save weeks of analysis and materially reduce execution risk.
Contact PW Consulting to arrange a briefing, obtain access to the complete report and explore tailored workshops that translate these findings into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Saccharin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diagnostic X-Ray Imaging Market to Reach USD 24,029 Million by 2032 (5.6% CAGR)
By pmarketresearch, 2026-07-30
Diagnostic X-Ray Imaging Market: Strategic Imperatives for 2026
As healthcare systems worldwide recalibrate capital allocation, diagnostic throughput, and technology roadmaps following pandemic-era disruptions, the Diagnostic X-Ray Imaging market re-emerges as a high-frequency, durable segment of medical capital expenditure. PW Consulting’s Diagnostic X-Ray Imaging Market Diagnostic X-Ray Imaging Market research frames the decisions 2026 leaders must make — balancing incremental digital upgrades, regulatory compliance, and supply-chain resilience against accelerating clinical demand. This introduction outlines the study’s strategic value for executives preparing budgets, partnerships, and product roadmaps in 2026, while preserving the granular proprietary intelligence available in the full report.
Diagnostic X-Ray Imaging Market
Executive snapshot — market trajectory and structural context
Using 2025 as the analytical base year, our model estimates the global diagnostic X‑ray market at approximately 16.5 billion USD (revenue unit: Million USD). Over the 2026–2032 forecast window, we project compound annual growth of 5.6%, reflecting a combination of replacement cycles in developed markets, capacity expansion in middle-income health systems, and steady adoption of digital radiography and AI-enabled workflow tools. By the end of the forecast horizon the market approaches the mid‑20 billion USD range, underscoring both expansion and consolidation dynamics that will shape procurement, partnerships, and product strategies through the decade.
Diagnostic X-Ray Imaging Market
Market concentration is meaningful but not prohibitive: the three largest vendors together account for under half of global sales, and the five-largest cohort controls a clear majority — a structure that creates windows for focused disruptors and component suppliers to capture value via specialization, services, or channel partnerships.
Diagnostic X-Ray Imaging Market
Why this market matters in 2026 — five practical reasons
- High-frequency utilization: X‑ray remains the backbone of diagnostic workflows across emergent, routine, and chronic-care pathways — driving consistent service volumes and predictable revenue streams for equipment and service models.
- Digital migration unlocks value: The ongoing transition from analog and computed radiography to flat‑panel digital radiography continues to generate replacement demand, workflow efficiency gains, and new service offers (AI-assisted triage, automated QC).
- Regulatory and reimbursement inflection points: Tighter safety standards and evolving reimbursement codes are altering procurement decision trees — favoring vendors who can demonstrate compliance and enable billing optimization.
- Component and supply-chain leverage: Independent suppliers of X‑ray tubes and detectors are strategically important — either as partners for OEMs or as acquisition targets for firms seeking vertical integration and margin control.
- Consolidation and services: As hardware becomes more standardized, aftermarket services, financing, training, and integrated software services are potent differentiators that preserve margins and increase switching costs.
Drivers, headwinds, and regulatory dynamics
Our Diagnostics X‑Ray market model layers quantitative forecasts with qualitative assessments of structural drivers that will influence 2026 decisions:
- Clinical demand and epidemiology: Demographic aging and expanded access in emerging markets sustain steady imaging volumes, while episodic surges (e.g., infectious disease waves or trauma spikes) create short-term procurement needs and rental/device-as-a-service opportunities.
- Technology diffusion: Advances in flat‑panel detectors, mobile DR platforms, and AI for image acquisition/triage improve throughput and lower cost-per-exam — creating a premium tier of technology buyers while opening retrofit and upgrade markets.
- Regulatory environment: New and reinforced standards are shaping product design and market entry. Notably, Part F requirements from radiation oversight authorities and FDA assembly/reporting obligations for diagnostic X‑ray equipment impose documentation, labeling, and installation reporting duties that vendors and assemblers must incorporate into commercial contracts and installation workflows.
- Reimbursement mechanics: Established reimbursement frameworks (public and private) continue to govern adoption pace; firms that synchronize coding, evidence generation, and payer engagement unlock faster uptake.
- Supply-chain dynamics: Competition between OEM in‑house manufacturing and independent suppliers for key components (tubes, flat panels) impacts lead times, pricing, and negotiation leverage — an area where supply‑risk mitigation strategies are increasingly central to procurement teams.
Competitive landscape — who matters and why
The competitive terrain combines global platform vendors, regional specialists, and component suppliers. Our report profiles each tier with commercial metrics, technology roadmaps, and recommended engagement strategies.
- GE HealthCare Technologies Inc. (Chicago, IL, USA) — A leading provider of digital radiography systems, known for advanced flat-panel detectors, mobile units, and integrated imaging solutions. GE’s broad installed base and service networks make it a strategic partner for large health systems seeking end-to-end lifecycle management.
- Siemens Healthineers AG (Erlangen, Germany) — Supplier of integrated DR platforms with deep AI and workflow integration capabilities. Siemens’ recent product introductions emphasize enterprise-level automation and clinical throughput, making it competitive for high-volume hospital environments. (Recent: MULTIX Impact E launch, Jan 2025.)
- Koninklijke Philips N.V. (Amsterdam, Netherlands) — Offers digital radiography platforms with advanced automation and AI-assisted collimation that target workflow efficiency. Philips' strength lies in systems integration and clinical workflow orchestration across imaging modalities.
- Canon Medical Systems Corporation (Otawara, Japan) — Focused on high-image quality DR systems and detector technology; known for robust engineering and clinical image performance in diagnostic settings.
- Fujifilm Healthcare Solutions (Tokyo, Japan / Americas operations in US) — Supplier of glass-free detectors and DR platforms optimized for diagnostic imaging with a strong presence in retrofit and upgrade segments.
- Varex Imaging Corporation (Salt Lake City, UT, USA) — Independent supplier of X‑ray tubes and flat-panel detectors; a pivotal supplier that presents channel and M&A implications for OEMs aiming to secure component supply and technology differentiation.
- Carestream Health, Inc. (Rochester, NY, USA) — Provider of mobile X‑ray platforms and HD detectors, increasingly focusing on regulatory approvals and market expansion. (Recent: CE Mark for DRX‑Rise, Jan 2025.)
Recent market moves — product launches and regulatory milestones — reaffirm the pace of innovation. Examples include Siemens’ MULTIX Impact E and GE HealthCare’s Definium Pace Select ET launches during 2025, and United Imaging’s uDR Aurora CX debut. These rollouts reflect vendor strategies to capture both greenfield demand and replacement cycles with higher throughput and AI-enabled capabilities.
What our full report contains — practical, transaction-ready content
PW Consulting’s Diagnostic X‑Ray Imaging Market study is structured for decision-makers who need actionable outputs, not just descriptive analytics. Key deliverables include:
- Top‑down and bottom‑up market sizing with scenario analysis anchored on a 2025 base year and a 2026–2032 forecast horizon at a 5.6% CAGR assumption.
- Segment-level frameworks (by product type, application, and region) with drivers, adoption curves, and sensitivity analyses — presented as decision matrices to inform regional rollout or divestiture choices. (Note: granular segment tables and proprietary split data are accessible in the full report.)
- Competitive benchmark dashboards covering product features, go‑to‑market models, service portfolios, and contract archetypes for the top vendors and leading component suppliers.
- Regulatory and payer playbooks that translate Part F, FDA 21 CFR guidance, and reimbursement coding dynamics into procurement checklists, clinical-evidence requirements, and compliance milestones.
- Supply‑chain risk maps and supplier-sourcing options, including strategic scenarios for vertical integration, long-term supply agreements, and component substitution tradeoffs.
- M&A, partnership, and commercialization playbooks: target criteria, valuation multiples, and integration checklists tailored to buyers focused on technology, service expansion, or geographic access.
- Implementation tools: procurement scorecards, ROI and TCO calculators, and phased deployment roadmaps for converting pilot projects into enterprise-wide deployments.
Strategic implications and recommended actions for 2026
- Prioritize compliance-enabled differentiation: Vendors should embed regulatory evidence and assembler documentation workflows into product offerings to shorten sales cycles with large health systems that require installation reporting and regulatory traceability.
- Monetize services and software: Margins are shifting toward recurring revenue — invest in remote monitoring, predictive maintenance, and AI workflow modules that create annuity-like revenue streams and increase switching costs.
- Hedge supply risk proactively: Health system buyers and OEMs should execute dual-source strategies for critical components and consider contractual frameworks that share lead-time and inventory risk.
- Segment go‑to‑market tactically: Match product tiers to buyer needs — mobile DR and retrofit kits for capacity-constrained sites; high-throughput integrated systems for tertiary centers; scaled service bundles for regional networks.
- Use acquisitions strategically: For entrants and mid-tier players, targeted acquisitions of detector or tube specialists can accelerate time-to-market and margin expansion; for incumbents, bolt-on services providers can defend margins against commoditization.
How to use this research — recommended readership and next steps
This study is built for CEOs, product leaders, corporate development teams, procurement heads, and clinical engineering executives planning budgets, contract negotiations, or M&A activity in 2026. Use the executive summary and scenario roadmaps to align board-level decisions, and deploy the implementation toolkits to operationalize procurement and deployment decisions within 6–18 months.
To preserve strategic advantage, this introduction intentionally highlights drivers, vendor dynamics, and practical frameworks while withholding the detailed segment tables, regional/application split matrices, and proprietary company scorecards that underpin our actionable recommendations. Those core datasets and the full suite of implementation tools are available in the complete PW Consulting report — where quantitative granularity meets commercial playbooks.
Accessing the full intelligence
If your 2026 planning requires transaction-ready models, supplier scorecards, or regulatory playbooks tailored to your organization’s profile, PW Consulting can provide the complete Diagnostic X‑Ray Imaging Market report and bespoke advisory packages. The full deliverable contains the detailed segment-level data, regional and application breakdowns, and vendor benchmarking necessary to translate strategic intent into executable programs.
Contact PW Consulting to schedule a briefing and obtain the comprehensive datasets that inform capital allocation, partnership strategy, and product development priorities for the coming planning cycle.
For detailed analysis of this topic, please visit the official page: Diagnostic X-Ray Imaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydraulic Dock Leveler Market to Reach USD 2,707.08M by 2032 (6.5% CAGR)
By pmarketresearch, 2026-07-30
Hydraulic Dock Leveler Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present an executive introduction to our Hydraulic Dock Leveler Market study — a focused, decision-grade resource designed to shape capital allocation, product strategy, and commercial execution in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the market is modeled with a compound annual growth rate (CAGR) of 6.5%. The market demonstrated steady expansion from approximately 1.36 billion USD in 2020 to 1.75 billion USD in 2025, and our forecast sees that trajectory continuing toward an estimated 2.71 billion USD by 2032. These macro dynamics frame the opportunity set and the risks that executives must manage in the next 18 months and beyond.
Hydraulic Dock Leveler Market
Why this study matters for 2026 decisions
-
Timing capital expenditure: With market growth in the mid-single digits (6.5% CAGR), firms must choose whether to accelerate investment in new manufacturing capacity, prioritize product upgrades, or exploit aftermarket and retrofit channels. Each choice has different payback horizons against the forecast growth path.
Hydraulic Dock Leveler Market -
Product and regulatory compliance: The dock leveler product set is being reshaped by safety and performance standards. Adoption of ANSI MH30.1-2022 / MH30.2-2022 across North American projects is driving specification changes — from structural testing regimes to documentation and warranty expectations.
Hydraulic Dock Leveler Market -
M&A and partnership screening: A moderately concentrated vendor landscape creates opportunities for bolt-on acquisitions, distribution partnerships, and strategic alliances focused on controls, hydraulics, and service networks.
-
Aftermarket economics: As installations age and uptime demands rise, aftermarket services, retrofit kits, and predictive maintenance provide attractive margin pools relative to new-unit sales.
Market dynamics — drivers, constraints & inflection points
-
Demand drivers: E-commerce and omni-channel fulfillment continue to expand demand for optimized loading/unloading infrastructure. Warehouse modernization programs, renovation cycles in distribution networks, and investments in heavy-industrial terminals all underpin steady unit demand and upgrade cycles.
-
Standards and safety: Recent standardization efforts (notably ANSI MH30.1-2022 and MH30.2-2022) are converting best-practice features into procurement requirements. For product teams and tender managers, ANSI certification increasingly predicts specification wins and reduces vendor risk in institutional procurement.
-
Product performance envelope: Hydraulic designs now routinely span broad capacity ranges, with certain industry-grade models engineered for very high load ratings. This range is important for OEMs targeting heavy-industrial end markets where durability, interlock compatibility, and low life‑cycle cost are paramount.
-
Serviceability & control systems: Reduced-maintenance architectures and resilient control stations (e.g., corrosion- and moisture-resistant enclosures) are becoming differentiators — influencing lifecycle operating costs and total cost of ownership calculations.
-
Supply-side constraints: Raw-material volatility and component sourcing (hydraulic cylinders, valves, electrical controls) continue to create scheduling and cost pressures that favor vertically integrated suppliers or those with diversified supply chains.
Competitive landscape — what the leading players signal
The competitive field blends long-established industrial players with focused dock-equipment specialists. Market concentration metrics indicate room for differentiation and consolidation: the top three firms do not monopolize the market, and even the top five leave substantial share for regional champions and niche specialists. Below is a distilled view of strategic postures and capabilities among the core vendors we benchmarked.
-
Overhead Door Corporation — Leans into certified, specification-driven product launches. Recent introductions with ANSI certification and extended warranty positioning indicate a strategy targeting institutional buyers and specification-heavy accounts where compliance and reduced procurement risk matter most.
-
Poweramp (Systems, LLC) — Emphasizes operational simplicity and vertical storing configurations that appeal where workplace ergonomics and bay density are important. Their push-button and high CIR features reflect a customer focus on throughput and operator ease.
-
DLM (Systems, LLC) — Maintains a balanced product portfolio for pit and edge-of-dock needs. Their emphasis is on adaptable platforms that can be configured by OEMs or distributors for heterogeneous fleet requirements.
-
Rite-Hite Corporation — Differentiates on integrated systems thinking (e.g., Smooth Transition Dok System®), positioning dock levelers as part of a broader site-level material handling solution rather than as standalone units.
-
Pentalift Equipment Corporation — Known for high-capacity, low-maintenance designs aimed at heavy-industrial applications. Their engineering emphasis on high-rating units maps to customers prioritizing life-cycle robustness over initial purchase price.
-
Nordock Inc. — Focuses on designs that reduce downtime and maintenance burden, marketing push-button simplicity and reliable edge-of-dock options for high-turnover facilities.
-
McGuire Manufacturing Co. — Highlights structural durability and low lifetime ownership cost, making them a contender in total-cost-of-ownership conversations during procurement.
-
Blue Giant Equipment Company — Competes on durability and environmental resistance, including corrosion-resistant controls and NEMA-rated solutions for demanding ambient conditions.
Implications for product strategy and commercial models
-
Design for specifications: With standards becoming procurement gatekeepers, incorporating certification pathways into new-product timelines reduces time-to-spec and accelerates adoption by institutional buyers.
-
Service-first go-to-market: Build margin-rich service offerings — aftermarket parts kits, preventive maintenance subscriptions, and retrofit packages — to leverage installed base growth and extend revenue visibility.
-
Modularization and configurable platforms: Create scalable product platforms that allow flexible configurations by capacity, control type, and environmental protection to shorten lead times and support localized value propositions.
-
Controls and connectivity: Investing in durable control enclosures and basic telematics (for usage and fault reporting) can unlock premium positioning in operations-sensitive accounts without requiring heavy R&D investment.
Operational and supply-chain considerations
Boards and COOs must weigh near-term market growth against potential bottlenecks in hydraulics components and corrosion-resistant electrical enclosures. Strategies that mitigate risk include multi-sourcing, near-shore assembly for key markets, and inventory hedging for critical subcomponents. OEMs that simplify installation and reduce field-service frequency will gain an advantage as labor costs and technician availability remain constrained across core logistics markets.
What the full report delivers (practical content for 2026 execution)
-
Methodology: Transparent forecasting model with scenario analysis across demand, pricing, and supply disruptions.
-
Market sizing & macro trends: Historical base (2020–2025), 2025 benchmarking, and an industry-grade forecast to 2032 with an explicit 6.5% CAGR baseline.
-
Segmentation framework: Multi-dimensional splits by product architecture, application type, and geography with demand drivers and adoption curves (note: detailed segment tables and downloadable excel workbooks are included in the full report).
-
Vendor benchmarking: Comparative scorecards across engineering capability, product depth, distribution reach, after-sales capacity, and R&D roadmap.
-
Regulatory & standards mapping: Impact analysis of ANSI MH30.1/MH30.2 and implications for procurement language and warranty design.
-
Supply-chain stress tests: Component concentration analysis, lead-time sensitivity, and mitigation playbooks.
-
Commercial playbooks: Pricing tactics, bundling of service and retrofit offerings, and tender-response templates to win specification-driven projects.
-
M&A and partnership screen: Deal targets and integration considerations keyed to growth and margin objectives.
Top-line strategic recommendations for 2026
-
Prioritize ANSI-compliant product lines for institutional channels to speed specification approvals and reduce procurement friction.
-
Scale aftermarket and retrofit capabilities to monetize the installed base — focus on preventive maintenance, control-enclosure upgrades, and capacity retrofits where lifecycle economics are compelling.
-
Pursue selective vertical integration or strategic supplier agreements for hydraulics and control hardware to reduce lead-time exposure.
-
Differentiate on serviceability: simplify field maintenance, provide clear documentation for facility teams, and offer predictable SLAs to win long-term contracts.
-
Use targeted M&A to acquire distribution reach or niche engineering IP in environmental-protected controls or high-capacity designs.
Concluding perspective
The hydraulic dock leveler market presents a reliably growing, technically nuanced opportunity for companies that can align product engineering with emerging standards, operational reliability, and aftermarket service economics. With a mid-single-digit CAGR and a clear trajectory from the 2025 base year, 2026 is a year for tactical moves: lock in compliance-based product offerings, bolster aftermarket revenue streams, and shore up supply chains to convert forecasted demand into predictable, profitable growth.
For detailed segment tables, vendor share models, downloadable forecast workbooks, and tactical implementation templates, refer to the full PW Consulting report. The dataset and appendices contain the granular numbers and decision tools necessary to operationalize the strategic recommendations outlined above.
For detailed analysis of this topic, please visit the official page: Hydraulic Dock Leveler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EVSE market to reach USD 1,079M by 2032, expanding at a 29.1% CAGR
By pmarketresearch, 2026-07-30
EVSE Market Outlook 2026: Strategic Imperatives for Corporate Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking executive orientation to our latest Electric Vehicle Service Equipment (EVSE) Market study. This briefing is designed to translate the research’s quantitative backbone into the practical, decision-ready intelligence executives need in 2026—without giving away the full segmentation tables and proprietary scorecards included in the full report. Consider this a high-fidelity preview: substantive, diagnostic, and strategically prescriptive—yet intentionally incomplete to encourage a site visit for the full dataset and tools.
Electric Vehicle Service Equipment (EVSE) Market
Why 2026 Is the Inflection Point
The EVSE market is shifting from pilot-phase deployments to commercial-scale rollouts. Our model—anchored on a 2025 base year and projecting through 2032—shows a compound annual growth rate (CAGR) of 29.1% across the 2026–2032 forecast window. In concrete terms, the market expands from an estimated USD 180 Million in 2025 to more than USD 1,079 Million by 2032, with an intermediate jump to around USD 228.7 Million in 2026. That pace is not mere hype: it signals compressed timelines for ROI, accelerated supplier selection cycles, and materially different capex/opex profiles for projects initiated in 2026 versus those delayed a year or two.
Electric Vehicle Service Equipment (EVSE) Market
What This Research Delivers—Practical, Actionable, and Operational
-
High-resolution demand and supply model: a calibrated market-size baseline, validated growth drivers, and scenario runs that stress-test adoption curves under different regulatory and technology trajectories.
Electric Vehicle Service Equipment (EVSE) Market -
Deployment playbooks: site assessment checklists, electrical upgrade matrices, and installation labor-cost frameworks ready to be adapted to enterprise procurement cycles.
-
Financial tools: project-level TCO and payback models, procurement contract templates, and sensitivity analyses for energy tariffs, demand charges, and utilization profiles.
-
Vendor benchmarking and commercial scorecards: qualitative and quantitative assessments of market leaders, challenger offerings, and emerging platforms—presented to support shortlists and RFPs.
-
Standards and compliance map: a living register of certification requirements, product safety standards, and regional procurement constraints (with integration guidance for compliance workflows).
-
Execution roadmaps: 90/180/365-day action plans to move from strategy to pilot to scale—covering technology, financing, operations, and stakeholder communications.
Key Strategic Takeaways for 2026 Decision-Makers
-
Act to lock in technology-platform advantages now. With near-term market growth accelerating, early procurement choices and trial partnerships will shape unit economics and partner ecosystems for years. The difference between “early adopter” and “legacy integrator” will often be decided by 2026 deployment velocity.
-
Design procurement to manage standards and localization risk. Regulatory moves—especially those touching domestic sourcing requirements and certification regimes—mean procurement teams should include compliance gates and alternate-sourcing clauses in contracts.
-
Optimize for site-level utilization, not just unit cost. Rising utilization will make the economics of faster charging, managed load control, and smart metering more attractive; conversely, incorrect mix choices can extend payback timelines even as the market grows rapidly.
-
Prioritize interoperability and future-proofing. Connector standards, software APIs, and bidirectional capabilities are converging into the most durable competitive advantages. Suppliers with flexible upgrade pathways reduce stranded-asset risk.
-
Prepare for consolidation pressure and partnership-led growth. Market concentration metrics indicate a fragmented landscape with scope for consolidation and strategic alliances—smart acquirers and incumbent alliances will capture distribution and scale advantages in the coming 18–36 months.
Competitive Landscape: Who Matters and Why
The vendor environment is diverse: established electrical and industrial players, specialist fast-charger manufacturers, network operators, and standards/validation institutions all have consequential roles. A few exemplars and their strategic implications:
-
ChargePoint — A platform-first supplier with breadth across residential, commercial, and fast-charging offerings. Recent product launches that embed driver management and reimbursement workflows highlight a strategy to capture fleet and corporate mobility budgets as much as hardware spend. Expect ChargePoint to double down on software-led monetization and enterprise integrations.
-
Eaton (partnering with ChargePoint) — Using joint offerings to push into ultrafast DC and integrated power management demonstrates an industrial-playbook approach: combine distribution, electrical hardware, and systems integration to address grid-constraint projects and large-scale commercial deployments.
-
Tritium — Focused on scalable DC fast charging platforms, the vendor’s modular TRI-FLEX architecture is tailored for commercial and fleet rollouts. For corporations building depot or corridor charging, modular scalability is a major operational advantage.
-
ABB — Targeting megawatt-scale and high-duty-cycle requirements, its product families are positioned for heavy-duty vehicle charging and industrial use-cases where uptime and power density matter most.
-
Siemens — Offering connected charging hardware with enterprise-grade metering and grid features, Siemens is a logical partner where integration with building energy management and utility-scale projects is required.
-
EVgo — An operator-first player expanding connector compatibility and network footprint. Their strategy points to expansion via on-network growth and interoperability bets that can shape charging network economics.
-
EPRI — As the curator of vetted product lists and utility-facing validation, EPRI’s role is pivotal for suppliers and buyers seeking utility approval and long-term operational credibility.
Each of these profiles maps to specific strategic choices: partner versus vendor, software-first versus hardware-first, or operator versus supplier models. The detailed vendor scorecards in the full report provide procurement teams with the comparative criteria and weighted scoring recommended for 2026 RFPs.
Regulatory and Standards Dynamics: Tailwinds and Risks
Several regulatory and standards developments are actively reshaping procurement and deployment risk in 2026:
-
Procurement localization rules and waiver reviews are increasing the cost of global sourcing for EVSE. This changes supplier selection dynamics for projects that rely on federally funded or public right-of-way installations.
-
Updates to measurement and metering directives create a requirement regime that intersects with revenue-quality metering in public charging—projects without compliant metering may face remedial costs and delayed revenue recognition.
-
Standardization and safety certifications, including recent updates urging UL-certified adapters and accessories, make certification diligence non-negotiable—buyers should require documented evidence of standard compliance during technical evaluation phases.
-
Regional rebate and grant programs targeting residential and commercial deployments materially change the investment calculus for certain projects—our report identifies how program design influences vendor economics and customer acquisition strategies.
From Insight to Action: 90/180/365 Day Roadmaps
-
90 days: Run a sourcing health-check and standards compliance audit for planned 2026 projects; assemble a two-vendor shortlist per use-case; deploy a proof-of-concept at a single high-utilization site using one modular DC fast charger or managed AC station.
-
180 days: Execute pilots with full telemetry and meter-integration, negotiate master services agreements with performance SLAs, and begin permitting and grid-connection negotiations informed by the report’s utility-engagement playbook.
-
365 days: Scale procurement using standardized contracts, operational processes, and a supplier governance model; evaluate strategic partnership or acquisition opportunities informed by competitive concentration and vendor roadmaps.
Why PW Consulting’s EVSE Market Study Matters for Your 2026 Planning
Decisions made in 2026 will disproportionately affect cost structures and strategic positioning across the next business cycle. Our report combines a detailed market model (with base-year 2025 calibration), practical implementation toolkits, and vendor-level intelligence to help executives move from impulsive procurement to deliberate market capture. The macro trajectory—a strong double-digit CAGR and a market expanding by multiple times through 2032—creates both huge upside and significant execution risk. The difference between capturing value and becoming a reactionary buyer will be judged by the quality of your procurement playbook, your standards/compliance posture, and the speed of your pilot-to-scale pathway.
For those ready to translate this preview into an executable plan, the full study contains the granular segmentation matrices, regional and application-level forecasts, downloadable financial models, and vendor scorecards that operational teams require. Visit our report page to access the complete dataset, templates, and a companion webinar where our analysts walk through the model assumptions and scenario outcomes live.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Service Equipment (EVSE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
AC Current Transformers for Electrical Meters: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a high-conviction, action-oriented primer on the AC current transformer (CT) market for electrical meters — a compact, technically nuanced segment whose near-term behaviour will exert outsized influence on metering accuracy, smart-grid deployments, and utility capex strategies in 2026. This preview distills the macro trajectory, the competitive map, regulatory inflections, and pragmatic, scenario-based guidance executives need to prioritize investments and procurement decisions this year. It deliberately highlights analytical depth while preserving proprietary segment-level detail — think of this as the trailer that proves we understand the movie, and points you to the ticket counter for the full screening.
AC Current Transformers (CT) for Electrical Meters Market
Why this market matters to corporate strategy in 2026
-
Revenue-grade metering and the expanding smart-meter base are elevating the role of CTs from passive components to mission-critical accuracy enablers. For utilities, meter manufacturers, and system integrators, CT selection now directly affects billing integrity, regulatory compliance, and lifetime O&M costs.
AC Current Transformers (CT) for Electrical Meters Market -
Hardware choices made in 2026 — for new installations, retrofits, or supplier consolidation — will cascade through product roadmaps and supply chains for the next 5–7 years. Decisions on core technologies (nanocrystalline cores vs. traditional materials), form factors (split-core, solid-core, Rogowski), and supplier risk management are therefore strategic, not tactical.
AC Current Transformers (CT) for Electrical Meters Market -
Regulatory updates and interoperability requirements emerging this year increase the cost of late compliance; early alignment will produce competitive differentiation through faster time-to-market and fewer field interventions.
Market trajectory: the headline numbers you should anchor to
At a macro level, the AC CT market for electrical meters is on a steady growth path. Using 2025 as the base year, our market model places total industry revenue at approximately USD 263.13 Million that year. Under the central scenario (which incorporates measured smart-meter rollouts, steady industrial modernization, and incremental upgrades), we project a compound annual growth rate (CAGR) of about 4.5% across the 2026–2032 forecast window. That trajectory implies a market that rises to roughly USD 356.3 Million by 2032, with intermediate annual expansion that buyers and suppliers should anticipate when sizing production runs and negotiating multi‑year supply agreements.
Two implications flow directly from these figures: first, aggregate demand is robust enough to justify incremental capacity investments and targeted supply-chain partnerships in 2026; second, the growth rate is not hyperbolic, which places a premium on operational efficiency, product differentiation, and targeted segmentation to capture above-market returns.
Dynamics reshaping the competitive and regulatory landscape
-
Standards and certification cycles: The publication of ANSI C12.1-2026 and related updates has tightened performance expectations for revenue meters and their auxiliary components, including CTs. The standard’s amendments — such as clarified test protocols for radio-frequency immunity — increase testing complexity for meter assemblies and shift procurement emphasis toward CT vendors who can demonstrate rigorous, testable compliance.
-
Government and utility programs: Regulatory momentum in several large markets is aligning incentives and technical requirements to accelerate smart-meter rollouts. Proposed amendments (for example, from authorities focused on improved billing accuracy) create near-term tender opportunities but also require suppliers to be pre-qualified on tighter specs.
-
Technology and materials: Advances in core materials (nanocrystalline alloys, specialized ferrites), alongside alternative sensing technologies (Rogowski coils for high-current installations), are bifurcating the product set between cost-optimized commodity CTs and higher-margin, accuracy-focused devices suited for revenue metering and sensitive grid-edge applications.
-
Manufacturing footprint and supply resilience: Geopolitical and logistics pressures have made dual-sourcing and regional inventory strategies more valuable. Buyers should evaluate supplier capabilities not only by price and specifications, but by demonstrated ability to sustain shipment performance during spikes (e.g., synchronized smart meter tender cycles).
Competitive landscape — who matters and what they bring
The market is commercially diverse: a mix of well-established European precision manufacturers, North American specialists in revenue-grade products, and agile Asian OEMs supplying integrated meter components. Market concentration is moderate; the largest trios do not dominate the market fully, which leaves room for nimble niche players and OEM partnerships.
-
Vacuumschmelze (Hanau, Germany) — Strengths: specialist core materials (nanocrystalline VITROPERM/VITROVAC) and deep experience serving IEC/ANSI markets. Strategic implication: best-in-class for high-accuracy metering projects that require stringent material performance and repeatable certification workstreams.
-
Accuenergy (United States) — Strengths: bespoke, revenue-grade split-core and solid-core CTs tailored for precise power monitoring. Strategic implication: attractive partner for integrators who need configurable CTs and close engineering collaboration for hybrid metering systems.
-
LEM (Switzerland) — Strengths: established AT series and brand recognition in automation and smart-grid segments. Strategic implication: preferred for projects where integration with broader instrument transformer portfolios and long-lived service contracts matter.
-
Phoenix Contact (Germany) — Strengths: solutions for both new installations and retrofitting; product lines that ease field conversion to 1 A or 5 A standards. Strategic implication: strong contender where installers favor products that reduce on-site work and simplify retrofits.
-
Electro-Meters (United States) , Flex-Core (United States) , Oswell E‑Group (China) , GFUVE GROUP (China) , and YTL Meter (China) — Strengths: variously offer product breadth, inventory depth, compact split-core designs, or local market access. Strategic implication: a mix of cost-effective supply options and regional partners for large-scale meter rollouts.
Recent vendor activity underlines two themes: a push for product and technical leadership (for example, technical guides and whitepapers that reduce field risk), and the bundling of CTs into multifunction metering solutions. Notable developments include technical guidance releases that clarify CT performance expectations in smart-meter assemblies and the launch of multifunction power meters that integrate high-precision CTs. These moves reflect suppliers’ intent to capture more value across the metering stack, and they change procurement calculus: buying a CT in isolation versus buying a CT as part of an instrumented metering system yields different cost and risk profiles.
What our full report delivers (practical, executable content)
Our AC CT market study is built for decision-makers who need to translate market dynamics into operational plans in 2026. Highlights include:
-
Proprietary market model with historical calibration (2020–2025) and scenario-based forecasts across 2026–2032, enabling stress-testing of procurement strategies against low/central/high adoption pathways.
-
Supplier scorecards that benchmark technical performance (accuracy classes, material technologies, form factors), manufacturing capacity, lead-time reliability, and certification readiness — presented to facilitate RFP shortlisting.
-
Regulatory impact maps showing where standards changes materially affect product specifications and test requirements, and a compliance playbook for vendors and buyers alike.
-
Procurement playbooks and contract templates that address common pitfalls in volume commitments, warranty claims, and field-recall liabilities specific to CTs used in revenue metering.
-
Case studies and field-evidence on metering performance outcomes across residential, commercial, and industrial deployments — with practical checklists to reduce smart-metering production delays attributable to CT selection.
Note: while this introduction synthesizes the market’s macro trends and competitive dynamics, the report contains detailed segment-level breakdowns, supplier rankings, and price benchmarks that we intentionally withhold here — these are the core intelligence that the full report delivers to subscribers.
Strategic recommendations for 2026 (actionable, prioritized)
-
Segment your 2026 procurement into three tracks: (1) high‑accuracy projects requiring premium CTs; (2) mass-deployment rollouts where unit cost and lead time matter most; and (3) retrofit/field-replacement inventory for rapid-response deployments. Allocate R&D or supplier-development budgets accordingly.
-
Pre-qualify two complementary suppliers per procurement track to mitigate single-supplier risk, emphasizing documented compliance with ANSI C12.1-2026 and equivalent regional standards.
-
Require test-report packages and a limited pilot run before mass procurement. Our field analysis shows that early pilot feedback on CT integration materially reduces production delays in meter manufacturing and commissioning.
-
Embed performance‑based contract clauses tied to accuracy consistency and lifecycle warranty to align supplier incentives with in-service meter performance.
-
Invest in supplier co-engineering where new materials or form factors are being deployed; a small upfront engineering commitment can unlock lower unit cost and fewer field interventions over the product lifecycle.
Concluding perspective and next step
The AC current transformer market for electrical meters in 2026 is neither a high-velocity breakout nor a flat commodity arena; it is a measured-growth market where technical differentiation, regulatory alignment, and supply-chain resilience determine who captures the premium. With a base-year revenue near USD 263.13 Million and a central CAGR of approximately 4.5% through 2032 (to roughly USD 356.3 Million), the opportunity is clear — but so is the need for disciplined, data‑driven supplier and product strategies.
PW Consulting’s full report contains the quantitative segment breakdowns, supplier scorecards, price benchmarks, and procurement templates you need to move from strategy to execution this year. For clients preparing 2026 capex plans, RFPs, or supplier consolidation programs, the report reduces execution risk and shortens time-to-compliance.
To obtain the full dataset, supplier rankings, and practical annexes referenced above, please visit our report page or contact your PW Consulting representative. The executive summary you have here provides the why and the what; the full report provides the how.
For detailed analysis of this topic, please visit the official page: AC Current Transformers (CT) for Electrical Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biological Safety Cabinet Market to reach USD 329.0 Million by 2032 (7.5% CAGR)
By pmarketresearch, 2026-07-30
Biological Safety Cabinet Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a condensed preview of our comprehensive Biological Safety Cabinet (BSC) Market research — a pragmatic intelligence asset designed to inform capital allocation, product strategy, and regulatory compliance decisions in 2026. The market has demonstrated steady expansion throughout the last half-decade and is on a clear growth trajectory: aggregate market value rose meaningfully from the low hundreds of million USD in 2020 to approximately 197.5 Million USD in our 2025 base year, and our forecast projects continued growth at a compound annual growth rate (CAGR) of 7.5% through the 2026–2032 window, reaching roughly 329.0 Million USD by 2032. This narrative highlights the strategic implications of those macro dynamics while deliberately omitting granular subsegment tables and region/application breakdowns — the proprietary detail that drives transaction and procurement decisions is available exclusively in the full report.
Biological Safety Cabinet Market
Why this research matters in 2026
- Capital planning and plant design: Buyers and OEMs need reliable topline and scenario-driven forecasts to time capacity investments and factory upgrades that comply with evolving safety standards.
- Product roadmaps: Engineering teams must prioritize features — adaptive airflow, integrated monitoring, filter integrity diagnostics, ergonomic design — that will determine competitive positioning as certification requirements tighten.
- Aftermarket & service strategy: With annual field certification increasingly mandated, service networks and digital maintenance contracts become durable, high-margin revenue streams.
- M&A and partnership screening: Investors and corporate development teams require granular, model-backed valuation levers to identify bolt-on opportunities in filtration technology, sensor hardware, and service platforms.
- Procurement and compliance: Hospital systems, research institutions, and pharma facilities must balance total cost of ownership (TCO) against compliance risk amid shifting international standards.
Scope and practical contents of the full report
The full PW Consulting study is engineered to be actionable for C-suite and product teams. Key deliverables include:
Biological Safety Cabinet Market
- Market sizing and forecast methodology (2020–2025 historical base; 2026–2032 forecast horizon)
- Demand-driver analysis: R&D spending trends, hospital lab modernization, biosafety program investments
- Detailed regulatory and standards impact assessment, with testing matrices tied to certification timelines
- Competitive intelligence dossiers and capability maps for incumbent and challenger firms
- Product segmentation and technology roadmaps (including retrofit and modular designs)
- Service, spare parts, and field certification economics
- Procurement playbooks and RFP language templates for health systems and research institutions
- Scenario-based financial models (base, upside, downside), including sensitivity to pricing, service uptake, and certification cycles
- Strategic recommendations and prioritized initiatives for growth, defensibility, and cost takeout
To preserve the competitive value of the study, granular subsegment tables (regional splits, application shares, precise type-by-type revenues) are intentionally withheld from this preview and provided only in the licensed report package.
Biological Safety Cabinet Market
Key market dynamics and inflection points
Several interlocking dynamics define the BSC market in 2026:
- Regulatory tightening and certification intensity: The adoption of NSF/ANSI 49-2024 mechanisms has elevated the technical bar for BSC design and in-field testing: performance testing now explicitly covers airflow velocities, HEPA/ULPA filter integrity, and routine field certification on a 12-month cadence. Certification programs have widened to include environmental controls such as noise, illumination, vibration attenuation, and electrical safety as part of the acceptance criteria. These requirements materially raise the cost of non-compliance and increase demand for cabinets with integrated monitoring and self-diagnostic capabilities.
- Standards fragmentation in Europe: Revisions to EN 12469 (new parts published in late 2025) removed prescriptive reference values for performance evaluation. The practical outcome is ambiguity for purchasers and a competitive advantage for vendors who can demonstrate verified performance through independent field-certification workflows and documented TCO trade-offs.
- Technology and ergonomics as differentiators: Product features such as adaptive airflow control, improved ergonomics, integrated sensor suites, and easier filter access are shifting purchase decisions from price-centric toward value-centric evaluation frameworks.
- Service and lifecycle economics: With mandatory annual certification cycles and increasingly complex performance metrics, aftermarket service contracts, remote monitoring subscriptions, and rapid filter replace-and-validate offers are becoming mission-critical revenue pools.
- Market concentration and competitive structure: The market exhibits moderate consolidation: the top three players account for a meaningful proportion of revenue, while the top five approach a majority share. That structure leaves room for regional specialists and vertically integrated suppliers to capture niche value through customization, speed-to-delivery, and localized service excellence.
Competitive landscape — who moves first matters
Our competitive mapping focuses on product capability and go-to-market posture rather than price alone. Representative vendor profiles include:
- Thermo Fisher Scientific Inc., Waltham, MA: A global platform player with the Herasafe class II portfolio emphasizing adaptive airflow control and end-user ergonomics. Their recent Herasafe 2025 launch underscores a strategy of continuous product refreshes that align with compliance trends.
- Esco Lifesciences (Esco Micro Pte. Ltd.), Singapore: A filtration-technology-centric supplier offering ULPA/HEPA-equipped Class II solutions. Their engineering DNA supports strong appeals to biotech and research customers focused on contaminant control.
- Labconco Corporation, Kansas City, MO: A diversified laboratory equipment maker whose Purifier Axiom series balances performance with modular serviceability.
- The Baker Company, Sanford, ME: A bespoke engineering supplier that differentiates on made-to-order solutions and rigorous testing — their recent ISO 14001:2015 certification reinforces both compliance credentials and sustainability messaging.
- NuAire, Inc., Plymouth, MN: Known for the LabGard series, NuAire competes on robustness and aftermarket service coverage, an important factor for clinical laboratory buyers.
- Kewaunee Scientific Corporation, Statesville, NC: Integrates BSCs into laboratory furniture systems, a compelling value proposition for large lab construction projects — their strategic alliance with NuAire aims to blend furniture and biosafety portfolios for global customers.
Recent strategic moves — product launches, certifications, and alliances — demonstrate two emergent manufacturer plays: (1) feature-led differentiation (adaptive airflow, sensor fusion), and (2) platform + service consolidation (integrated furniture partnerships, global service networks). These plays materially affect lead times, pricing power, and aftermarket margins.
Strategic plays for 2026 — recommended actions
- Manufacturers: Prioritize modular platform architectures that allow rapid tech upgrades (sensors, remote monitoring) while meeting NSF/ANSI and equivalent standards. Invest in field-certification enablement kits and certified service partner networks to shorten procurement cycles.
- Buyers (health systems, labs, pharma): Shift procurement evaluation from upfront CAPEX to TCO models that include annual certification, planned filter replacement, and remote diagnostics. Negotiate outcome-based service SLAs tied to certification pass rates.
- Private equity and strategic investors: Target niche filtration technology, sensor integration firms, and regional service providers that can scale via bolt-on acquisitions to quickly move up the value chain.
- Policy makers and standard bodies: Support harmonization efforts and promote accredited field-certification capacity to reduce market ambiguity and lower compliance risk for end-users.
How PW Consulting can accelerate your 2026 playbook
Our full report provides the granular data and executable tools needed to act decisively in 2026: downloadable datasets (including region/application/type splits), dynamic financial models, supplier scorecards, RFP templates, and a prioritized roadmap of product and service investments. For procurement teams, we provide bid-evaluation matrices that map technical test outcomes to TCO implications. For investors and M&A teams, we deliver deal screens and accretion/dilution simulations based on multiple service-adoption scenarios.
This preview is intended as a strategic trailer — it demonstrates the depth and direction of our analysis while withholding core subsegment tables and granular regional/application revenue breakdowns to protect the competitive intelligence embedded in the licensed report. To access the full dataset, provider matrix, and scenario models that underpin the figures cited above, request PW Consulting’s Biological Safety Cabinet Market report package.
Decisions made in 2026 about product R&D spend, service-network buildout, or M&A positioning will determine market leadership for the rest of this decade. Use the market trajectory — from roughly 148 Million USD in 2020 to about 197.5 Million USD in 2025, with a projected path to approximately 329.0 Million USD by 2032 at a 7.5% CAGR — as the strategic backdrop. Then act to capture the premium created by compliance-driven differentiation, service modernization, and platform integration.
For detailed analysis of this topic, please visit the official page: Biological Safety Cabinet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Telescope Market Poised for Modest Growth at 1.42% CAGR
By pmarketresearch, 2026-07-30
Telescope Market 2026: Strategic Imperatives from PW Consulting’s Telescope Market Preview
Executive teaser
The global telescope market is entering a period defined less by explosive growth than by structural reconfiguration. PW Consulting’s Telescope Market Preview—anchored on 2025 as the base year—documents a market that expanded modestly from 2020 through 2025 and is projected to grow at a restrained compound annual growth rate (CAGR) of 1.42% across the 2026–2032 forecast window. Total market value moved from a low-double-digit baseline in 2020 to a stronger, but still measured, position by 2025; our forecast anticipates continued, uneven expansion through 2032. For 2026 strategic planning cycles, this report converts those top-line dynamics into operational imperatives, risk scenarios, and executable playbooks for manufacturers, distributors, and strategic investors.
Telescope Market
Why this preview matters for 2026 decision-making
- From growth to margin and resilience: With a low-single-digit CAGR in the forecast period, the industry is shifting focus from volume-driven expansion to margin preservation, product differentiation, and supply-chain resilience. Leaders in 2026 will be those who translate modest market expansion into outsized returns through cost-to-serve optimization and targeted premiumization.
- Consolidation and concentration: Market concentration is material: the top three players control a meaningful majority of the market, and the top five extend that dominance further. This structure creates both barriers and opportunities—scale advantages for incumbents, and niche entry points for specialists and vertically integrated newcomers.
- Near-term shocks informing long-term strategy: Recent policy and trade shocks underscore the necessity of scenario-based strategic planning rather than linear forecasting. Firms that adopt flexible sourcing, dual-sourcing of critical optics/electronics, and dynamic pricing will outperform peers.
Core themes that will shape supplier and investor choices in 2026
- Supply-chain reconfiguration: Tariff movements and trade frictions in 2025 shifted sourcing economics dramatically. The industry’s response is now a mix of near-shoring, supplier consolidation, and inventory strategy revision. Decision-makers must quantify the cost of resilience (inventory carrying, domestic tooling, logistics) against the risk of disrupted access to key components.
- Technology fusion: optics + software: Astrophotography, smart-guidance systems, and software-defined telescopes are blurring product boundaries. Hardware manufacturers who either embed software or partner with software-first firms can capture higher lifetime value per customer and control aftermarket monetization.
- Channel economics and consumer behavior: Direct-to-consumer models, specialist retailers, and community-driven sales (e.g., clubs, educational partnerships) coexist with legacy distribution. Companies should map acquisition costs and lifetime value by channel and product tier to allocate sales and marketing efficiently.
- Premium vs. accessible stratification: The market bifurcates into premium, high-margin instruments tailored for advanced amateurs and institutions, and accessible, feature-rich products for mass-market enthusiasts. Portfolio strategies must reconcile R&D cadence with time-to-market and inventory risk.
Report highlights: actionable content inside the full study
PW Consulting’s Telescope Market Preview distills public and proprietary inputs into a practitioner-focused toolkit. Highlights include:
Telescope Market
- Forward-looking demand scenarios (base, upside, downside) that stress-test revenue, margin and working capital under tariff, supplier failure, and demand-shock assumptions.
- Profitability levers by product archetype—showing where gross margin can be reclaimed through design simplification, supplier rationalization, and modular service offerings.
- Channel and go-to-market playbooks: CAC/LTV tables, distributor economics, OEM vs. brand-led retail considerations, and a decision matrix for direct digital channels.
- Supply-chain heat maps and contingency protocols that prioritize optics, mounts, and imaging electronics—plus a supplier-sourcing scorecard to operationalize near-shoring or diversification moves.
- M&A and partnership screening filters tuned to consolidation dynamics—identifying targets that fill capability gaps (software, mounts, imaging), provide geographic hedges, or add aftermarket revenue streams.
- Product roadmap templates that balance technological novelty (image sensors, harmonic-drive mounts, integrated processing) with manufacturability and aftermarket serviceability.
- Regulatory and trade-impact playbooks presenting costed scenarios for import tariffs, certification timelines, and strategic inventory positioning.
Competitive landscape: positioning the core players
Our competitive analysis synthesizes firm-level strengths, strategic intent, and recent moves to clarify where each actor competes and which white spaces remain.
Telescope Market
- Celestron (Torrance, CA) —A legacy consumer brand that continues to invest in smart telescopes and accessible astrophotography platforms. Their portfolio refreshes and smart-telescope launches reflect a push to convert casual buyers into platform customers with software and accessory ecosystems.
- ZWO / Zhen Wang Optical (Suzhou, China) —A leader in astrophotography sensors and smart-imaging modules; excels in vertically integrated design-to-manufacture cycles. Their position underscores the importance of component control and rapid product iteration.
- Astro-Physics (Barrington, IL) —Specializes in high-end mounts and precision instruments for advanced amateurs and institutions. Their value is in craftsmanship and a reputation that sustains premium pricing.
- Takahashi Seisakusho (Tokyo) —A premium optics house with strong brand equity among enthusiasts and institutions. Their craftsmanship strategy highlights the advantages of a differentiated, quality-first product posture.
- WarpAstron (Shanghai) and MLAstro (China) —Both signal the maturation of affordable, high-functionality astrophotography tools and subsystems. They represent the competitive pressure at the middle and value tiers of the market.
- Observable Space (Los Angeles) —Formed through strategic consolidation of PlaneWave Instruments and OurSky, this software-defined and systems-focused entrant demonstrates a consolidation trend toward integrated hardware-software telescopes and observatories.
Recent industry moves and what they imply
- M&A and consolidation: Strategic acquisitions and mergers in early 2025 accelerated platform consolidation. Buyers are acquiring inventory, IP, and go-to-market capabilities to bridge immediate supply interruptions and to scale distribution.
- Product innovation: Product launches in 2025 emphasize smaller, smarter, and faster-to-market instruments—reflecting a trend toward consumer-friendly astrophotography and turnkey observation solutions.
- Trade and regulation: Tariff increases enacted in 2025—significantly raising duties on certain imported telescope components—have immediate pricing and availability consequences. These regulatory shocks are forcing short-term trade-offs between margin compression and service continuity, and long-term investment in alternative sourcing.
Strategic playbook: what executives should do in 2026
- Run portfolio stress tests: Use scenario outputs to identify which SKUs are margin-accretive under tariff and logistics shocks. Prioritize SKUs for onshore tooling or alternate sourcing that protect gross margins.
- Invest in software-enabled differentiation: Embed or partner for software to build recurring revenue (firmware updates, cloud processing, imaging stacks) and to increase customer lifetime value.
- Targeted M&A and partnerships: Pursue tuck-ins that accelerate capability in mounts, imaging, or software rather than broadscale revenue acquisition. Acquire providers that fill a strategic gap and reduce exposure to constrained suppliers.
- Rework channel economics: Rebalance distributor agreements and direct channels to reduce middleman margins where necessary, and create premium service tiers through installer or institutional packages for stable revenue.
- Operationalize resilience: Quantify the trade-offs between inventory buffers, dual-sourcing, and domestic manufacturing. Create an early-warning supplier index to trigger contingency playbooks when critical inputs show elevated risk.
What the full report unlocks (and what we deliberately withhold here)
This preview is designed to demonstrate the rigor and applicability of PW Consulting’s full Telescope Market study. The complete report includes granular segmentation, regional dynamics, and quantified channel economics that are essential for execution-level investment or product decisions. In this public synopsis we intentionally present directional findings, firm-level strategy implications, and methodological transparency—while reserving detailed segment-level tables, regional breakout percentages, and proprietary unit-price modeling for the full deliverable accessible through our client portal.
Methodology and data fidelity
Our analysis synthesizes primary interviews, company disclosures, customs and trade datasets, and proprietary demand models. Historical baseline covers 2020–2025 with 2025 as base year; forecasts run through 2032 using a combination of trend extrapolation, scenario adjustment for trade/regulatory risk, and bottom-up SKU-level modeling for major manufacturers. Market concentration metrics are derived from reconciled firm revenues and validated against public filings and distributor intelligence.
Final takeaway for 2026 planners
2026 will be a year where leadership is defined not by capturing a rapidly expanding market, but by managing fragility and extracting margin from a stable-to-slow-growth environment. Companies that strategically prioritize supply-chain resilience, software-enabled product ecosystems, and selective consolidation will convert modest market growth into sustainable competitive advantage. PW Consulting’s Telescope Market Preview provides the strategic framing; the full report supplies the datasets, segment analytics, and executable templates you will need to operationalize the moves described here.
For access to the complete dataset, regional breakouts, and the full suite of playbooks and valuation tools referenced above, visit our report landing page to view the full Telescope Market study and download the executive dashboard.
For detailed analysis of this topic, please visit the official page: Telescope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com