

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Copper Sulfate Pentahydrate Market to Hit USD 576.8M by 2032 (5.4% CAGR)

Copper Sulfate Pentahydrate Market: Strategic Intelligence for 2026 Decision-Making
Executive trailer
As companies realign supply chains and product portfolios for the post‑pandemic and decarbonization eras, Copper Sulfate Pentahydrate emerges as a quietly critical intermediate across agriculture, feed, electroplating and specialty industrial applications. This PW Consulting briefing introduces our full Copper Sulfate Pentahydrate Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) and explains why the insights it contains are indispensable for boardrooms and procurement teams planning for 2026.
Copper Sulfate Pentahydrate Market
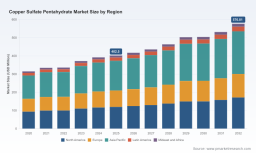
Key macro position: the global market, measured in USD Million, expanded from approximately 315.2 in 2020 to 402.5 in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.4% through 2032 — reaching an estimated 576.8 by 2032. These topline dynamics reflect the combined effects of agricultural demand resilience, selective industrial recovery, and periodic supply shocks that amplify volatility in certain grades.
Copper Sulfate Pentahydrate Market
Why this report matters for 2026 strategy
-
Operational resilience: the market’s steady mid‑single‑digit CAGR masks episodic supply and quality disruptions that can rapidly cascade into production stoppages or costly recalls. Companies that treat copper sulfate as a strategic raw material — not a commoditized, low‑touch buy — will avoid expensive remediation.
Copper Sulfate Pentahydrate Market -
Regulatory and reputational risk: recent regulatory activity (notably a voluntary recall in April 2026 of contaminated feed‑grade lots originating from China) underscores the need for traceability, batch testing, and contract clauses that allocate recall costs. The recall and confirming reports of dioxin contamination have already prompted faster adoption of upstream verification protocols among North American and European buyers.
-
Commercial differentiation: as customers demand higher‑assurance materials (GMP/USP/FCC/technical certificates, documented supply chains, and product stewardship), producers with certified quality systems and transparent traceability can capture premium pricing and longer contracts.
-
M&A and vertical plays: the market’s structure and pockets of regional specialization create tactical opportunities for acquisitive buyers to secure high‑purity feeds, backward integrate into feed‑grade production, or establish regional hubs that reduce lead times and import risk.
What the full report delivers (practical, transaction‑ready content)
-
Robust market sizing and forecast model (USD Million; 2020–2032) with build‑up logic and sensitivity toggles to test price, feedstock availability and regulatory stress scenarios.
-
Demand driver diagnostics by grade and application, with elasticities and scenario impacts (presented qualitatively in this preview; granular subsegment volumes and shares are reserved for the full report to maintain competitive value).
-
Supply map and capacity registry covering global producers, conversion facilities, and logistical chokepoints; includes lead‑time benchmarks and alternative routing playbooks for emergency sourcing.
-
Supplier due‑diligence toolkit: audit checklists, required certificate templates, in‑market testing regimes and contract language to mitigate contamination risk and supplier non‑performance.
-
Price build and trade dynamics: raw‑material drivers, pass‑through analysis, and a proprietary pricing deck for use in negotiation and budgeting.
-
Regulatory tracker and recall playbook: mapping of current controls across major markets, recall impact scenarios, insurance considerations and crisis communication templates.
-
Competitive landscape intelligence: profiles and strategic positioning of key players, capability matrices, and a short list of potential targets and partners for buyers and investors.
-
Actionable growth roadmaps: go‑to‑market plays, cost‑to‑serve optimization, and a prioritized list of tactical initiatives with expected ROI and implementation timelines for 6–24 months.
High‑level competitive landscape and strategic implications
The Copper Sulfate Pentahydrate market sits in a middle ground of specialization: several established producers serve distinct channels (pharma/nutraceutical, agricultural, feed, electroplating, and industrial uses), while many smaller suppliers address local commodity demand. The market is best characterized as moderately fragmented: the largest regional players collectively do not exert dominant, global pricing control, leaving room for consolidation and margin capture through quality differentiation and logistics efficiency.
-
Shreeji Industries (India) — GMP‑certified manufacturer supplying IP/BP/USP/FCC grades. Strengths: pharmaceutical‑grade credentials, multi‑grade capability and a clear focus on higher‑value channels (nutraceuticals, fungicides, electroplating). Strategic implication: potential partner or acquisition target for firms seeking a certified, Asia‑based, quality‑assured source and faster entry into regulated markets.
-
Sulfozyme Agro India Pvt Ltd (India) — supplier oriented to agricultural and technical grades for plant nutrition, fungicide formulations and feed additives. Strengths: proximity to large agricultural demand pools, specialized technical grade production. Strategic implication: attractive for agricultural chemical formulators that require integrated supply and formulation co‑development; also a candidate for off‑taker agreements or joint quality uplift programs.
-
Univerical (United States) — North American manufacturer of high‑purity liquid and crystalline products for electroplating and industrial uses. Strengths: regional manufacturing, focus on high‑purity and plating‑on‑plastics niches, shorter lead times for North American customers. Strategic implication: natural partner for Western buyers seeking to reduce import dependency and to secure more consistent quality for industrial applications.
Each player illustrates a strategic axis buyers should evaluate: quality certification (GMP/USP/FCC), geographic risk (local production vs. import dependence), and channel focus (agriculture/feed vs. electroplating/industrial). The full report contains head‑to‑head capability matrices and supplier scorecards that buyers can use immediately in sourcing decisions.
Supply‑chain vulnerability spotlight — the 2026 contamination episode
April 2026 saw a voluntary recall of contaminated feed‑grade Copper (II) Sulfate Pentahydrate lots originating from China, reported by the Animal Nutrition Association of Canada and flagged by national food safety authorities. The contamination—associated with dioxin residues—has tangible operational implications:
-
Immediate testing and batch hold policies are now business‑critical for feed and agricultural formulators selling into regulated markets.
-
Buyers must reassess audit frequency, third‑party lab validation, and contractual warranties to allocate recall and remediation costs.
-
Regionalization of supply (or strategic inventory buffers) may be justified despite added holding costs for customers with zero‑tolerance product profiles.
The PW report contains a forensic appendix on the recall, a recommended lab‑testing protocol, and a supplier‑risk matrix that quantifies expected disruption costs under multiple contamination scenarios.
Strategic recommendations for leadership teams planning in 2026
-
Procurement: shift from single‑source spot buys toward blended buying strategies: certified regional suppliers for critical applications and vetted global suppliers for cost flexibility. Implement mandatory incoming batch testing for feed and pharma grades.
-
Quality & Regulatory: prioritize suppliers with third‑party certifications and documented chain‑of‑custody. Insert contractual clauses for recall liability, and secure contingent supply agreements with tested alternates.
-
Operations: evaluate regional buffer stocks and near‑shoring for high‑assurance grades. Rebalance safety stock vs. working capital to reflect the realized risk premium post‑recall.
-
Commercial & R&D: explore premiumization for traceable, certified grades and invest in formulation changes that reduce copper sulfate dependence where possible (or increase recrystallization/upgrade steps to capture margin).
-
M&A & Partnerships: screen targets that provide quality uplift, regional manufacturing, or access to regulated markets. Consider minority investments in certified producers to secure preferential supply.
-
Risk & Finance: stress‑test budgets with the PW forecast scenarios (base, supply shock, regulatory tightening) and ensure insurance coverage aligns with identified recall exposure.
How to use this briefing and next steps
This article is a focused executive preview designed to communicate the strategic value embedded in our full market study. For procurement teams, the buyer’s toolkit and supplier scorecards are immediately actionable. For corporate strategy and M&A teams, the sector mapping and candidate shortlists accelerate diligence. For R&D and product teams, the formulation impact assessments spotlight opportunities to reduce raw material intensity or develop premium, differentiated product lines.
The complete PW Copper Sulfate Pentahydrate Market report contains the granular sub‑segment volumes, regional and application splits, price decks, full company profiles and the quantitative scenario models that underpin the recommendations summarized above. Those detailed elements are intentionally held in the full report to preserve competitive advantage — and they are precisely what your commercial and sourcing teams will need to operationalize 2026 plans.
Call to action
To obtain the full dataset, supplier scorecards, risk matrices and the downloadable forecast model (2026–2032), visit our report page or contact PW Consulting’s industry team. If you are preparing 2026 budgets, negotiating multi‑year offtake agreements, or evaluating acquisition targets, securing the complete intelligence now will materially shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Copper Sulfate Pentahydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com