

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: DTH Drill Market USD 1,355M in 2025, set for 4.5% CAGR (2026–2032)

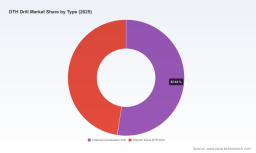
DTH Drill Market — 2026 Strategic Preview
As organizations calibrate capital deployment and operational priorities for 2026, the Deep Trench Hammer (DTH) drill market is transitioning from incremental improvement to selective reinvention. PW Consulting’s latest DTH Drill Market study (base year 2025, forecast 2026–2032) synthesizes longitudinal market sizing, competitive positioning, and applied technology levers into a single usable framework for commercial leaders, procurement chiefs, and engineering heads. This preview highlights the study’s strategic value while intentionally withholding granular subsegment tables and regional/application splits — the exact data and scenario matrices are available in the full report.
DTH Drill Market
Macro Snapshot: Growth Trajectory and What It Means
The DTH drill market has shown steady expansion over the past half-decade. Our modeling indicates growth from approximately USD 1,100 Million in 2020 to USD 1,355 Million in 2025, and a continued rise through the forecast window to roughly USD 1,853 Million by 2032. That trajectory implies a mid-single-digit compound annual growth rate (CAGR) of 4.5% across the forecast period (2026–2032).
DTH Drill Market
For executives, that CAGR and trajectory carry three immediate implications: (1) demand is stable enough to justify targeted investment in product development and aftermarket services; (2) competition will increasingly center on lifecycle economics — fuel/energy efficiency, serviceability, and digital productivity — rather than raw unit volume; and (3) incremental technology adoption (electrification, real-time sensing, optimized consumables) will deliver disproportionate value for operators with large drilling portfolios.
DTH Drill Market
Dynamics Driving Strategic Choices in 2026
-
Productivity-as-Primary KPI: Field benchmarks and vendor claims point to productivity gains that materially change cost-per-meter economics. Optimized hammers and bit designs can enable high hourly footage (industry reports indicate best-practice DTH setups achieving up to 50 meters per hour), while advanced consumables reduce change intervals and air/fuel usage. Executives should reframe procurement conversations around enabled meters per operating hour rather than unit price alone.
-
Energy and Emissions Pressure: Regulatory and corporate sustainability targets are elevating the strategic importance of energy efficiency. Vendors are positioning products with lower air/fuel consumption and improved energy conversion — a trend that translates into both Opex savings and a compliance hedge as emissions accounting becomes more rigorous.
-
Digital & Automation Uptake: Real-time sensing and analytics (for example, systems that deliver vibration and performance telemetry) are shifting DTH from a purely mechanical category into a data-driven service offering. Early adopters extract productivity gains, predictive maintenance benefits, and improved safety outcomes; laggards face increasing aftermarket cost pressures.
-
Supply-Chain and Materials Intensity: Cemented carbide and specialized head geometries remain central to tool performance. Raw-material sourcing and refining bottlenecks can create delivery and margin volatility — an operational risk that should be actively hedged via supplier diversification and recycling/remanufacturing strategies.
-
Consolidation vs. Specialization: The market shows a meaningful concentration among the top players, with a three-firm concentration ratio and a five-firm concentration ratio indicating that leading manufacturers hold a sizable portion of market revenue. That dynamic favors scale players for global contracts and aftermarket coverage but opens niche opportunities for specialized or regional suppliers that can undercut on responsiveness and customization.
What the PW Consulting Report Delivers — Practical, Actionable, Executable
- Proprietary market-sizing model (2020–2032) with scenario sensitivity to energy costs, regulatory tightening, and automation adoption rates.
- Commercial playbooks for OEMs, distributors, and large end-users including pricing architectures, spare-parts inventory strategies, and warranty structures that optimize lifecycle margins.
- CapEx/Opex comparison tools to evaluate internal combustion vs. electric-drive DTH systems under varied fuel and electricity cost regimes.
- Field-level productivity benchmarks and a standardized set of KPIs — meters per hour, bits-per-meter, downtime drivers — enabling apples-to-apples vendor evaluation.
- Supplier due-diligence templates addressing manufacturing footprint, raw-material security, quality assurance, and aftermarket capability.
- Buy-side negotiation playbook and RFP language focusing on guaranteed meters, energy consumption per meter, and digital service level agreements (SLAs).
- Scenario-driven M&A and partnership thesis mapping for strategic entrants seeking bolt-on technologies (e.g., telemetry, remanufacturing) or geographic expansion.
Note: the public preview purposefully omits the full set of regional, type- and application-level tables and the underlying revenue splits. Those critical tables and the interactive model are provided in the full report to registered subscribers.
Competitive Landscape — Who Matters and Why
The DTH landscape blends global OEM scale, regional manufacturing strengths, and focused niche specialists. The market’s top-tier firms — headquartered largely across Sweden, Ireland, Finland, the U.S., China, and Australia — combine deep product portfolios with aftermarket networks and expanding digital capabilities. Below is a strategic snapshot of several influential participants:
-
Sandvik (Stockholm, Sweden): A long-standing engineering leader with a strong portfolio in DTH bits and drilling tools. Recent product introductions include resharpening equipment aimed at extending consumable life and reducing lifecycle cost. Sandvik’s strength is integrated product-service offers and a brand trusted for field reliability.
-
Atlas Copco (Stockholm, Sweden): Known for low-energy hydraulic DTH systems and a broad distribution base, Atlas Copco is leveraging energy-efficiency positioning to win specifications in construction and quarry segments where operating costs are a competitive lever.
-
Epiroc (Stockholm, Sweden): Aggressively pursuing the digital frontier with a DTH Optimizer solution and a new DTH hammer family that emphasizes sensing and real-time optimization. Epiroc’s product+software play is designed to lock in long-term service contracts and generate data-derived aftermarket revenue.
-
Mincon (Naas, Ireland): Focused on consumables and hammer designs optimized for fuel efficiency and penetration rates. Recent catalog refreshes underscore incremental performance improvements that appeal to water-well and geothermal segments.
-
Boart Longyear (Perth, Australia): A traditional exploration and production tools supplier with strong ties to resource-sector customers; their value is deep domain expertise in exploration workflows and global logistical reach.
-
Regional and Niche Players: Rockmore International (Austria), Robit Plc (Finland), Center Rock (USA), and several China-based producers (Drill King, Sinodrills, BD Drill Group) deliver valuable local cost advantages, rapid lead times, and product variations tuned to specific rock types and applications. U.S.-based Infinity Tool MFG supplies industry-standard bit geometries with flexible small-batch capability.
Recent vendor activity in 2025–2025 highlights the twin themes of product evolution and digital enablement: Epiroc’s multi-configuration hammer plus sensing platform; Sandvik’s mid-range resharpening machine; Mincon and Rockmore updating catalogs with performance and efficiency upgrades; and Sinodrills emphasizing low-consumption hammers from their production line. These moves are competitive signals — incumbents are protecting installed bases while newer entrants target efficiency-sensitive subsegments.
Strategic Imperatives for 2026
-
Prioritize Total Cost of Operation (TCO): Replace legacy procurement metrics with TCO models that weigh fuel/energy, consumable lifespan, and downtime. Demand guaranteed performance metrics in contracts (e.g., meters-per-hour performance commitments) and link payments to realized productivity.
-
Invest in Digital Integration: Require telemetry-ready hardware and secure data access clauses in procurement to enable predictive maintenance and performance-based contracting.
-
Hedge Raw-Material Risk: Lock supplier agreements for critical alloys and carbide supply, explore remanufacturing partners, and evaluate in-house reconditioning as a margin lever.
-
Reconfigure Aftermarket Strategy: For OEMs: bundle digital subscriptions with consumables and service; for end-users: regionalize spare kits and centralized analytics to cut downtime.
-
Pursue Focused M&A: Target small to mid-sized technology players (telemetry, bit metallurgy) or regional distributors that can accelerate route-to-market in high-growth corridors.
Execution Checklist — 90-Day Plan for Leadership Teams
- Run a TCO pilot comparing incumbent tools and two alternative vendor solutions across representative rigs.
- Negotiate sample supply contracts that include energy-per-meter and bit-life guarantees.
- Map spare-parts nodes and implement a critical-parts reorder point tied to meters drilled rather than time elapsed.
- Initiate a proof-of-concept with a telemetry vendor to capture drill-vibration and penetration data for a minimum of 30 days.
- Perform a sourcing risk assessment for carbide and specialty alloys and prioritize suppliers for long-term agreements.
Conclusion: The DTH drill market in 2026 is sufficiently mature to reward targeted investments but not so consolidated as to preclude disruptive entry. Scale matters — particularly in aftermarket coverage and digital enablement — but significant opportunities remain for operators that can convert technical gains (lower air/fuel per meter, reduced bit-change frequency) into verifiable commercial outcomes.
Get the Full Intelligence
This preview demonstrates the strategic contours and immediate decision levers. The full PW Consulting DTH Drill Market report contains the withheld regional, type, and application breakdowns, the interactive forecasting model, vendor scorecards, and downloadable RFP templates required to operationalize these recommendations. Access the complete study on our report page to obtain the detailed tables, scenario models, and the actionable annexes that empower confident 2026 capital and procurement decisions.
For detailed analysis of this topic, please visit the official page: DTH Drill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com