

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Treatment Equipment Market to Expand at 6.2% CAGR (2026-2032)

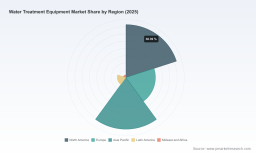
Water Treatment Equipment Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a forward-looking synthesis of the Water Treatment Equipment market designed to influence executive decisions in 2026. Built on a base-year assessment for 2025 and a robust time series across 2020–2025, our view projects the sector through 2032 at a compound annual growth rate (CAGR) of 6.2%. The market has expanded markedly over the past half-decade and is expected to approach the high‑double‑digit billions (USD, revenue unit: Billion) by the end of the forecast window. This briefing highlights the structural drivers, competitive dynamics, risk vectors, and practical actions that matter for procurement, investment, and M&A in 2026 — while intentionally withholding the granular segment and regional line‑items that are reserved for the full report.
Water Treatment Equipment Market
Why 2026 Is a Strategic Inflection Point
-
Policy and capital alignment: Public financing frameworks and renewed regulatory emphasis on conservation are converging with heightened public spending on clean water infrastructure. This alignment reduces funding uncertainty and accelerates opportunities for equipment upgrades, retrofits, and new-build projects across municipal and industrial end-markets.
Water Treatment Equipment Market -
Energy and cost pressure: Water and wastewater treatment remain energy‑intensive activities. The combination of utility cost pressure and corporate sustainability targets is forcing operators to prioritize energy-efficient process equipment, smarter controls, and performance-based O&M arrangements.
Water Treatment Equipment Market -
Technology stacking: Innovations in membranes, disinfection, AI-driven pump management, and modular zero-liquid-discharge (ZLD) systems are shifting buyer economics — moving capital allocation from one-off CAPEX purchases toward integrated solutions that deliver lifecycle OPEX savings.
-
Fragmented supplier base: The market rewards scale in technology development and after‑sales reach but also offers openings for specialist vendors with demonstrable lifecycle economics. Expect both horizontal consolidation and vertical partnerships in 2026–2028.
Market Trajectory (Headline View)
From 2020 through the 2025 base year, the market experienced sustained expansion driven by regulatory compliance projects, industrial water reuse initiatives, and municipal replacement cycles. With a 6.2% CAGR through 2032, the trajectory is clear: demand will keep rising, but the nature of demand is changing — more retrofit projects, greater appetite for modular systems, and an increasing share of purchases tied to services and digital performance guarantees rather than equipment alone.
Practical, Actionable Contents of the Full Report
-
Market sizing and scenario modelling: Transparent methodology with base/bull/bear scenarios, sensitivity testing around energy prices, regulatory tightening, and capital availability.
-
Technology and procurement playbooks: Comparative TCO models for membranes, filtration, UV/chemical disinfection, pumps, and ZLD; recommended procurement structures including availability-based contracting and pay-for-performance clauses.
-
Supplier benchmarking: Qualitative and quantitative scorecards covering technology readiness, service footprint, digital platform maturity, balance-sheet strength, and OEM‑to‑distributor channel economics.
-
Go‑to‑market strategies: Segmented commercial approaches for municipal utilities, heavy industry (chemical, power, mining), food & beverage, and residential/commercial retrofit channels.
-
Regulatory & funding map: Crosswalk of major funding mechanisms, permitting trends, and compliance timelines that materially affect project pipelines and procurement windows.
-
M&A and partnership playbook: Target archetypes, valuation drivers, integration risks, and a checklist for diligence focused on service contracts and digital telemetry assets.
-
Risk register and mitigation: Supply‑chain stress scenarios (critical materials, logistics), cybersecurity controls for digital assets, and contingency plans for rapid policy shifts.
Competitive Landscape — Where Advantage Will Be Won
The competitive map is characterized by three broad supplier archetypes: global systems integrators with full‑service water portfolios; component and chemical specialists; and agile niche innovators focused on a single technology or service model. Leading companies span these archetypes and display differentiated propositions:
-
Systems & services integrators (e.g., Veolia, SUEZ, Evoqua): Strengths lie in end‑to‑end project execution, O&M contracts, and cross-border project financing. Their advantage is in converting large infrastructure programs into multi‑year revenue streams.
-
Technology & chemical leaders (e.g., The Dow Chemical Company, Ecolab, Calgon Carbon): Competitive moats emerge from proprietary chemistries, advanced media, and dosing/control platforms that deliver measurable reductions in chemical and energy consumption.
-
Equipment and digital innovators (e.g., Xylem, Grundfos, Pentair): These suppliers combine hardware excellence with digital monitoring and optimization platforms that lower lifetime costs and create upsell paths into services.
-
Regional OEMs and full-service distributors (e.g., Aquatech, Kurita, Newater, VESSCO, ALAR, Water Treatment Supply): They win where customization, speed-to-delivery, and local compliance knowledge are decisive — particularly in industrial applications.
Across these groups, market winners in 2026 will be those that can shift buyer focus from cheapest initial CAPEX to guaranteed lifecycle performance. Partnerships between chemical houses, membrane manufacturers, and digital platform providers will accelerate; likewise, modular ZLD and decentralized purification variants create entry points for agile specialists.
Recent Developments to Watch (Strategic Implications)
-
Next‑gen UV and disinfection systems with smarter control stacks reduce energy and chemical needs — making retrofits attractive for mid‑life municipal plants that face operating‑cost scrutiny.
-
Intelligent pump systems incorporating AI can unlock 10–20% energy savings at scale, changing the business case for replacing legacy pumping inventories in treatment trains.
-
Modular ZLD solutions lower entry barriers for industrial operators targeting zero discharge, creating prospective demand that favors suppliers offering scalable, factory‑assembled modules.
-
Advanced whole‑house and point‑of‑use membrane technologies expand the residential and commercial retrofit market, but they also commoditize some traditional mid‑market channels.
Strategic Recommendations for 2026 Decision-Makers
-
Reframe procurement KPIs: Shift from equipment price to three‑year and five‑year TCO and guaranteed outcomes. Insist on telemetry and performance SLAs tied to payments.
-
Prioritize modularity and retrofitability: Capex‑constrained operators should prioritize equipment that reduces downtime during installation and can be scaled incrementally.
-
Invest in partnerships, not only acquisitions: Fast followers can secure access to advanced membranes, ZLD modules, or digital control platforms through JV and licensing models rather than full M&A.
-
Design for energy: All procurement decisions must be evaluated against energy intensity targets. Digital pump optimization and advanced disinfection platforms will produce the quickest measurable wins.
-
Lock service economics: For vendors, compress the sales cycle by offering bundled O&M and remote monitoring. For buyers, convert uncertain OPEX into predictable service contracts.
-
Prepare for regulatory acceleration: Build a regulatory scenario playbook — faster compliance timelines materially change capex scheduling and funding applications.
Risk & Opportunity Matrix
Key risks include supply‑chain disruption for critical membranes and electronic components, sudden regulatory shifts in regional jurisdictions, and cyber risks tied to increased digitization. Conversely, opportunities exist in retrofits financed by public funds, decarbonization-linked incentives, and cross‑sector reuse projects (e.g., industrial symbiosis and potable reuse). The full report contains quantified scenario impacts on project pipelines and vendor revenues, enabling prioritized action plans for each risk bucket.
What the Full PW Consulting Report Unlocks
This preview is deliberately high‑level to underline strategic direction and to guide 2026 decision priorities. The complete Water Treatment Equipment Market study provides the missing granular intelligence that executives, investors, and procurement teams need to act decisively: detailed segment and regional breakdowns, vendor scorecards with commercial playbooks, project-level case studies, bid templates, margin benchmarks, and an M&A target shortlist refined by fit‑for‑scale criteria. For teams that must translate strategy into contracts, the delivered toolkits include RFP language, SLA templates tied to performance telemetry, and rollout sequences optimized for capital availability.
PW Consulting’s approach blends market economics, engineering realism, and commercial pragmatism. In an industry where capital choices made in 2026 determine operational cost curves for decades, our guidance helps you prioritize the initiatives that protect EBITDA, reduce regulatory exposure, and deliver sustainable water outcomes.
Next Steps
-
Request the full report to access the data tables, segment-level forecasts, and vendor financial overlays that underpin the strategic recommendations summarized here.
-
Engage our advisory team for a short diagnostic workshop: we’ll map your asset base to the report’s opportunity heatmaps and produce a 90‑day decision agenda.
For detailed analysis of this topic, please visit the official page: Water Treatment Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com