

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydraulic Dock Leveler Market to Reach USD 2,707.08M by 2032 (6.5% CAGR)

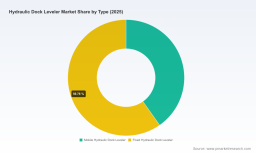
Hydraulic Dock Leveler Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present an executive introduction to our Hydraulic Dock Leveler Market study — a focused, decision-grade resource designed to shape capital allocation, product strategy, and commercial execution in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the market is modeled with a compound annual growth rate (CAGR) of 6.5%. The market demonstrated steady expansion from approximately 1.36 billion USD in 2020 to 1.75 billion USD in 2025, and our forecast sees that trajectory continuing toward an estimated 2.71 billion USD by 2032. These macro dynamics frame the opportunity set and the risks that executives must manage in the next 18 months and beyond.
Hydraulic Dock Leveler Market
Why this study matters for 2026 decisions
-
Timing capital expenditure: With market growth in the mid-single digits (6.5% CAGR), firms must choose whether to accelerate investment in new manufacturing capacity, prioritize product upgrades, or exploit aftermarket and retrofit channels. Each choice has different payback horizons against the forecast growth path.
Hydraulic Dock Leveler Market -
Product and regulatory compliance: The dock leveler product set is being reshaped by safety and performance standards. Adoption of ANSI MH30.1-2022 / MH30.2-2022 across North American projects is driving specification changes — from structural testing regimes to documentation and warranty expectations.
Hydraulic Dock Leveler Market -
M&A and partnership screening: A moderately concentrated vendor landscape creates opportunities for bolt-on acquisitions, distribution partnerships, and strategic alliances focused on controls, hydraulics, and service networks.
-
Aftermarket economics: As installations age and uptime demands rise, aftermarket services, retrofit kits, and predictive maintenance provide attractive margin pools relative to new-unit sales.
Market dynamics — drivers, constraints & inflection points
-
Demand drivers: E-commerce and omni-channel fulfillment continue to expand demand for optimized loading/unloading infrastructure. Warehouse modernization programs, renovation cycles in distribution networks, and investments in heavy-industrial terminals all underpin steady unit demand and upgrade cycles.
-
Standards and safety: Recent standardization efforts (notably ANSI MH30.1-2022 and MH30.2-2022) are converting best-practice features into procurement requirements. For product teams and tender managers, ANSI certification increasingly predicts specification wins and reduces vendor risk in institutional procurement.
-
Product performance envelope: Hydraulic designs now routinely span broad capacity ranges, with certain industry-grade models engineered for very high load ratings. This range is important for OEMs targeting heavy-industrial end markets where durability, interlock compatibility, and low life‑cycle cost are paramount.
-
Serviceability & control systems: Reduced-maintenance architectures and resilient control stations (e.g., corrosion- and moisture-resistant enclosures) are becoming differentiators — influencing lifecycle operating costs and total cost of ownership calculations.
-
Supply-side constraints: Raw-material volatility and component sourcing (hydraulic cylinders, valves, electrical controls) continue to create scheduling and cost pressures that favor vertically integrated suppliers or those with diversified supply chains.
Competitive landscape — what the leading players signal
The competitive field blends long-established industrial players with focused dock-equipment specialists. Market concentration metrics indicate room for differentiation and consolidation: the top three firms do not monopolize the market, and even the top five leave substantial share for regional champions and niche specialists. Below is a distilled view of strategic postures and capabilities among the core vendors we benchmarked.
-
Overhead Door Corporation — Leans into certified, specification-driven product launches. Recent introductions with ANSI certification and extended warranty positioning indicate a strategy targeting institutional buyers and specification-heavy accounts where compliance and reduced procurement risk matter most.
-
Poweramp (Systems, LLC) — Emphasizes operational simplicity and vertical storing configurations that appeal where workplace ergonomics and bay density are important. Their push-button and high CIR features reflect a customer focus on throughput and operator ease.
-
DLM (Systems, LLC) — Maintains a balanced product portfolio for pit and edge-of-dock needs. Their emphasis is on adaptable platforms that can be configured by OEMs or distributors for heterogeneous fleet requirements.
-
Rite-Hite Corporation — Differentiates on integrated systems thinking (e.g., Smooth Transition Dok System®), positioning dock levelers as part of a broader site-level material handling solution rather than as standalone units.
-
Pentalift Equipment Corporation — Known for high-capacity, low-maintenance designs aimed at heavy-industrial applications. Their engineering emphasis on high-rating units maps to customers prioritizing life-cycle robustness over initial purchase price.
-
Nordock Inc. — Focuses on designs that reduce downtime and maintenance burden, marketing push-button simplicity and reliable edge-of-dock options for high-turnover facilities.
-
McGuire Manufacturing Co. — Highlights structural durability and low lifetime ownership cost, making them a contender in total-cost-of-ownership conversations during procurement.
-
Blue Giant Equipment Company — Competes on durability and environmental resistance, including corrosion-resistant controls and NEMA-rated solutions for demanding ambient conditions.
Implications for product strategy and commercial models
-
Design for specifications: With standards becoming procurement gatekeepers, incorporating certification pathways into new-product timelines reduces time-to-spec and accelerates adoption by institutional buyers.
-
Service-first go-to-market: Build margin-rich service offerings — aftermarket parts kits, preventive maintenance subscriptions, and retrofit packages — to leverage installed base growth and extend revenue visibility.
-
Modularization and configurable platforms: Create scalable product platforms that allow flexible configurations by capacity, control type, and environmental protection to shorten lead times and support localized value propositions.
-
Controls and connectivity: Investing in durable control enclosures and basic telematics (for usage and fault reporting) can unlock premium positioning in operations-sensitive accounts without requiring heavy R&D investment.
Operational and supply-chain considerations
Boards and COOs must weigh near-term market growth against potential bottlenecks in hydraulics components and corrosion-resistant electrical enclosures. Strategies that mitigate risk include multi-sourcing, near-shore assembly for key markets, and inventory hedging for critical subcomponents. OEMs that simplify installation and reduce field-service frequency will gain an advantage as labor costs and technician availability remain constrained across core logistics markets.
What the full report delivers (practical content for 2026 execution)
-
Methodology: Transparent forecasting model with scenario analysis across demand, pricing, and supply disruptions.
-
Market sizing & macro trends: Historical base (2020–2025), 2025 benchmarking, and an industry-grade forecast to 2032 with an explicit 6.5% CAGR baseline.
-
Segmentation framework: Multi-dimensional splits by product architecture, application type, and geography with demand drivers and adoption curves (note: detailed segment tables and downloadable excel workbooks are included in the full report).
-
Vendor benchmarking: Comparative scorecards across engineering capability, product depth, distribution reach, after-sales capacity, and R&D roadmap.
-
Regulatory & standards mapping: Impact analysis of ANSI MH30.1/MH30.2 and implications for procurement language and warranty design.
-
Supply-chain stress tests: Component concentration analysis, lead-time sensitivity, and mitigation playbooks.
-
Commercial playbooks: Pricing tactics, bundling of service and retrofit offerings, and tender-response templates to win specification-driven projects.
-
M&A and partnership screen: Deal targets and integration considerations keyed to growth and margin objectives.
Top-line strategic recommendations for 2026
-
Prioritize ANSI-compliant product lines for institutional channels to speed specification approvals and reduce procurement friction.
-
Scale aftermarket and retrofit capabilities to monetize the installed base — focus on preventive maintenance, control-enclosure upgrades, and capacity retrofits where lifecycle economics are compelling.
-
Pursue selective vertical integration or strategic supplier agreements for hydraulics and control hardware to reduce lead-time exposure.
-
Differentiate on serviceability: simplify field maintenance, provide clear documentation for facility teams, and offer predictable SLAs to win long-term contracts.
-
Use targeted M&A to acquire distribution reach or niche engineering IP in environmental-protected controls or high-capacity designs.
Concluding perspective
The hydraulic dock leveler market presents a reliably growing, technically nuanced opportunity for companies that can align product engineering with emerging standards, operational reliability, and aftermarket service economics. With a mid-single-digit CAGR and a clear trajectory from the 2025 base year, 2026 is a year for tactical moves: lock in compliance-based product offerings, bolster aftermarket revenue streams, and shore up supply chains to convert forecasted demand into predictable, profitable growth.
For detailed segment tables, vendor share models, downloadable forecast workbooks, and tactical implementation templates, refer to the full PW Consulting report. The dataset and appendices contain the granular numbers and decision tools necessary to operationalize the strategic recommendations outlined above.
For detailed analysis of this topic, please visit the official page: Hydraulic Dock Leveler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com