

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EVSE market to reach USD 1,079M by 2032, expanding at a 29.1% CAGR

EVSE Market Outlook 2026: Strategic Imperatives for Corporate Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking executive orientation to our latest Electric Vehicle Service Equipment (EVSE) Market study. This briefing is designed to translate the research’s quantitative backbone into the practical, decision-ready intelligence executives need in 2026—without giving away the full segmentation tables and proprietary scorecards included in the full report. Consider this a high-fidelity preview: substantive, diagnostic, and strategically prescriptive—yet intentionally incomplete to encourage a site visit for the full dataset and tools.
Electric Vehicle Service Equipment (EVSE) Market
Why 2026 Is the Inflection Point
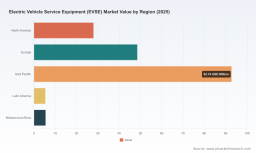
The EVSE market is shifting from pilot-phase deployments to commercial-scale rollouts. Our model—anchored on a 2025 base year and projecting through 2032—shows a compound annual growth rate (CAGR) of 29.1% across the 2026–2032 forecast window. In concrete terms, the market expands from an estimated USD 180 Million in 2025 to more than USD 1,079 Million by 2032, with an intermediate jump to around USD 228.7 Million in 2026. That pace is not mere hype: it signals compressed timelines for ROI, accelerated supplier selection cycles, and materially different capex/opex profiles for projects initiated in 2026 versus those delayed a year or two.
Electric Vehicle Service Equipment (EVSE) Market
What This Research Delivers—Practical, Actionable, and Operational
-
High-resolution demand and supply model: a calibrated market-size baseline, validated growth drivers, and scenario runs that stress-test adoption curves under different regulatory and technology trajectories.
Electric Vehicle Service Equipment (EVSE) Market -
Deployment playbooks: site assessment checklists, electrical upgrade matrices, and installation labor-cost frameworks ready to be adapted to enterprise procurement cycles.
-
Financial tools: project-level TCO and payback models, procurement contract templates, and sensitivity analyses for energy tariffs, demand charges, and utilization profiles.
-
Vendor benchmarking and commercial scorecards: qualitative and quantitative assessments of market leaders, challenger offerings, and emerging platforms—presented to support shortlists and RFPs.
-
Standards and compliance map: a living register of certification requirements, product safety standards, and regional procurement constraints (with integration guidance for compliance workflows).
-
Execution roadmaps: 90/180/365-day action plans to move from strategy to pilot to scale—covering technology, financing, operations, and stakeholder communications.
Key Strategic Takeaways for 2026 Decision-Makers
-
Act to lock in technology-platform advantages now. With near-term market growth accelerating, early procurement choices and trial partnerships will shape unit economics and partner ecosystems for years. The difference between “early adopter” and “legacy integrator” will often be decided by 2026 deployment velocity.
-
Design procurement to manage standards and localization risk. Regulatory moves—especially those touching domestic sourcing requirements and certification regimes—mean procurement teams should include compliance gates and alternate-sourcing clauses in contracts.
-
Optimize for site-level utilization, not just unit cost. Rising utilization will make the economics of faster charging, managed load control, and smart metering more attractive; conversely, incorrect mix choices can extend payback timelines even as the market grows rapidly.
-
Prioritize interoperability and future-proofing. Connector standards, software APIs, and bidirectional capabilities are converging into the most durable competitive advantages. Suppliers with flexible upgrade pathways reduce stranded-asset risk.
-
Prepare for consolidation pressure and partnership-led growth. Market concentration metrics indicate a fragmented landscape with scope for consolidation and strategic alliances—smart acquirers and incumbent alliances will capture distribution and scale advantages in the coming 18–36 months.
Competitive Landscape: Who Matters and Why
The vendor environment is diverse: established electrical and industrial players, specialist fast-charger manufacturers, network operators, and standards/validation institutions all have consequential roles. A few exemplars and their strategic implications:
-
ChargePoint — A platform-first supplier with breadth across residential, commercial, and fast-charging offerings. Recent product launches that embed driver management and reimbursement workflows highlight a strategy to capture fleet and corporate mobility budgets as much as hardware spend. Expect ChargePoint to double down on software-led monetization and enterprise integrations.
-
Eaton (partnering with ChargePoint) — Using joint offerings to push into ultrafast DC and integrated power management demonstrates an industrial-playbook approach: combine distribution, electrical hardware, and systems integration to address grid-constraint projects and large-scale commercial deployments.
-
Tritium — Focused on scalable DC fast charging platforms, the vendor’s modular TRI-FLEX architecture is tailored for commercial and fleet rollouts. For corporations building depot or corridor charging, modular scalability is a major operational advantage.
-
ABB — Targeting megawatt-scale and high-duty-cycle requirements, its product families are positioned for heavy-duty vehicle charging and industrial use-cases where uptime and power density matter most.
-
Siemens — Offering connected charging hardware with enterprise-grade metering and grid features, Siemens is a logical partner where integration with building energy management and utility-scale projects is required.
-
EVgo — An operator-first player expanding connector compatibility and network footprint. Their strategy points to expansion via on-network growth and interoperability bets that can shape charging network economics.
-
EPRI — As the curator of vetted product lists and utility-facing validation, EPRI’s role is pivotal for suppliers and buyers seeking utility approval and long-term operational credibility.
Each of these profiles maps to specific strategic choices: partner versus vendor, software-first versus hardware-first, or operator versus supplier models. The detailed vendor scorecards in the full report provide procurement teams with the comparative criteria and weighted scoring recommended for 2026 RFPs.
Regulatory and Standards Dynamics: Tailwinds and Risks
Several regulatory and standards developments are actively reshaping procurement and deployment risk in 2026:
-
Procurement localization rules and waiver reviews are increasing the cost of global sourcing for EVSE. This changes supplier selection dynamics for projects that rely on federally funded or public right-of-way installations.
-
Updates to measurement and metering directives create a requirement regime that intersects with revenue-quality metering in public charging—projects without compliant metering may face remedial costs and delayed revenue recognition.
-
Standardization and safety certifications, including recent updates urging UL-certified adapters and accessories, make certification diligence non-negotiable—buyers should require documented evidence of standard compliance during technical evaluation phases.
-
Regional rebate and grant programs targeting residential and commercial deployments materially change the investment calculus for certain projects—our report identifies how program design influences vendor economics and customer acquisition strategies.
From Insight to Action: 90/180/365 Day Roadmaps
-
90 days: Run a sourcing health-check and standards compliance audit for planned 2026 projects; assemble a two-vendor shortlist per use-case; deploy a proof-of-concept at a single high-utilization site using one modular DC fast charger or managed AC station.
-
180 days: Execute pilots with full telemetry and meter-integration, negotiate master services agreements with performance SLAs, and begin permitting and grid-connection negotiations informed by the report’s utility-engagement playbook.
-
365 days: Scale procurement using standardized contracts, operational processes, and a supplier governance model; evaluate strategic partnership or acquisition opportunities informed by competitive concentration and vendor roadmaps.
Why PW Consulting’s EVSE Market Study Matters for Your 2026 Planning
Decisions made in 2026 will disproportionately affect cost structures and strategic positioning across the next business cycle. Our report combines a detailed market model (with base-year 2025 calibration), practical implementation toolkits, and vendor-level intelligence to help executives move from impulsive procurement to deliberate market capture. The macro trajectory—a strong double-digit CAGR and a market expanding by multiple times through 2032—creates both huge upside and significant execution risk. The difference between capturing value and becoming a reactionary buyer will be judged by the quality of your procurement playbook, your standards/compliance posture, and the speed of your pilot-to-scale pathway.
For those ready to translate this preview into an executable plan, the full study contains the granular segmentation matrices, regional and application-level forecasts, downloadable financial models, and vendor scorecards that operational teams require. Visit our report page to access the complete dataset, templates, and a companion webinar where our analysts walk through the model assumptions and scenario outcomes live.
For detailed analysis of this topic, please visit the official page: Electric Vehicle Service Equipment (EVSE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com