

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: AC CT Market to Reach USD 356.3M by 2032 at 4.5% CAGR

AC Current Transformers for Electrical Meters: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a high-conviction, action-oriented primer on the AC current transformer (CT) market for electrical meters — a compact, technically nuanced segment whose near-term behaviour will exert outsized influence on metering accuracy, smart-grid deployments, and utility capex strategies in 2026. This preview distills the macro trajectory, the competitive map, regulatory inflections, and pragmatic, scenario-based guidance executives need to prioritize investments and procurement decisions this year. It deliberately highlights analytical depth while preserving proprietary segment-level detail — think of this as the trailer that proves we understand the movie, and points you to the ticket counter for the full screening.
AC Current Transformers (CT) for Electrical Meters Market
Why this market matters to corporate strategy in 2026
-
Revenue-grade metering and the expanding smart-meter base are elevating the role of CTs from passive components to mission-critical accuracy enablers. For utilities, meter manufacturers, and system integrators, CT selection now directly affects billing integrity, regulatory compliance, and lifetime O&M costs.
AC Current Transformers (CT) for Electrical Meters Market -
Hardware choices made in 2026 — for new installations, retrofits, or supplier consolidation — will cascade through product roadmaps and supply chains for the next 5–7 years. Decisions on core technologies (nanocrystalline cores vs. traditional materials), form factors (split-core, solid-core, Rogowski), and supplier risk management are therefore strategic, not tactical.
AC Current Transformers (CT) for Electrical Meters Market -
Regulatory updates and interoperability requirements emerging this year increase the cost of late compliance; early alignment will produce competitive differentiation through faster time-to-market and fewer field interventions.
Market trajectory: the headline numbers you should anchor to
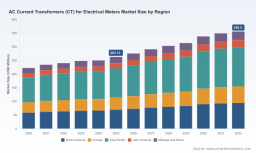
At a macro level, the AC CT market for electrical meters is on a steady growth path. Using 2025 as the base year, our market model places total industry revenue at approximately USD 263.13 Million that year. Under the central scenario (which incorporates measured smart-meter rollouts, steady industrial modernization, and incremental upgrades), we project a compound annual growth rate (CAGR) of about 4.5% across the 2026–2032 forecast window. That trajectory implies a market that rises to roughly USD 356.3 Million by 2032, with intermediate annual expansion that buyers and suppliers should anticipate when sizing production runs and negotiating multi‑year supply agreements.
Two implications flow directly from these figures: first, aggregate demand is robust enough to justify incremental capacity investments and targeted supply-chain partnerships in 2026; second, the growth rate is not hyperbolic, which places a premium on operational efficiency, product differentiation, and targeted segmentation to capture above-market returns.
Dynamics reshaping the competitive and regulatory landscape
-
Standards and certification cycles: The publication of ANSI C12.1-2026 and related updates has tightened performance expectations for revenue meters and their auxiliary components, including CTs. The standard’s amendments — such as clarified test protocols for radio-frequency immunity — increase testing complexity for meter assemblies and shift procurement emphasis toward CT vendors who can demonstrate rigorous, testable compliance.
-
Government and utility programs: Regulatory momentum in several large markets is aligning incentives and technical requirements to accelerate smart-meter rollouts. Proposed amendments (for example, from authorities focused on improved billing accuracy) create near-term tender opportunities but also require suppliers to be pre-qualified on tighter specs.
-
Technology and materials: Advances in core materials (nanocrystalline alloys, specialized ferrites), alongside alternative sensing technologies (Rogowski coils for high-current installations), are bifurcating the product set between cost-optimized commodity CTs and higher-margin, accuracy-focused devices suited for revenue metering and sensitive grid-edge applications.
-
Manufacturing footprint and supply resilience: Geopolitical and logistics pressures have made dual-sourcing and regional inventory strategies more valuable. Buyers should evaluate supplier capabilities not only by price and specifications, but by demonstrated ability to sustain shipment performance during spikes (e.g., synchronized smart meter tender cycles).
Competitive landscape — who matters and what they bring
The market is commercially diverse: a mix of well-established European precision manufacturers, North American specialists in revenue-grade products, and agile Asian OEMs supplying integrated meter components. Market concentration is moderate; the largest trios do not dominate the market fully, which leaves room for nimble niche players and OEM partnerships.
-
Vacuumschmelze (Hanau, Germany) — Strengths: specialist core materials (nanocrystalline VITROPERM/VITROVAC) and deep experience serving IEC/ANSI markets. Strategic implication: best-in-class for high-accuracy metering projects that require stringent material performance and repeatable certification workstreams.
-
Accuenergy (United States) — Strengths: bespoke, revenue-grade split-core and solid-core CTs tailored for precise power monitoring. Strategic implication: attractive partner for integrators who need configurable CTs and close engineering collaboration for hybrid metering systems.
-
LEM (Switzerland) — Strengths: established AT series and brand recognition in automation and smart-grid segments. Strategic implication: preferred for projects where integration with broader instrument transformer portfolios and long-lived service contracts matter.
-
Phoenix Contact (Germany) — Strengths: solutions for both new installations and retrofitting; product lines that ease field conversion to 1 A or 5 A standards. Strategic implication: strong contender where installers favor products that reduce on-site work and simplify retrofits.
-
Electro-Meters (United States) , Flex-Core (United States) , Oswell E‑Group (China) , GFUVE GROUP (China) , and YTL Meter (China) — Strengths: variously offer product breadth, inventory depth, compact split-core designs, or local market access. Strategic implication: a mix of cost-effective supply options and regional partners for large-scale meter rollouts.
Recent vendor activity underlines two themes: a push for product and technical leadership (for example, technical guides and whitepapers that reduce field risk), and the bundling of CTs into multifunction metering solutions. Notable developments include technical guidance releases that clarify CT performance expectations in smart-meter assemblies and the launch of multifunction power meters that integrate high-precision CTs. These moves reflect suppliers’ intent to capture more value across the metering stack, and they change procurement calculus: buying a CT in isolation versus buying a CT as part of an instrumented metering system yields different cost and risk profiles.
What our full report delivers (practical, executable content)
Our AC CT market study is built for decision-makers who need to translate market dynamics into operational plans in 2026. Highlights include:
-
Proprietary market model with historical calibration (2020–2025) and scenario-based forecasts across 2026–2032, enabling stress-testing of procurement strategies against low/central/high adoption pathways.
-
Supplier scorecards that benchmark technical performance (accuracy classes, material technologies, form factors), manufacturing capacity, lead-time reliability, and certification readiness — presented to facilitate RFP shortlisting.
-
Regulatory impact maps showing where standards changes materially affect product specifications and test requirements, and a compliance playbook for vendors and buyers alike.
-
Procurement playbooks and contract templates that address common pitfalls in volume commitments, warranty claims, and field-recall liabilities specific to CTs used in revenue metering.
-
Case studies and field-evidence on metering performance outcomes across residential, commercial, and industrial deployments — with practical checklists to reduce smart-metering production delays attributable to CT selection.
Note: while this introduction synthesizes the market’s macro trends and competitive dynamics, the report contains detailed segment-level breakdowns, supplier rankings, and price benchmarks that we intentionally withhold here — these are the core intelligence that the full report delivers to subscribers.
Strategic recommendations for 2026 (actionable, prioritized)
-
Segment your 2026 procurement into three tracks: (1) high‑accuracy projects requiring premium CTs; (2) mass-deployment rollouts where unit cost and lead time matter most; and (3) retrofit/field-replacement inventory for rapid-response deployments. Allocate R&D or supplier-development budgets accordingly.
-
Pre-qualify two complementary suppliers per procurement track to mitigate single-supplier risk, emphasizing documented compliance with ANSI C12.1-2026 and equivalent regional standards.
-
Require test-report packages and a limited pilot run before mass procurement. Our field analysis shows that early pilot feedback on CT integration materially reduces production delays in meter manufacturing and commissioning.
-
Embed performance‑based contract clauses tied to accuracy consistency and lifecycle warranty to align supplier incentives with in-service meter performance.
-
Invest in supplier co-engineering where new materials or form factors are being deployed; a small upfront engineering commitment can unlock lower unit cost and fewer field interventions over the product lifecycle.
Concluding perspective and next step
The AC current transformer market for electrical meters in 2026 is neither a high-velocity breakout nor a flat commodity arena; it is a measured-growth market where technical differentiation, regulatory alignment, and supply-chain resilience determine who captures the premium. With a base-year revenue near USD 263.13 Million and a central CAGR of approximately 4.5% through 2032 (to roughly USD 356.3 Million), the opportunity is clear — but so is the need for disciplined, data‑driven supplier and product strategies.
PW Consulting’s full report contains the quantitative segment breakdowns, supplier scorecards, price benchmarks, and procurement templates you need to move from strategy to execution this year. For clients preparing 2026 capex plans, RFPs, or supplier consolidation programs, the report reduces execution risk and shortens time-to-compliance.
To obtain the full dataset, supplier rankings, and practical annexes referenced above, please visit our report page or contact your PW Consulting representative. The executive summary you have here provides the why and the what; the full report provides the how.
For detailed analysis of this topic, please visit the official page: AC Current Transformers (CT) for Electrical Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com