

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Saccharin Market Poised for USD 456M by 2032 at 7.84% CAGR

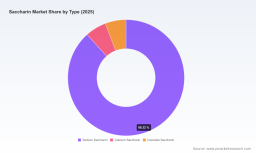
Saccharin Market — Strategic Outlook for 2026 (PW Consulting)
As companies set priorities for 2026, understanding the commercial dynamics of high-intensity sweeteners has become a board‑level imperative. PW Consulting’s latest Saccharin Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes primary supplier intelligence, regulatory developments and scenario-driven demand modeling into an operationally focused playbook. The market stood at approximately USD 272 Million in 2025 and is projected to grow to roughly USD 456 Million by 2032, reflecting a compound annual growth rate of 7.84% across the forecast window. This introduction outlines why that trajectory matters, what strategic choices it forces on industry participants in 2026, and where the report adds immediate, actionable value — while intentionally withholding detailed segment-level figures to protect the report’s proprietary granularity and guide readers to the source for full access.
Saccharin Market
Why this report matters for 2026 decision-making
-
Timing: The sector is transitioning from steady replacement demand toward differentiated growth driven by product reformulation in food & beverage, expanded pharmaceutical use-cases and niche personal-care formulations. The growth profile through 2032 validates near-term capacity planning decisions.
Saccharin Market -
Margin pressure and cost arbitrage: Structural cost advantages in certain geographies are compressing global margins for commodity saccharin, while premiumisation (high‑purity grades, certified food‑grade and pharma‑grade streams) opens routes to margin recovery.
Saccharin Market -
Regulatory stability — with conditional caveats: Longstanding regulatory frameworks remain in force, but evolving compliance requirements (REACH, food additive authorizations and local import HS code enforcement) are shifting compliance cost lines for cross‑border supply chains.
-
Fragmented supply base: The market is not concentrated in a handful of dominant global incumbents; instead, a broad supplier ecosystem (from large-scale producers to specialty high‑purity houses) creates win paths for both scale and niche strategies.
What our full report delivers (practical, deal‑ready content)
-
Verified market sizing and growth scenarios: granular total addressable market modelling by demand tier with transparent assumptions (historical validation, consumption drivers and price elasticity ranges).
-
Demand-supply mapping: supplier capacity overlays, utilization scenarios and export flow analysis to identify potential bottlenecks and strategic sourcing locations.
-
Cost-to-serve and margin decomposition: unit cost modeling (raw materials, energy, logistics, compliance) and sensitivity runs to detect margin inflection points under alternative feedstock and freight scenarios.
-
Regulatory risk matrix and compliance playbook: impact assessments for major jurisdictions and a checklist for REACH, FDA and EFSA compliance pathways together with typical timelines and cost ranges for certification.
-
Commercial playbooks for buyers and sellers: contracting templates, quality acceptance protocols, dual-sourcing strategies and sample testing regimens designed for 2026 procurement cycles.
-
M&A and partnership pipeline: candidate screening criteria, valuation anchors for specialty vs commodity assets and integration risk checklists for private equity and strategic buyers.
-
Scenario planning suite: three vetted scenarios (baseline, accelerated adoption, regulatory tightening) with P&L and working capital impacts for immediate deployment in 2026 planning cycles.
Competitive landscape: profiles and strategic implications
The saccharin supply chain comprises multiple archetypes — large-volume commodity producers with backward integration, regional specialists focused on cost-efficient exports, and small, high‑purity producers serving regulated end‑markets. Our competitive analysis profiles each archetype and highlights near‑term strategic moves to watch in 2026.
-
Large-scale commodity producers (China and select EM manufacturers): These players leverage scale, integrated raw-material sourcing and cost advantages to serve global food and industrial channels. Their ISO and food‑safety certifications enable broad export footprints; market entrants and buyers should expect competitive pricing discipline and fast order fulfillment where logistics are optimized.
-
Back‑integrated Indian manufacturers: Some manufacturers combine in‑country raw material sourcing with sizable annual production capability. This reduces exposure to overseas feedstock shocks and supports competitive export pricing, particularly into regional pharma and feed markets.
-
High‑purity and specialty producers (Korea, select EU/US suppliers): These vendors focus on the upper end of the value chain — pharmaceutical and specialized food applications — and command pricing premia tied to traceability, certifications and production controls. For buyers requiring documented safety histories and formulation stability, these suppliers mitigate regulatory and reputational risk.
-
Laboratory and niche distributors: US-based and regional distributors provide just-in-time small-batch supplies and regulatory documentation for R&D and niche applications; their strategic value lies in enabling rapid product development without the overhead of direct supplier qualification.
Recent market developments reinforce these dynamics: in 2025, we tracked launches of new sodium saccharin formulations targeted at food and beverage reformulation and recognition awards for long-established high‑purity producers — signals of both product innovation and brand positioning that matter for premium channels.
Regulation, trade and supply‑chain realities shaping 2026
-
Regulatory foundations: The additive remains subject to long-established food‑additive frameworks in major markets; regulators continue periodic reassessment rather than wholesale bans, which supports continued commercial use but increases the importance of documented safety dossiers and supply‑chain traceability.
-
EU REACH and trade codes: Compliance requirements tied to import classifications and REACH obligations are materially affecting sourcing decisions for companies that sell into European markets — non‑compliance risks can translate into shipment delays and costly remediation.
-
Feedstock and regional cost bases: Readily available raw materials in certain countries underpin persistent cost advantages and have driven capacity expansion. Buyers should model supplier landed costs inclusive of tariffs, compliance spend and freight volatility to understand true unit economics.
Strategic choices for 2026 — recommended actions by stakeholder
-
Manufacturers: Prioritize a two‑track strategy — defend commodity volumes through scale and cost management while investing in a premium stream (pharma‑grade, certified food ingredients). Consider selective capex to improve flexibility (reactors, filtration, certification processes) and pursue backward integration where feedstock volatility is material.
-
Buyers (F&B, pharma, personal care): Implement dual‑sourcing and supplier maturity models; add contractual clauses for traceability and regulatory audit rights. For reformulation initiatives, partner early with high‑purity suppliers to de‑risk shelf‑life and organoleptic outcomes.
-
Investors: Seek platform targets that combine production scale with documented quality pathways. Value accretion is likely where buyers can consolidate fragmented regional capacity, upgrade quality systems and cross‑sell into pharma and specialty markets.
-
Policy and compliance teams: Build REACH readiness and import‑classification checks into 2026 procurement cycles; factor these into landed cost models and supplier selection criteria.
Risk and reward — an executive summary view
Upside drivers include continued reformulation in food and beverages, incremental clinical and OTC pharmaceutical demand and the ability for premium producers to capture value through certification and technical service. Downside risks are concentrated in regulatory shocks, feedstock/energy price volatility and logistics disruptions that could materially affect near‑term margins for commodity suppliers. The interplay between low-cost scale and premium differentiation will determine winners in 2026: companies with flexible supply chains and documented compliance programs will outcompete peers on both price and access to regulated markets.
Immediate takeaways for 2026 planning
-
Recalibrate procurement to reflect true landed costs, not only ex‑works prices; include compliance and logistics as line items in 2026 budgets.
-
For manufacturers, allocate capital to either expand flexible capacity or to up‑grade quality systems — both are defensible in the current growth scenario, but not simultaneously without clear returns.
-
Investors should prioritise targets offering a credible transition path from commodity to specialty segments, or assets that meaningfully consolidate regional supply chains.
-
All stakeholders should lock in vendor audits and certification timelines early; regulatory lead times are non-trivial and can bottleneck commercial plans.
Next steps — how to extract the full strategic value
The summary above highlights the commercial levers and regulatory contours that will shape decisions in 2026. PW Consulting’s full Saccharin Market report contains the granular segmentation, price curves, supplier scorecards, capacity maps and downloadable scenario models required to convert this strategic direction into executable plans (procurement RFP language, M&A diligence packs, capex justification templates). If you are leading procurement, manufacturing strategy or M&A evaluation in this sector, the full dataset and modelling workbench will save weeks of analysis and materially reduce execution risk.
Contact PW Consulting to arrange a briefing, obtain access to the complete report and explore tailored workshops that translate these findings into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Saccharin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com