

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Diagnostic X-Ray Imaging Market to Reach USD 24,029 Million by 2032 (5.6% CAGR)

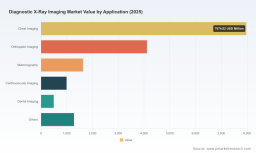
Diagnostic X-Ray Imaging Market: Strategic Imperatives for 2026
As healthcare systems worldwide recalibrate capital allocation, diagnostic throughput, and technology roadmaps following pandemic-era disruptions, the Diagnostic X-Ray Imaging market re-emerges as a high-frequency, durable segment of medical capital expenditure. PW Consulting’s Diagnostic X-Ray Imaging Market Diagnostic X-Ray Imaging Market research frames the decisions 2026 leaders must make — balancing incremental digital upgrades, regulatory compliance, and supply-chain resilience against accelerating clinical demand. This introduction outlines the study’s strategic value for executives preparing budgets, partnerships, and product roadmaps in 2026, while preserving the granular proprietary intelligence available in the full report.
Diagnostic X-Ray Imaging Market
Executive snapshot — market trajectory and structural context
Using 2025 as the analytical base year, our model estimates the global diagnostic X‑ray market at approximately 16.5 billion USD (revenue unit: Million USD). Over the 2026–2032 forecast window, we project compound annual growth of 5.6%, reflecting a combination of replacement cycles in developed markets, capacity expansion in middle-income health systems, and steady adoption of digital radiography and AI-enabled workflow tools. By the end of the forecast horizon the market approaches the mid‑20 billion USD range, underscoring both expansion and consolidation dynamics that will shape procurement, partnerships, and product strategies through the decade.
Diagnostic X-Ray Imaging Market
Market concentration is meaningful but not prohibitive: the three largest vendors together account for under half of global sales, and the five-largest cohort controls a clear majority — a structure that creates windows for focused disruptors and component suppliers to capture value via specialization, services, or channel partnerships.
Diagnostic X-Ray Imaging Market
Why this market matters in 2026 — five practical reasons
- High-frequency utilization: X‑ray remains the backbone of diagnostic workflows across emergent, routine, and chronic-care pathways — driving consistent service volumes and predictable revenue streams for equipment and service models.
- Digital migration unlocks value: The ongoing transition from analog and computed radiography to flat‑panel digital radiography continues to generate replacement demand, workflow efficiency gains, and new service offers (AI-assisted triage, automated QC).
- Regulatory and reimbursement inflection points: Tighter safety standards and evolving reimbursement codes are altering procurement decision trees — favoring vendors who can demonstrate compliance and enable billing optimization.
- Component and supply-chain leverage: Independent suppliers of X‑ray tubes and detectors are strategically important — either as partners for OEMs or as acquisition targets for firms seeking vertical integration and margin control.
- Consolidation and services: As hardware becomes more standardized, aftermarket services, financing, training, and integrated software services are potent differentiators that preserve margins and increase switching costs.
Drivers, headwinds, and regulatory dynamics
Our Diagnostics X‑Ray market model layers quantitative forecasts with qualitative assessments of structural drivers that will influence 2026 decisions:
- Clinical demand and epidemiology: Demographic aging and expanded access in emerging markets sustain steady imaging volumes, while episodic surges (e.g., infectious disease waves or trauma spikes) create short-term procurement needs and rental/device-as-a-service opportunities.
- Technology diffusion: Advances in flat‑panel detectors, mobile DR platforms, and AI for image acquisition/triage improve throughput and lower cost-per-exam — creating a premium tier of technology buyers while opening retrofit and upgrade markets.
- Regulatory environment: New and reinforced standards are shaping product design and market entry. Notably, Part F requirements from radiation oversight authorities and FDA assembly/reporting obligations for diagnostic X‑ray equipment impose documentation, labeling, and installation reporting duties that vendors and assemblers must incorporate into commercial contracts and installation workflows.
- Reimbursement mechanics: Established reimbursement frameworks (public and private) continue to govern adoption pace; firms that synchronize coding, evidence generation, and payer engagement unlock faster uptake.
- Supply-chain dynamics: Competition between OEM in‑house manufacturing and independent suppliers for key components (tubes, flat panels) impacts lead times, pricing, and negotiation leverage — an area where supply‑risk mitigation strategies are increasingly central to procurement teams.
Competitive landscape — who matters and why
The competitive terrain combines global platform vendors, regional specialists, and component suppliers. Our report profiles each tier with commercial metrics, technology roadmaps, and recommended engagement strategies.
- GE HealthCare Technologies Inc. (Chicago, IL, USA) — A leading provider of digital radiography systems, known for advanced flat-panel detectors, mobile units, and integrated imaging solutions. GE’s broad installed base and service networks make it a strategic partner for large health systems seeking end-to-end lifecycle management.
- Siemens Healthineers AG (Erlangen, Germany) — Supplier of integrated DR platforms with deep AI and workflow integration capabilities. Siemens’ recent product introductions emphasize enterprise-level automation and clinical throughput, making it competitive for high-volume hospital environments. (Recent: MULTIX Impact E launch, Jan 2025.)
- Koninklijke Philips N.V. (Amsterdam, Netherlands) — Offers digital radiography platforms with advanced automation and AI-assisted collimation that target workflow efficiency. Philips' strength lies in systems integration and clinical workflow orchestration across imaging modalities.
- Canon Medical Systems Corporation (Otawara, Japan) — Focused on high-image quality DR systems and detector technology; known for robust engineering and clinical image performance in diagnostic settings.
- Fujifilm Healthcare Solutions (Tokyo, Japan / Americas operations in US) — Supplier of glass-free detectors and DR platforms optimized for diagnostic imaging with a strong presence in retrofit and upgrade segments.
- Varex Imaging Corporation (Salt Lake City, UT, USA) — Independent supplier of X‑ray tubes and flat-panel detectors; a pivotal supplier that presents channel and M&A implications for OEMs aiming to secure component supply and technology differentiation.
- Carestream Health, Inc. (Rochester, NY, USA) — Provider of mobile X‑ray platforms and HD detectors, increasingly focusing on regulatory approvals and market expansion. (Recent: CE Mark for DRX‑Rise, Jan 2025.)
Recent market moves — product launches and regulatory milestones — reaffirm the pace of innovation. Examples include Siemens’ MULTIX Impact E and GE HealthCare’s Definium Pace Select ET launches during 2025, and United Imaging’s uDR Aurora CX debut. These rollouts reflect vendor strategies to capture both greenfield demand and replacement cycles with higher throughput and AI-enabled capabilities.
What our full report contains — practical, transaction-ready content
PW Consulting’s Diagnostic X‑Ray Imaging Market study is structured for decision-makers who need actionable outputs, not just descriptive analytics. Key deliverables include:
- Top‑down and bottom‑up market sizing with scenario analysis anchored on a 2025 base year and a 2026–2032 forecast horizon at a 5.6% CAGR assumption.
- Segment-level frameworks (by product type, application, and region) with drivers, adoption curves, and sensitivity analyses — presented as decision matrices to inform regional rollout or divestiture choices. (Note: granular segment tables and proprietary split data are accessible in the full report.)
- Competitive benchmark dashboards covering product features, go‑to‑market models, service portfolios, and contract archetypes for the top vendors and leading component suppliers.
- Regulatory and payer playbooks that translate Part F, FDA 21 CFR guidance, and reimbursement coding dynamics into procurement checklists, clinical-evidence requirements, and compliance milestones.
- Supply‑chain risk maps and supplier-sourcing options, including strategic scenarios for vertical integration, long-term supply agreements, and component substitution tradeoffs.
- M&A, partnership, and commercialization playbooks: target criteria, valuation multiples, and integration checklists tailored to buyers focused on technology, service expansion, or geographic access.
- Implementation tools: procurement scorecards, ROI and TCO calculators, and phased deployment roadmaps for converting pilot projects into enterprise-wide deployments.
Strategic implications and recommended actions for 2026
- Prioritize compliance-enabled differentiation: Vendors should embed regulatory evidence and assembler documentation workflows into product offerings to shorten sales cycles with large health systems that require installation reporting and regulatory traceability.
- Monetize services and software: Margins are shifting toward recurring revenue — invest in remote monitoring, predictive maintenance, and AI workflow modules that create annuity-like revenue streams and increase switching costs.
- Hedge supply risk proactively: Health system buyers and OEMs should execute dual-source strategies for critical components and consider contractual frameworks that share lead-time and inventory risk.
- Segment go‑to‑market tactically: Match product tiers to buyer needs — mobile DR and retrofit kits for capacity-constrained sites; high-throughput integrated systems for tertiary centers; scaled service bundles for regional networks.
- Use acquisitions strategically: For entrants and mid-tier players, targeted acquisitions of detector or tube specialists can accelerate time-to-market and margin expansion; for incumbents, bolt-on services providers can defend margins against commoditization.
How to use this research — recommended readership and next steps
This study is built for CEOs, product leaders, corporate development teams, procurement heads, and clinical engineering executives planning budgets, contract negotiations, or M&A activity in 2026. Use the executive summary and scenario roadmaps to align board-level decisions, and deploy the implementation toolkits to operationalize procurement and deployment decisions within 6–18 months.
To preserve strategic advantage, this introduction intentionally highlights drivers, vendor dynamics, and practical frameworks while withholding the detailed segment tables, regional/application split matrices, and proprietary company scorecards that underpin our actionable recommendations. Those core datasets and the full suite of implementation tools are available in the complete PW Consulting report — where quantitative granularity meets commercial playbooks.
Accessing the full intelligence
If your 2026 planning requires transaction-ready models, supplier scorecards, or regulatory playbooks tailored to your organization’s profile, PW Consulting can provide the complete Diagnostic X‑Ray Imaging Market report and bespoke advisory packages. The full deliverable contains the detailed segment-level data, regional and application breakdowns, and vendor benchmarking necessary to translate strategic intent into executable programs.
Contact PW Consulting to schedule a briefing and obtain the comprehensive datasets that inform capital allocation, partnership strategy, and product development priorities for the coming planning cycle.
For detailed analysis of this topic, please visit the official page: Diagnostic X-Ray Imaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com